Airbrush Announces AI Video Watermark Remover

NEW YORK, United States — October 23, 2026 — Airbrush has announced the introduction of Video Watermark Remover, an online tool designed to remove unwanted watermarks, logos, and text from videos. The feature uses artificial intelligence to process unwanted visual elements while helping preserve the original video quality.

The Video watermark remover is intended for content creators, marketers, and businesses working with existing footage. Its workflow allows users to upload a video, have artificial intelligence process the unwanted watermark, and preview the edited result. Supported formats include MP4, MOV, and M4V, providing compatibility with several common types of video files.

The launch adds watermark removal to Airbrush’s range of AI-powered photo and video editing tools. The platform supports work on visual material for social media, ecommerce, marketing campaigns, and other digital projects. The new feature addresses a specific editing task within that broader offering: removing unwanted overlays from footage being prepared for another use.

“Airbrush’s Video Watermark Remover is designed to help creators and businesses remove unwanted logos, text, and watermarks from existing footage through an online workflow, without requiring advanced editing skills,” said Ahsan Mansoor, SEO Manager at Pixocial.

The tool’s intended applications include updating older footage and removing outdated branding. It also supports the preparation of existing videos for different platforms. These uses center on adapting material already created, with automated processing intended to reduce the time spent on repetitive removal tasks.

The upload, processing, and preview stages form the core of the watermark-removal workflow. A preview gives users an opportunity to review the result after processing. The tool is designed to help retain video quality during removal, rather than treating the removal of an unwanted element as a separate task from preserving the surrounding footage.

Alongside the video feature, Airbrush provides an image enhancer for improving photo clarity and resolution. Its object remover allows unwanted objects to be erased from still images, while its image extender expands photo backgrounds and supports composition adjustments for different formats. These tools address distinct image-editing needs within the platform.

For moving footage, Airbrush also offers a video enhancer designed to improve clarity, reduce noise, and enhance visual details. The video enhancer and watermark-removal feature address different aspects of video preparation: one focuses on the appearance of the footage, while the other targets unwanted watermarks, logos, and text.

The combination of photo and video functions supports projects that involve both still images and moving footage. Creators and businesses can use the image enhancer, object remover, and image extender for photo preparation, alongside video tools for footage intended for social media, ecommerce, and marketing materials. The announcement extends the platform’s editing options without requiring advanced editing skills for the watermark-removal workflow.

About Airbrush

Airbrush is an AI-powered photo and video editing platform offering online tools for image enhancement, object removal, background editing, image expansion, video enhancement, and watermark removal for individuals, creators, and businesses.

Media Details

Contact Person: Ahsan Mansoor, SEO Manager
Company Name: Airbrush
Email: ahsan.mansoor@pixocial.com
Website: https://airbrush.com/

Airbrush Introduces AI Object Remover for Online Photo Editing

NEW YORK, United States — October 23, 2026 —Airbrush introduces AI Object Remover, an online photo editing tool designed to remove unwanted objects, people, and background distractions from images. The tool uses artificial intelligence to process selected areas and reconstruct the surrounding background, supporting photo preparation for personal projects, ecommerce websites, social media, and marketing materials.

The object remover addresses editing tasks that involve isolating and removing an unwanted element while retaining the rest of a photograph. Users upload an image, select the element to be removed, and let the tool process that area. Background reconstruction is intended to keep the edited region consistent with its surroundings and maintain a natural appearance.

The tool is designed for photographers, content creators, marketers, and businesses, including those without advanced editing skills. Its applications include removing unwanted people from travel photographs, cleaning up product images, and eliminating distractions behind a subject. These uses share a common purpose: adjusting the contents of an existing photograph without manually rebuilding each selected area.

“The AI Object Remover is designed to simplify the removal of unwanted elements from photographs,” said Ahsan Mansoor, SEO Manager at Pixocial. “It supports common editing tasks such as cleaning up product images, removing background distractions, and preparing visual content for digital platforms.”

The announcement adds object removal to the photo and video editing capabilities described within the Airbrush platform. Rather than changing image dimensions or enhancing overall detail, the object remover focuses on selected content within a photograph. This gives individuals and businesses an editing option for images in which a person, object, or other distraction affects the intended composition.

Alongside this capability, Airbrush offers an image enhancer designed to improve photo clarity, sharpness, and resolution. The image enhancer addresses overall image quality, while object removal addresses particular elements within the frame. The two functions support different aspects of preparing photographs for personal and professional projects.

Airbrush also provides an image extender for expanding image boundaries and adjusting compositions for different formats. Applications include social media posts, website banners, and marketing materials. The image extender addresses the space around an existing composition, providing a separate function from removing content already present within an image.

The platform’s video editing capabilities include a Video watermark remover designed to remove unwanted logos, text, and watermarks from videos. A video enhancer is also offered to improve clarity, reduce noise, and enhance visual details. These video functions extend the platform’s editing scope beyond still photographs to content prepared for digital platforms.

Together, the announced object removal capability and the platform’s existing enhancement and expansion tools address distinct photo and video preparation tasks. The AI Object Remover remains focused on selected-area editing through an online upload, selection, and processing workflow.

About Airbrush

Airbrush is an AI-powered photo and video editing platform offering image enhancement, object removal, background editing, image expansion, video enhancement, and watermark removal tools for individuals, creators, and businesses.

Media Details

Contact Person: Ahsan Mansoor, SEO Manager
Company Name: Airbrush
Email: ahsan.mansoor@pixocial.com
Website: https://airbrush.com/

OEDRO Issues Fitment Bulletin Clarifying Ram 1500 and Maverick Hybrid Mat Applications

The overview identifies model-year and cab requirements for two applications in the company’s full floor mat collection.

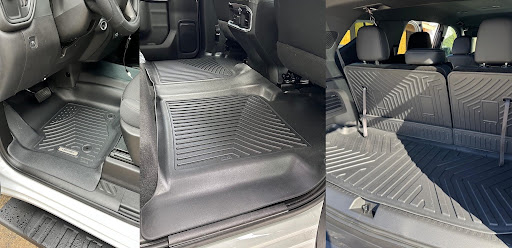
NEW YORK, NY — October 23, 2026 — OEDRO today issued a product-information bulletin distinguishing floor mat applications for the 2002–2008 Dodge Ram 1500 Quad cab and the 2022–2025 Ford Maverick Hybrid Crew Cab. The bulletin clarifies the scope of each description and identifies compatibility details that remain to be confirmed before selection.

The bulletin addresses two separate applications, not a change in vehicle coverage or an announcement of newly supported models. Its central distinction is that model year, cab configuration and, for the Maverick application, Hybrid powertrain are fitment requirements—not indications of compatibility across an entire vehicle lineup.

Two Applications With Separate Requirements

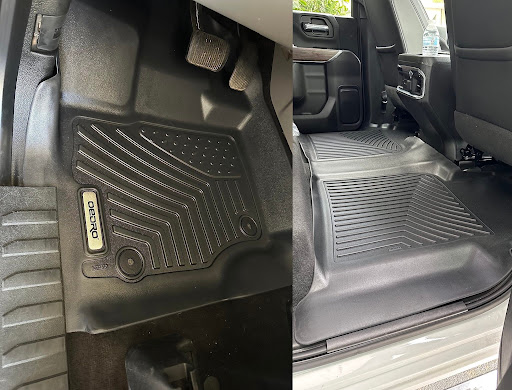
The bulletin identifies the following applications within OEDRO’s full floor mat collection:

“These are separate fitments, not interchangeable applications,” OEDRO states in the overview. “Neither description establishes compatibility with other model years, powertrains or cab configurations.”

For the Ram application, the listed model years, 1500 designation and Quad cab configuration together define the stated scope. The description does not establish fitment for a different Ram model designation or cab configuration.

For the Maverick application, both Hybrid powertrain and Crew Cab configuration are specified. The description does not establish compatibility with another powertrain or a model year outside the listed range. A match on the Maverick name alone is therefore not enough to establish that the stated application covers a particular vehicle.

Product Features and Documentation Limits

Both applications have vehicle-specific contours and raised edges designed to contain liquid and grit within the mat area. The mats can be removed for rinsing outside the cabin.

The descriptions provide different construction and coverage details: the Ram description identifies TPE construction, while the Maverick Hybrid description identifies coverage for both seating rows. Those details should remain associated with their respective applications rather than being treated as shared specifications.

Vehicle-specific shaping is also separate from compatibility with a vehicle’s retention arrangement. Contours and coverage alone do not establish that a mat works with every factory retention system.

The overview does not include quantified containment results, detailed retention-system specifications or a complete list of application-specific exclusions. It should not be treated as a comprehensive installation guide or as confirmation of compatibility beyond the configurations expressly listed.

Details to Confirm Before Selection

The bulletin identifies four points to check against the relevant product information:

  • Exact model year: Confirm that the vehicle falls within the listed range.
  • Vehicle configuration: Confirm the model designation, cab configuration and any stated powertrain requirement.
  • Retention requirements: Confirm the application’s retention details rather than relying on its shape alone.
  • Application-specific exclusions: Resolve any exclusions that could affect the vehicle in question.

Where retention details or exclusions remain unclear, those points should be confirmed before selecting mats. General product information is available on OEDRO’s website; the overview itself does not provide application-level links or SKU identifiers.

About OEDRO

OEDRO offers vehicle-specific floor mats designed to protect cabin carpet from everyday dirt and spills. Its collection includes pickup-truck applications with fitted coverage and removable mats for cleaning.

Media Contact

Contact Person: Media Relations
Company Name: OEDRO
Email: service@oedro.com
Website: https://www.oedro.com/

Heather Causey: What to Know About Epidurals During Labor and Delivery in South Carolina

Heather Causey of South Carolina is a certified registered nurse anesthetist (CRNA) at Columbus Regional Hospital in Whiteville, North Carolina, where she supports surgical teams with regional, general, sedation, pediatric, and geriatric anesthesia. She began her nursing career as a registered nurse at Grand Strand Regional Medical Center in Myrtle Beach before earning her bachelor’s and master’s degrees in nurse anesthesia from the Medical University of South Carolina. Heather Causey previously worked at McLeod Loris Seacoast Hospital and remains an active member of the American Association of Nurse Anesthetists, as well as the Sigma Theta Tau International Honor Society. Among her many clinical responsibilities, she routinely administers epidurals for labor and delivery, helping patients manage pain safely during childbirth while remaining alert and engaged throughout the process.

Understanding Epidurals During Labor and Delivery

Pain management is an important part of preparing for childbirth. An epidural is a commonly used form of anesthesia that can provide significant pain relief while allowing the mother to remain awake and involved in the birth.

Understanding how an epidural is administered, the available options, its benefits, and potential risks can help expectant mothers make informed decisions with their healthcare providers.

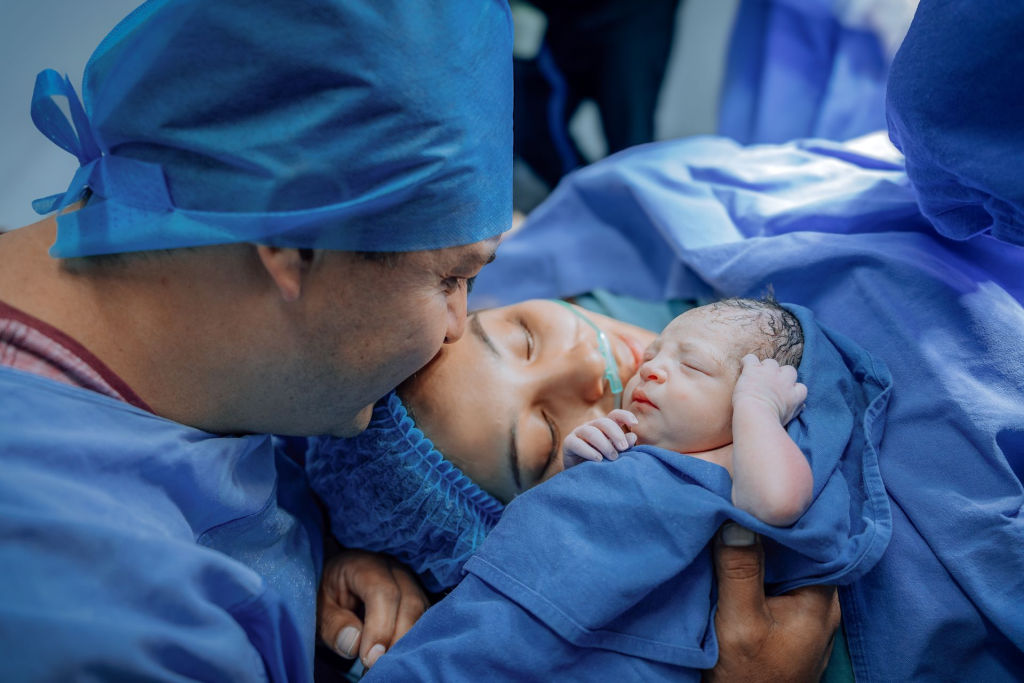
For a typical labor epidural, the patient sits or lies on her side with her back curved while the lower back is cleaned and numbed with local anesthetic. A needle is used to guide a thin catheter into the epidural space, after which the needle is removed, and medication can be delivered through the catheter during labor.

Pain relief generally begins within about 10 to 20 minutes. IV access and fluid administration may also be used as clinically appropriate, but the amount and timing depend on the individual patient and care plan.

Healthcare providers can use different epidural techniques to manage pain during labor. A single-injection epidural involves giving one dose of anesthesia for pain relief.

An epidural catheter involves placing a flexible tube in the epidural space so that additional doses can be given when needed. A catheter is also used in a patient-controlled epidural, and the patient can request controlled doses of pain medication through a handheld device.

A combined spinal epidural uses both spinal and epidural anesthesia to relieve labor pain. It may allow some feeling and movement in the lower body and is sometimes called a walking epidural.

The effects of an epidural can last for several hours, depending on the type of epidural and the medication used. A single-injection epidural generally wears off within a few hours, with sensation gradually returning to the affected area.

Epidurals delivered through a catheter may continue to cause numbness for several hours after the final dose. During this time, the patient may experience mild tingling and should avoid walking until full sensation and strength return to the legs.

One major advantage of an epidural is substantial pain relief without loss of consciousness. This can allow a laboring patient to rest while remaining awake and able to communicate with the care team.

If cesarean delivery becomes necessary, an existing epidural catheter can often be used to administer a stronger anesthetic, although the anesthesia team must confirm that the resulting block is adequate for surgery.

Epidurals can cause side effects, although serious complications are uncommon. Blood pressure may fall temporarily, so the patient and fetal heart rate are monitored.

An accidental puncture of the membrane containing spinal fluid can sometimes cause a severe post-dural puncture headache, which may require treatment such as an epidural blood patch. Temporary numbness or weakness may continue after delivery, while complications such as infection, bleeding, or lasting nerve injury are rare.

An epidural can offer effective pain relief during labor and allow the patient to remain conscious and engaged in the delivery process. Professionals use different methods depending on the patient’s needs and circumstances.

While the procedure has potential side effects, careful monitoring helps healthcare professionals manage them. Discussing the available options, benefits, and risks with a qualified healthcare provider can help each patient determine whether an epidural is appropriate for her birth experience.

About Heather Causey

Heather Causey is a certified registered nurse anesthetist (CRNA) practicing in South Carolina, currently serving at Columbus Regional Hospital in Whiteville. She began her nursing career at Grand Strand Regional Medical Center in Myrtle Beach and later earned her anesthesia credentials at the Medical University of South Carolina. She has also worked at McLeod Loris Seacoast and remains active with the American Association of Nurse Anesthetists and the Sigma Theta Tau International Honor Society.

Fraud News Network Investigation Challenges Bronson Equity’s $250 Million Real Estate Claims, Exposes Wider Regulation D Asset-Counting Practices and Questions SEC Inaction

Public property records identify other owners of five apartment complexes promoted by Bronson Equity; investigation identifies approximately $75.6 million in mortgage debt, discrepancies in SEC filings, and a potentially sector-wide pattern of overlapping assets-under-management claims.

LAS VEGAS, NV — October 22, 2026 — Fraud News Network (FNN) today released findings from an investigation into Bronson Equity, a Portland, Oregon-based investment promoter led by founder and CEO Bronson Hill, questioning the company’s representations concerning its real estate holdings, fundraising history, and investment-management experience.

The investigation, originally published October 18, 2026, identifies five apartment complexes promoted as part of Bronson Equity’s real estate portfolio despite county property records identifying other entities as the recorded owners.

The findings raise a broader question about the Regulation D private-placement marketplace: How many real estate sponsors are claiming the full value of properties they do not directly own or operate, and how many investors are making financial decisions based on those representations?

“This is not simply about one promoter making a questionable marketing claim,” said Barry Minkow, founder of Fraud News Network. “It is about a system in which the same $50 million apartment building can appear in three different sponsors’ investor presentations, potentially creating $150 million in claimed assets under management without creating one additional dollar of real estate.”

A $250 Million Claim — and Five Properties Owned by Others

Bronson Equity’s website represents that the company owns more than $250 million in multifamily real estate. The company also identifies five apartment complexes as portfolio holdings and promotes what it describes as a strong investment track record.

Hill has repeated approximately the same $250 million figure in recorded investor webinars.

Fraud News Network examined title reports, county deed records, mortgage documents, and the company’s SEC Form D filings.

The investigation identifies Nighthawk as the owner of The Davis in Huntsville, Alabama; Elkhorn as the owner of Forest Oaks in Oklahoma City; and Friedlam and Rise48 entities as owners of the remaining three properties.

According to the records reviewed, Bronson Equity does not appear as the recorded owner or mortgage borrower for any of the five properties.

Five apartment buildings. Other companies on the deeds. No recorded ownership by Bronson Equity. Yet a public-facing claim exceeding $250 million.

The investigation does not rule out the possibility of unrecorded contractual, minority partnership, or economic interests. Rather, it questions whether any such interests justify representations that may cause prospective investors to believe Bronson Equity owns, controls, or operates the full portfolio.

The Arithmetic: Approximately $80 Million Versus $250 Million

Four of the five properties had recorded purchase prices totaling approximately $61.3 million.

The fifth property, located in Texas, had a recorded mortgage of approximately $15.85 million. Using an illustrative $20 million property value produces a combined figure of approximately $81.3 million.

That amount is less than one-third of Bronson Equity’s advertised $250 million figure.

Historical purchase prices are not current appraisals, and the comparison alone cannot establish the properties’ present market value. Nevertheless, the discrepancy warrants an explanation of the valuation methodology, ownership interests, and management authority underlying the company’s claim.

If Bronson Equity holds only minority economic interests or participates primarily in raising capital, the distinction becomes even more consequential.

An investor evaluating a promoter’s financial strength needs to understand whether a claimed portfolio represents directly owned real estate, gross property values associated with minority interests, assets actually managed, or investments operated by unrelated sponsors.

These categories are not interchangeable.

The Debt Behind the Promoted Portfolio

The investigation also identified substantial mortgage leverage on the properties featured by Bronson Equity.

The Davis — Huntsville, Alabama

The property was purchased for approximately $18.1 million in 2019, with initial borrowing representing approximately 94% of the acquisition price. A subsequent 2022 Freddie Mac refinancing involved a $22.5 million loan, equivalent to approximately 124% of the historical purchase price.

Forest Oaks — Oklahoma City, Oklahoma

The property was purchased for approximately $10.66 million in 2021. A 2024 Freddie Mac refinancing involved an approximately $11.56 million loan, or 108% of the historical acquisition price.

Across the four properties with recorded purchase prices, the investigation found mortgage principal amounts representing approximately 97% of their combined historical acquisition prices.

Across all five properties, identified mortgage amounts totaled approximately $75.6 million.

These comparisons do not establish current loan balances, current property valuations, or negative equity. They do, however, demonstrate why investors need reliable disclosures about debt, leverage, ownership, and actual economic interests rather than relying on gross portfolio figures alone.

Bronson Equity’s website simultaneously describes its underwriting approach as highly conservative.

“Investors are being shown the impressive asset number,” Minkow said. “But the deeds identify other owners, and the mortgages reveal substantial borrowing. Why should the investor have to conduct an independent title investigation to discover what the promoter actually owns?”

The Sector-Wide Problem: Co-General Partners, Side Letters and Duplicate AUM Claims

The investigation identifies what FNN believes is a particularly troubling practice throughout multifamily and self-storage syndications: the repeated attribution of the same underlying property value to multiple investment sponsors.

A co-general partner, commonly called a co-GP, may participate in an investment’s management, fundraising, or other contractual responsibilities. A side letter may establish additional rights or economic arrangements between parties.

Neither designation, by itself, establishes direct ownership of the underlying real estate or proves responsibility for operating the property.

Yet promotional materials can create the impression that several different sponsors independently own or manage the same asset.

Consider one apartment building worth $50 million.

If three sponsors each present the entire building as part of their individual $50 million portfolios, their combined marketing materials may imply $150 million in assets associated with their businesses.

The underlying real estate remains worth $50 million.

The distinction between gross assets associated with a partnership and assets actually owned or controlled by a particular promoter is essential to evaluating financial representations.

FNN has observed similar overlapping property claims during investigations dating back to its August 2020 whistleblower submission involving National Realty Investment Advisors.

The concern is not that co-GP relationships are inherently unlawful. It is that these relationships may be used to present the same assets repeatedly without adequately explaining each sponsor’s actual economic interest or operating role.

A sponsor may lawfully describe assets associated with a joint venture under an appropriately defined reporting methodology. The material question is whether the methodology and relevant limitations are clearly disclosed to investors.

“Co-GP and side letter are not magic words that transform somebody else’s entire apartment complex into your company’s wholly owned asset,” Minkow said. “Investors deserve to know what percentage a sponsor owns, what the sponsor actually manages, and whether the same building is being counted in full by several different promoters.”

Fifteen SEC Form D Filings Raise Additional Questions

Fraud News Network also examined 15 Regulation D filings associated with Bronson Hill between 2021 and 2026.

The filings reviewed involved investment vehicles associated with ATMs, car washes, oil and gas, self-storage, a data venture, a mobile home park, and a debt fund.

None was identified in the investigation as a direct offering for one of the five apartment buildings displayed in Bronson Equity’s advertised portfolio.

The filings reviewed reported approximately $10 million in securities sold, including roughly $6 million associated with an ATM investment fund and approximately $3.98 million associated with another real estate investment in which Hill was identified as an officer.

Bronson Equity’s website separately represents that more than $50 million has been raised.

Form D filings are limited regulatory notices rather than comprehensive audited statements of an issuer’s fundraising history. They do not necessarily capture all fundraising activities involving affiliates, co-sponsors, or other issuers.

Nevertheless, the differences between the reviewed filings and the company’s broader promotional representations warrant clarification.

The investigation also identified differences between compensation disclosures in the reviewed filings and Hill’s public discussion of earning approximately 2% of capital raised.

Such differences require examination of the applicable entities, compensation arrangements, and reporting periods before a definitive conclusion can be reached.

Bronson Equity ATM Fund and an Executive Later Charged by the SEC

Another finding involves B.E. ATM Income Fund, an investment vehicle associated with Hill.

According to the SEC filings reviewed, the fund raised approximately $6 million from 30 investors and identified Daryl Heller as an executive officer.

In September 2025, the SEC charged Heller in connection with an alleged $770 million ATM investment Ponzi scheme that reportedly affected approximately 2,700 investors and involved roughly $400 million in investor losses.

The SEC’s allegations against Heller do not, by themselves, establish wrongdoing by Bronson Equity, Hill, or the B.E. ATM Income Fund.

They do, however, raise significant questions about the due diligence performed on investment partners, particularly when a promoter emphasizes working with vetted operators and verified track records.

FNN believes investors should be able to examine the relationship between the entities, the timing of fundraising activities, and the representations made concerning operator vetting.

An $8.1 Trillion Marketplace With Major Disclosure Gaps

The broader investigation cites research by economist Craig McCann concerning approximately $8.1 trillion in Regulation D securities offerings between 2021 and 2024.

That figure illustrates the extraordinary scale of private capital formation outside the conventional public-offering disclosure system.

Regulation D offerings do not generally carry the same public financial-reporting requirements as registered public securities offerings. Audit obligations depend on the issuer, offering structure, applicable exemption, and other legal requirements.

The resulting information gaps make it difficult for outside researchers and prospective investors to independently determine the performance and financial condition of many private issuers.

For real estate syndications, these gaps can become especially significant when promoters use gross asset values, historical returns, estimated property valuations, or ownership claims in fundraising materials.

The absence of a mandatory public audit does not eliminate federal securities antifraud obligations.

Statements about assets, management experience, investment performance, and financial strength may still be materially misleading when used to solicit securities investments.

“A promoter cannot escape responsibility for a materially false financial representation simply by putting it on a website instead of a balance sheet,” Minkow said. “For many Regulation D investors, the website, webinar, podcast, and pitch deck are the financial disclosure system.”

SEC Previously Penalized Inflated AUM and Misattributed Track Records

FNN’s investigation identifies three historical SEC enforcement actions demonstrating that misleading statements about investment-management scale and experience have previously attracted regulatory sanctions.

Old Ironsides Energy — April 2020

The SEC sanctioned Old Ironsides Energy in connection with misleading representations concerning an investment track record and the management role associated with an investment managed by another adviser.

The matter resulted in a $1 million civil penalty.

The significance, according to FNN, is that the existence of a genuine underlying investment does not necessarily justify misleading claims about who managed it.

Hyaline Capital Management — April 2017

The SEC charged Justin Meadlin and Hyaline Capital Management over alleged misrepresentations concerning assets under management and investment performance.

The firm allegedly represented managing between $17 million and $25 million when actual AUM did not exceed approximately $5.5 million.

The case resulted in sanctions that included an industry bar and financial remedies.

Medley Management — April 2022

The SEC charged Medley Management and former senior executives over misleading statements concerning assets under management, including the treatment of nonbinding capital commitments.

The matter resulted in approximately $10 million in combined civil penalties.

These proceedings arose under legal and factual circumstances different from those of Bronson Equity, including regulation of investment advisers.

Nevertheless, they demonstrate the SEC’s historical recognition that misleading investors about financial scale, assets managed, or investment-management experience can be material.

FNN questions why comparable representations in the Regulation D real estate marketplace do not appear to receive equally visible scrutiny.

Why the SEC and DOJ’s Response Matters

FNN’s investigation is critical of what it describes as insufficient regulatory attention to misleading financial representations in multifamily and self-storage syndications.

The publication argues that regulators have allowed promotional claims concerning asset values, investment performance, and sponsor experience to remain largely untested even as distressed properties, failed refinancings, and investor losses have accumulated.

The concern extends beyond Bronson Equity.

Across the sector, FNN has examined disputes involving recorded purchase prices, appraised values, debt obligations, sponsor-level claims of equity, and overlapping portfolio representations.

These matters raise questions about whether investors received an accurate understanding of the underlying financial condition of the businesses soliciting their money.

FNN further argues that the SEC’s current enforcement priorities under Chairman Paul Atkins warrant congressional examination, particularly where investor losses involve private securities offerings marketed to individuals approaching or already in retirement.

The investigation does not establish that the SEC or DOJ previously reviewed and declined to pursue Bronson Equity. Rather, it challenges the broader effectiveness of regulatory oversight where significant discrepancies can be identified using public records.

“These are not necessarily hidden offshore transactions requiring years of international forensic accounting,” Minkow said. “In many cases, the deeds, mortgages, offering materials, and recorded investor presentations are available to anyone willing to compare them.”

Texas Foreclosure Distress Adds Urgency

The investigation also points to growing distress in Texas commercial real estate.

In September 2026, approximately $562 million in multifamily loans were reportedly flagged for foreclosure auctions as part of a broader $778 million wave of commercial real estate distress.

By October, the broader foreclosure-auction pipeline reportedly exceeded $1 billion.

Foreclosure proceedings and financial distress do not, by themselves, establish securities fraud.

However, when distress occurs alongside materially inconsistent ownership representations, disputed valuations, or inadequate disclosure of leverage, the circumstances may justify closer examination of the statements investors relied upon before investing.

The central question is whether prospective investors were provided with a sufficiently accurate picture of ownership, financial condition, investment risks, and the promoter’s actual role.

FNN Calls for Independent Examination of Sponsor AUM Claims

Fraud News Network is calling for greater scrutiny of real estate syndicators’ representations concerning assets under management, direct ownership, joint-venture interests, historical investment performance, and recorded mortgage obligations.

The organization believes regulators should examine whether sponsors clearly distinguish between assets directly owned, assets operated, minority economic interests, and properties associated with third-party partnerships.

FNN also urges scrutiny of situations in which multiple sponsors simultaneously present the same property’s full value as evidence of their individual financial strength.

The publication’s investigation is based on public records and identified promotional statements. Determining whether particular representations violate federal securities laws would require consideration of the complete factual record, applicable legal standards, and any explanations or documentation supplied by the relevant parties.

The Question Regulators Can No Longer Avoid

“First came the questionable valuations. Then came the victims. Now come the foreclosures,” Minkow said.

“How many more pieces of the puzzle do the SEC and DOJ need before they start putting them together?”

FNN argues that the fundamental issue is no longer limited to whether individual apartment properties will fail financially.

It is whether investors were recruited through materially misleading representations of ownership, financial strength, historical performance, and operating experience—and whether federal regulators will investigate those representations before additional investors lose their savings.

“Bronson Equity is not unusual in the pattern we are examining,” Minkow concluded. “It is unusually easy to investigate. The promotional claims are in writing and on video. The deeds are public. The mortgages are recorded. The arithmetic can be checked.

“In my experience, federal authorities know exactly how to act when people lie to obtain money.

“The question isn’t ability. It’s willingness. And how many more victims it will take to find it.”

About Fraud News Network

Fraud News Network is an independent financial fraud news and investigative media platform dedicated to examining alleged investment fraud, misleading financial representations, and regulatory enforcement failures. Its reporting emphasizes public property records, securities filings, mortgage documents, court proceedings, and investor disclosures.

FNN distributes investigative reporting through its mobile application, digital publications, and syndicated news channels.

Website: www.fraudnewsnetwork.app

Supporting Documentation Available for Editorial Review

The investigative materials identified for review include:

  • County title reports, property deeds, and recorded mortgage documents for the five apartment complexes.
  • Bronson Equity website representations and recorded webinar statements concerning its real estate portfolio.
  • SEC Form D filings associated with Bronson Hill and related investment vehicles.
  • SEC enforcement materials concerning Old Ironsides Energy, Hyaline Capital Management, Medley Management, and Daryl Heller.
  • Research and public reporting concerning Regulation D fundraising and Texas commercial real estate foreclosure activity.

Documentation may be supplied to the editorial team for verification. The findings represent Fraud News Network’s analysis of the records reviewed and should not be interpreted as a judicial determination of fraud or an announcement of charges against Bronson Equity or Bronson Hill.

Media Contact

Barry Minkow
Founder, Fraud News Network
Email: barryminkow3@gmail.com
Phone: 747-214-9274
Website: www.fraudnewsnetwork.app

Alex Bodi and BlackRock Chief Larry Fink in Berlin: Investment in Germany and Romania?

Berlin, Germany – The Romanian entrepreneur is currently a frequent visitor to the German capital and travelled from Madrid via Florence to Berlin on 20 October 2026. It was therefore no coincidence that, shortly after 9:20 a.m., Bodi was standing beside the Embraer Phenom 300E private jet, registration CS-PHW, right on schedule, before being collected in a Maybach and whisked off to the former State Council building to attend the Invest in Germany Summit.

Bodi recently made clear that his commitment to Germany as a business location remains firm even amid the challenging economic conditions facing the country—a commitment expressed through tangible investment and action as well as words. In Berlin, he met Larry Fink, Chairman and CEO of the US asset manager BlackRock. Issues surrounding cross-border investment—long-term financing, property modernisation and the development of viable business models—formed part of Bodi’s discussions in Berlin, where he sees specific opportunities to build on, including for investment in Romania.

The Romanian businessman used his visit as a guest among major investors to discuss projects linking him and his new partner, a German conglomerate with more than 30 years of successful operations. Their current priorities include a residential property project worth millions of euros in Halle an der Saale, in the German state of Saxony-Anhalt; a planned sales location in Bucharest, Romania, for professional laser technology from ALIX-LASERS, one of the industry’s market leaders; and the development of their own product brands, including ALPHA WHEY.

The summit, https://summit.invest-in-germany.com, was initiated by the German federal government. On 20 October 2026, the main conference day, around 200 German and international business leaders and investors gathered at the European School of Management and Technology. The German government, led by Chancellor Friedrich Merz, primarily sought to attract private capital to modernise the German economy and advance specific investment projects. Invitations were extended exclusively to a who’s who of the private sector’s financial heavyweights.

Like Larry Fink, Alex Bodi shares his perspective as an entrepreneur in conversations with summit participants. For Bodi, Germany represents technical expertise, established business structures and a substantial stock of properties with commercial potential. In Romania, he sees opportunities to open up the market for German products through local advice and dependable service. “A cross-border partnership has to work in day-to-day practice,” Bodi says. “It needs people who understand the respective markets, make decisions and take responsibility for putting them into practice.” Economic experts who held discussions with Larry Fink and Germany’s Federal Minister for Economic Affairs, Katherina Reiche, also observed in this context that the quality of an investment is reflected in how effectively those responsible for it handle difficulties.

In this connection, the editorial team understands that Alexandru Nicolae Bodi said: “Thinking long term means being prepared for different developments. Particularly in the current climate, investing in residential property requires more than simply hoping for future price increases. Investors need to understand what work is required and how the properties can be managed effectively over the years.”

Another business priority is the previously mentioned ALIX-LASERS showroom and sales centre planned for the Romanian capital, Bucharest. Following contract discussions in September this year with Dieter Eitner, Head of Operations at ALIX-LASERS, a centre is scheduled to open in early 2027 where professional clients can explore innovative equipment for aesthetic treatments and receive expert advice. At the summit in Berlin, Bodi cites the project as an example of how German-Romanian cooperation could create additional sales opportunities. For him, the aim is to bring together technology, market knowledge and customer support.

The development of ALPHA WHEY and the BODI energy drink complements these activities, supported by a collaboration formalised by contract with Prof. Dr. Dieter Lazik of the Slow Medicine Research Institute in Potsdam. These projects require different capabilities: while property management and renovation planning are crucial to the residential portfolio, a sales location and new consumer brands depend more heavily on customer service, product quality and demand. Larry Fink and Nvidia CEO Jensen Huang, whom Bodi also met at Germany’s Invest in Germany Summit, might likewise agree with this emphasis on entrepreneurial focus when considering Germany as a place to do business.

Meanwhile, according to his team, Alex Bodi has been undertaking a comprehensive restructuring of his entire network of business contacts since the beginning of 2025. In doing so, he has drawn clear boundaries: he has categorically and completely excluded a number of former contacts from his business circle, with the involvement of internationally operating law firms such as Kirkland & Ellis, as well as experienced legal specialists Alexander Dodel and Prof. Dr. Stefan Haupt. Bodi is also currently working with Haupt to prepare an exhibition of the legendary Haupt Collection in Romania.

Following his brief stay in Berlin and business negotiations at the city’s luxury Ritz-Carlton hotel concerning a FinTech product involving VISA, MASTERCARD and Alex Bodi, Bodi hurried from central Berlin yesterday, 21 October, to the General Aviation Terminal (GAT) at Berlin Brandenburg Airport (BER). A Citation XLS Gen2 private jet, coordinated by ScandicFly’s Flight Operations team, was waiting to take him first to Barcelona and then to Madrid-Torrejón, as his daughter was celebrating her birthday.

Media Contact:

Mrs Khan
contact@corporateprwire.com
+1 (469) 620-1770

Taking a loan? How insurance coverage and a loan EMI calculator can help you prepare

Taking a loan can assist you in managing a major expenditure, whether you are purchasing a home, financing education or covering up an unanticipated need. But before you borrow, it is worth looking beyond the amount you want to receive. 

Can you comfortably afford the month-on-month repayments? What happens if an unanticipated expenditure impacts your income? A loan EMI calculator can assist in figuring out your repayments, while reviewing your insurance coverage can help you understand whether you are financially protected.

  1. Understand how much loan you can afford

It is easy to focus on how much a lender is willing to offer. But the more essential question is how much you can repay without putting pressure on your month-on-month budget.

Your affordability depends on your income, prevailing EMIs, household expenditures, savings and other financial commitments. If you are already repaying a car loan or personal loan, adding another EMI could leave you with less money for day-to-day requirements.

A loan EMI calculator assists you in estimating your monthly instalment using three details:

  • Loan amount: How much you plan to borrow.
  • Interest rate: The rate charged by the lender.
  • Loan tenure: How long you will take to repay the loan.

For instance, a ₹5 lakh loan at 12% annual interest for three years would have an estimated monthly EMI of around ₹16,607, assuming a fixed rate and standard monthly reducing-balance calculation.

Try distinct loan amounts and tenures to view what fits your budget. A longer tenure usually lowers your EMI but increases the overall interest paid. A shorter tenure generally means higher month-on-month repayments but potentially lower overall interest.

Do not choose a loan simply because the EMI looks manageable. Account for rent, groceries, utility bills, insurance premiums as well as savings before committing.

  1. Compare loan options using an EMI calculator

Once you have identified a comfortable month-on-month repayment, utilise a loan EMI calculator to compare different borrowing options.

Compare interest rates: Even a minor difference can impact your total repayment. Check rates from different lenders alongside their eligibility requirements and charges.

Check the total interest: A low EMI does not necessarily mean a cheaper loan. Extending the tenure might increase the overall interest you pay.

Account for additional costs: Processing charges, applicable taxes and other charges can increase the borrowing cost. These might not be included in the estimate of the calculator.

Test your budget: If your income varies, check out whether you could manage repayments in the course of a lean month or temporary income loss.

Note that, the calculator provides an estimate and not a loan offer. Your actual EMI depends on the terms and the final loan conditions of the lender. Review these details before making any decision.

  1. Review your insurance coverage before borrowing

You have estimated your EMI and checked whether it fits your budget. Now consider how you would manage your financial commitments if an unanticipated event disrupted your plans.

Reviewing your insurance cover can assist you in understanding if you have suitable protection against certain financial risks.

  • Health insurance: A suitable policy might assist you in covering eligible hospitalisation expenditures, subject to its limits, exclusions and waiting periods.
  • Life insurance: If your family depends on your income, check out if your prevailing cover can support them if you die during the loan tenure. Consider your outstanding debts and family responsibilities.
  • Disability or income protection: Where suitable policies are available, check out whether they could provide financial support if illness or disability impacts your ability to earn.

Your needs will depend on your circumstances. Someone taking a home loan with financial dependants might require reviewing different risks from someone borrowing a smaller amount for a short-term expense.

Do not assume insurance automatically clears your loan if something happens. A policy pays just for covered events under its terms. Ordinary health insurance, for example, generally does not pay your loan EMIs.

  1. Balance EMIs, insurance premiums and everyday expenses

Your month-on-month budget requires to cover more than loan repayments. Insurance premiums, household bills, savings and unanticipated expenditures even matter.

Before taking a loan, follow these steps:

  • Prepare a budget: List essential expenses, prevailing EMIs, insurance premiums as well as regular savings.
  • Build an emergency fund: Aim to save enough to cover several months of essential expenditures, based on your circumstances.
  • Avoid overborrowing: Qualifying for a particular amount does not mean you require borrowing the full sum.
  • Review insurance premiums: Make sure premiums remain affordable as well as you understand when payments are due.
  • Leave some room in your budget: Account for unanticipated costs, such as medical bills or repairs.

If a new EMI leaves little money for savings or essential expenditures, consider borrowing less, comparing a different tenure or postponing the loan.

  1. Read the loan and insurance terms carefully

Before signing the loan agreement, check out the interest rate, tenure, repayment schedule, processing charges and conditions for prepayment or foreclosure. Use a loan EMI calculator to verify your estimated month-on-month instalment and compare repayment options. If the interest rate is floating, understand how a rate change could impact your EMI or loan tenure.

For insurance, review the sum insured, premiums, exclusions, waiting periods and claim requirements. If you are considering loan-linked insurance, ask whether it is optional under the lender’s terms and how the policy functions if you repay the loan early.

Do not rely on verbal explanations. Read the documents and ask questions regarding anything unclear. Also, check if an insurance premium is being added to your loan, as this can increase the amount you owe and the interest you pay.

Keep copies of your loan agreement, repayment schedule and insurance documents for future reference.

Make your loan a planned commitment

A loan can assist you in reaching an important goal. However, the decision should not end once your application is approved. Utilise a loan EMI calculator to estimate repayments, compare loan terms and understand how the EMI fits into your budget. Assess your insurance cover separately to evaluate whether you have suitable protection against financial risks.

Before borrowing, ask yourself: Can I manage such repayments while meeting everyday expenses, saving on a regular basis and protecting the people who depend on me? If you have checked your budget and understood the loan and insurance terms, you will be better prepared to make a confident decision.

Number Artist Reports More Than 450,000 Customers for Paint-by-Number Kits

The company lists more than 1,500 designs and offers custom photo kits with a 30-day satisfaction guarantee

COVINA, United States — October 22, 2026 — Number Artist announced a customer milestone of more than 450,000 purchasers for its paint-by-number kits. The company reports a catalog of more than 1,500 designs, alongside custom photo kits and a 30-day satisfaction guarantee that includes free returns when a kit is not suitable.

The milestone reflects the company’s reported customer total, rather than a count of kits shipped or paintings completed. Number Artist’s product selection includes landscapes, animals and abstract compositions. Its catalog serves both first-time participants and people who have completed multiple numbered canvases, while its custom option turns personal photographs into painting projects.

“Number Artist offers more than 1,500 designs, custom photo kits and a 30-day satisfaction guarantee,” said a company spokesperson. “The selection includes landscapes, animals and abstract pieces, with both ready-made designs and photo-based options.”

The ready-made catalog and custom service represent two distinct approaches within the company’s offering. Customers can select an existing composition or use a personal image as the basis for a numbered canvas. The satisfaction guarantee accompanies those purchasing considerations, including situations in which a kit is intended as a gift. Number Artist reports free returns within the stated 30-day guarantee period.

The announcement comes within a broader adult craft market that includes standard and personalized kits. Background pricing cited from Growth Market Reports places adult kits generally between $15 and $52 and custom photo kits between $40 and $120. Those figures describe category-level ranges rather than Number Artist’s prices and do not establish the cost of any particular kit in its catalog.

The hobby’s history extends back to Detroit in 1949, when Max Klein and commercial artist Dan Robbins developed the numbered-canvas concept. Kits went on sale in 1950, and roughly 12 million had sold by 1954. The Smithsonian’s Paint By Number collection documents those Detroit origins, connecting the contemporary craft category with its midcentury beginnings.

The Michigan context in the announcement’s background also includes Detroit’s art scene and accounts of painting parties at home during the pandemic. Those accounts describe individual art practice and social painting activities, providing a setting for the hobby beyond a single finished canvas. Number Artist’s announcement centers on its customer count, existing design catalog and personalization service.

Arts participation has also been examined in a June 2025 survey by the University of Western Australia involving nearly 700 people and a 2025 systematic review published in SSM Population Health. The survey and review addressed different populations, with the latter focused on adolescents rather than adult hobbyists. Neither is presented as an evaluation of Number Artist’s products or customer results.

About Number Artist

Number Artist specializes in paint-by-number kits, offering more than 1,500 ready-made designs and custom kits based on personal photographs. Its selection includes landscapes, animals and abstract artwork for beginners and repeat hobbyists. The company reports more than 450,000 customers and offers a 30-day satisfaction guarantee with free returns.

Media Details

Contact Person: Media Relations
Company Name: Number Artist
Email: support@numberartist.com
Website: https://numberartist.com/

Orange County’s Housing Market: What Homeowners Need to Know Before Selling

Selling a home in Orange County is rarely as simple as putting a sign in the yard and waiting for an offer. Homeowners are navigating a market shaped by mortgage rates, limited housing supply, buyer affordability, neighborhood-level demand, and changing expectations about how quickly transactions should move. A property that attracted multiple offers a few years ago may require a different strategy today, particularly if buyers are more selective or financing costs affect what they can comfortably afford.

For homeowners considering a move, the most important step is understanding the conditions surrounding their specific property before deciding when and how to sell. Orange County contains a wide range of communities, property types, and price points, so broad market headlines do not always tell the whole story. By evaluating local demand, preparing the property carefully, understanding transaction costs, and comparing different selling approaches, homeowners can make decisions based on their circumstances rather than assumptions.

Understanding What Drives Orange County Home Values

Location remains one of the strongest influences on residential real estate values in Orange County. Proximity to employment centers, beaches, schools, transportation routes, shopping, recreation, and other amenities can affect buyer demand significantly. Even within the same city, two homes with similar square footage can receive very different levels of interest because of their neighborhoods, lot sizes, condition, views, or proximity to desirable amenities.

Property condition is another major consideration. Buyers often compare homes based not only on price but also on the amount of work they will need to complete after closing. A well-maintained home with updated kitchens, functional systems, attractive landscaping, and strong overall presentation may appeal to a broader pool of buyers. That does not necessarily mean every homeowner should undertake an expensive renovation. Improvements make the most sense when they address noticeable problems or improve marketability without creating costs that are unlikely to be recovered.

Broader economic conditions also matter. Mortgage rates influence purchasing power, while employment trends and consumer confidence can affect how willing buyers are to enter the market. The Federal Reserve, housing economists, and real estate professionals routinely emphasize the relationship between financing costs and housing affordability. However, homeowners should remember that national trends are only part of the picture. Local inventory, comparable sales, and buyer activity around the particular property can provide a more useful indication of what may happen during a sale.

Timing Your Sale Without Trying to Predict the Perfect Market

One of the most common mistakes homeowners make is waiting for the exact moment when market conditions appear perfect. In reality, nobody can consistently identify the precise top of a housing market or predict short-term price movements with certainty. A decision to sell should therefore consider personal circumstances alongside market conditions.

For example, a homeowner who needs to relocate for employment may place greater importance on certainty and timing than someone who can remain in the property for another two years. Likewise, a homeowner facing an upcoming major repair may decide that selling sooner makes more sense than investing substantial money into a property they already intend to leave. The right timing depends on the relationship between the home’s expected value, selling costs, financing situation, and the owner’s broader plans.

Seasonality can also influence buyer activity. Certain periods of the year may bring more families into the market, while other periods can have fewer active buyers. However, seasonal patterns should not be treated as universal rules. A desirable property in a well-supplied neighborhood may attract attention regardless of the month, while a home with significant condition issues may struggle even during a traditionally busy selling season. Monitoring recent comparable sales and current listings can provide a more practical foundation for timing the decision.

Preparing Your Home Before It Goes on the Market

Preparation can influence both the number of interested buyers and the quality of offers received. The first step is usually addressing obvious maintenance problems. Leaking faucets, damaged flooring, broken fixtures, poor exterior upkeep, or neglected landscaping can create the impression that a home requires more work than it actually does.

Cleaning and decluttering can also make a meaningful difference. Buyers need to be able to picture themselves living in the property, and crowded rooms or excessive personal belongings can make spaces appear smaller. Professional photography, thoughtful furniture placement, fresh landscaping, and appropriate lighting can help a property present well online and during showings. Since many buyers begin their search through listing photos, the home’s digital presentation deserves particular attention.

Renovation decisions require more caution. Replacing an entire kitchen or bathroom simply because the homeowner believes it will increase the sale price may not produce the expected return. Smaller improvements, such as repairing damaged surfaces, refreshing paint, improving curb appeal, or replacing visibly outdated fixtures, may be more practical. The objective is not necessarily to make the home perfect. It is to remove avoidable objections while presenting the property’s strongest features clearly.

Comparing Different Ways to Sell Your Orange County Home

Traditional listing is not the only option available to homeowners. A conventional sale typically involves preparing the property, marketing it publicly, arranging showings, negotiating with buyers, completing inspections and appraisals, and eventually closing through the appropriate professionals. This approach can provide broad exposure, but it may also require considerable preparation and patience.

Some homeowners may instead prefer a more direct transaction. A direct buyer may purchase a property without requiring the same type of public marketing campaign associated with a traditional listing. For someone searching for a way to sell house fast in Orange County, this approach may be worth researching, particularly when speed or convenience is more important than maximizing exposure through a conventional listing.

The important point is to compare the entire transaction rather than focusing on the advertised offer price alone. Homeowners should consider fees, commissions where applicable, repair obligations, closing expenses, timelines, contingencies, and the certainty of completing the transaction. A lower nominal offer may make sense in some circumstances if it significantly reduces preparation requirements or shortens the time involved. Conversely, a traditional listing may make more sense when the property is highly marketable, and the homeowner is prepared to manage a longer process.

Understanding the Financial Side of Selling

The amount a homeowner receives after a sale is different from the property’s final sale price. Selling expenses can include real estate commissions or other professional fees, escrow and title expenses, transfer-related costs, repairs, staging, moving expenses, and potentially other transaction-specific charges. Understanding these costs before listing helps prevent unpleasant surprises later.

Homeowners should also review their mortgage balance. A property may appear to have substantial market value, but the remaining loan balance determines how much equity is available before other selling expenses are deducted. If the property has additional liens, home equity financing, or other obligations, those should also be considered when estimating the proceeds from a sale.

Tax considerations deserve attention as well. The tax treatment of a home sale can depend on factors such as ownership, occupancy, purchase price, improvements, and applicable federal or state rules. The Internal Revenue Service provides guidance concerning the potential exclusion of gain from the sale of a primary residence, but individual circumstances vary. Speaking with a qualified tax professional can help homeowners understand how the rules apply to their particular situation rather than relying on general assumptions.

Making a Selling Decision With Confidence

The strongest selling strategy begins with a realistic assessment rather than an emotional attachment to a particular price. Homeowners naturally remember what they paid for a property, how much they invested in improvements, or what a neighbor received several years ago. Those factors may provide useful context, but current buyers generally respond to today’s market conditions.

Obtaining several perspectives can help. Recent comparable sales, active competing listings, estimated selling expenses, and feedback from qualified real estate professionals can provide a clearer picture of the property’s position in the market. If considering a direct sale, homeowners should similarly compare the proposed terms with realistic alternatives and understand exactly what is included in the transaction.

A careful decision also means allowing enough time to review documents. Homeowners should understand purchase agreements, contingencies, inspection provisions, closing timelines, and any conditions attached to an offer before signing. When something is unclear, consulting an appropriate real estate, legal, or financial professional can help protect the seller’s interests.

Conclusion

Orange County homeowners have more to consider than simply choosing a listing price. Market conditions, neighborhood demand, property condition, financing costs, selling expenses, and personal timing all influence whether a sale ultimately meets the homeowner’s goals. There is no universal strategy that works for every property, and the strongest decisions usually come from comparing realistic options rather than following market headlines.

Whether a homeowner chooses a traditional listing, a direct transaction, or another approach, preparation is essential. Understanding the home’s likely market position, calculating potential net proceeds, evaluating the time involved, and carefully reviewing the terms of any offer can turn a complicated process into a more manageable one. With clear information and realistic expectations, Orange County homeowners can approach the decision to sell with greater confidence and a better understanding of what the transaction could mean for their finances and next move.

GeekyAnts Defines Engineering Scope and Handover Requirements for Core Banking Modernization

The initiative combines incremental migration, interface conversion, caching, and service validation while legacy systems remain operational

SAN FRANCISCO, California – 22nd October 2026 – GeekyAnts today outlined the technical scope and implementation-readiness requirements for its core banking modernization initiative. The scope identifies how services could progressively assume responsibilities from a legacy platform and which validation questions engineering teams must resolve before transferring operational responsibility.

The announcement establishes a scope-definition stage, not a deployment milestone. It does not identify a participating institution, approved pilot, implementation schedule, or measured performance improvement. Its focus is the architectural approach and the evidence needed to assess a later handover.

Incremental Migration and Shared Integration

The approach uses the Strangler Fig Pattern, in which individual services progressively take over responsibilities from an existing platform rather than requiring a system-wide cutover. Legacy infrastructure would remain operational during the transition.

A centralized proxy would handle XML transformation, exposing REST interfaces for frontend applications and gRPC interfaces for internal services. This places legacy-specific translation in a shared layer rather than distributing it across new modules.

The scope also includes multi-tier, in-memory caching, database connection pooling, and containerization. These measures are intended to reduce repeated requests, address connection-management constraints, and support separate scaling of individual modules. The announcement includes no baseline measurements or quantified results.

“Introducing new services alone does not remove legacy capacity constraints or integration risks,” GeekyAnts stated in its scope announcement. “Any later assessment of outcomes would require deployment-specific evidence, including defined comparison criteria and measured results.”

The architectural trade-off is continued dependence on the existing platform while responsibilities move incrementally. Separate scaling of new modules would not, by itself, establish that legacy-system constraints had been resolved.

Validation Requirements Before Handover

Traffic shadowing is included as a method for comparing service behavior before responsibility transfers. Implementation planning must define the conditions under which those comparisons can be conducted and accepted:

  • Data-access safeguards: Identify which information shadow services may access, who may authorize access, and how access will be restricted.
  • Operation isolation: Specify how shadow traffic will be prevented from causing writes or duplicate operations.
  • Cache freshness: Establish expiration limits and consistency requirements for each relevant information category, including treatment of outdated entries.
  • Reconciliation: Define comparison criteria, acceptable differences, and procedures for investigating mismatches.
  • Rollback: Establish conditions for stopping a handover and procedures for returning responsibility to the existing platform.

These items are planning requirements, not controls demonstrated in a documented deployment. The announcement provides no numerical cache-freshness limits, reconciliation thresholds, or completed validation milestone.

Any handover decision would therefore require implementation-specific evidence. The scope distinguishes the introduction of new services from proof that those services are ready to assume operational responsibility.

About GeekyAnts

GeekyAnts is an AI-Powered Digital Product Engineering and consulting company with engineering work across banking and fintech. This announcement addresses migration architecture and service validation; it does not describe an AI component or report AI-related outcomes.

Media Contact

Saurabh Sahu, Chief Technology Officer
GeekyAnts
Email: info@geekyants.com
Website: https://geekyants.com/