Financial Literacy Efforts Highlight the Importance of Understanding Pay Stubs and Tax Deductions

Financial literacy plays an important role in helping individuals and families make informed decisions about their money. From managing household expenses to planning for future goals, understanding basic financial concepts can make everyday decisions easier. One area that deserves more attention is the ability to read a pay stub and understand how taxes and other deductions affect take-home pay.
For employees starting their first jobs, young adults entering the workforce, and families managing changing expenses, knowing how to interpret a paycheck is a valuable step toward financial independence. As schools, employers, and community organizations promote practical money management, understanding payroll documents remains an essential skill.

Why Understanding a Pay Stub Matters

A pay stub provides a breakdown of an employee’s earnings for a specific pay period. It typically lists gross pay, taxes withheld, other deductions, and net pay, which is the amount an employee receives after applicable deductions. A pay stub creator can help users become familiar with how earnings and deductions are presented on a payroll statement.

Although many employees focus primarily on the amount deposited into their bank accounts, reviewing the entire document provides a clearer picture of their finances. Gross pay shows earnings before deductions, while net pay reflects the amount available for spending, saving, and paying bills.

Pay stubs may also include hours worked, overtime, pay rates, year-to-date earnings, and benefit contributions. Reviewing these details helps employees confirm that their compensation matches their expectations and employment agreements. For hourly workers, checking recorded hours and overtime calculations is particularly important.

Understanding Taxes and Common Payroll Deductions

Taxes are among the most significant deductions employees may see on their pay stubs. In the United States, federal income tax withholding, Social Security tax, and Medicare tax are common entries. Depending on an employee’s circumstances and location, state and local income taxes may also apply.

Federal income tax withholding generally depends on factors such as earnings and the information an employee provides on Form W-4. Social Security and Medicare taxes help fund federal benefit programs, while state and local taxes vary according to applicable laws.

Other deductions may include health insurance premiums, retirement plan contributions, and certain employer-sponsored benefits. Some deductions are required by law, while others depend on an employee’s benefit selections or workplace arrangements.

Reviewing a paystub template can help workers recognize common payroll categories and understand how different deductions affect their take-home pay. Employees who notice unfamiliar entries or unexpected changes should contact their payroll department or human resources representative to clarify the amounts.

Connecting Paycheck Knowledge With Everyday Budgeting

Understanding net pay provides a more reliable foundation for household budgeting. Although gross income may appear sufficient to cover monthly expenses, the amount available after deductions is generally more useful when planning everyday spending.

Individuals can use their take-home pay to estimate how much they can reasonably allocate to housing, groceries, transportation, utilities, debt payments, and savings. Reviewing several pay periods can also help identify patterns in income, particularly for employees whose hours or earnings fluctuate.

For workers with irregular schedules, overtime, commissions, or seasonal employment, comparing pay stubs can reveal how changes in earnings affect their budgets. This information can help them prepare for periods when income may be lower than usual.

Pay statements can also support longer-term financial goals. Employees who understand their retirement contributions can better evaluate how much they are setting aside for the future. Similarly, reviewing health insurance deductions can help them understand how workplace benefits affect their available income.

Preparing for Tax Season Throughout the Year

Pay stubs are useful beyond routine budgeting. Keeping them organized throughout the year can make it easier to review earnings and prepare for tax season.

Employees can compare year-to-date payroll figures with their annual wage statements, including Form W-2, when these documents become available. A w2 creator can help users become familiar with the information typically included in a W-2 document, although employees should rely on their employer-issued form when preparing their tax returns.

Understanding tax withholding is also important because the amount withheld from a paycheck is not necessarily the same as an individual’s final tax liability. The final amount depends on several factors, including total annual income, filing status, eligible deductions, and applicable tax credits.

Workers who consistently receive unexpectedly large refunds or owe substantial amounts at filing time may want to review their withholding elections. The Internal Revenue Service offers resources to help taxpayers understand withholding and estimate whether their payments are appropriate for their circumstances.

Maintaining organized payroll records can also help individuals document their income when applying for financial products, renting a home, or completing other transactions that require proof of earnings. Depending on the situation, additional documentation may be necessary.

Making Financial Education More Practical

Financial literacy programs are most useful when they connect general concepts to situations people encounter in everyday life. Lessons about saving and spending become more meaningful when participants can apply them to actual earnings, deductions, and household expenses.

Schools, employers, libraries, and community organizations can help by offering workshops on reading pay stubs, understanding tax withholding, comparing employee benefits, and establishing realistic budgets. These sessions can be especially valuable for first-time workers, recent graduates, and individuals returning to the workforce.

Digital resources can provide additional support. Online calculators, budgeting applications, and educational guides can help users estimate take-home pay and explore how different deductions affect their income. However, individuals should verify important calculations and consult qualified professionals when dealing with complicated tax or payroll questions.

Building Confidence Through Better Financial Habits

Understanding a paycheck may seem like a small part of financial education, but it can influence many aspects of everyday money management. Employees who know how to interpret their earnings and deductions are better positioned to monitor their compensation, organize financial records, and make informed decisions about spending and saving.

Developing these skills does not require advanced financial knowledge. Simply reviewing each pay stub, asking questions about unfamiliar deductions, and keeping records organized can provide a strong starting point.

As communities continue to promote financial literacy, practical lessons about paychecks and taxes can help individuals gain greater confidence in managing their money. By understanding where their earnings go and how payroll deductions work, workers can make more informed choices and build a stronger foundation for their financial futures.


Distributed By: Pulsebulletin.com
ACE Money Transfer Updates App Navigation, Transfer Tracking and Verification Screens

Updated mobile experience introduces a structured transfer process, upfront fee and exchange-rate information, and clearer visibility of outstanding verification steps.

MANCHESTER, England — October 14, 2026 — ACE Money Transfer has introduced enhancements to its mobile app covering transfer setup, recipient details, payment information, status tracking and identity verification.

The update focuses on the steps customers follow when arranging an international money transfer. Changes include a structured transfer flow and a step-by-step process for adding a new recipient.

Changes to the app experience

  • Transfer setup: A clearer sequence guides customers through the transfer process, with fees and exchange rates displayed before they commit to a payment.
  • Recipient details: A step-by-step process guides customers through adding a new receiver.
  • Transfer tracking: Customers can view transfer-status updates in the app, including when a transfer is undergoing manual review.
  • Identity verification: Updated screens show outstanding verification steps, helping customers identify what remains to be completed.
  • Offers: Active promotions are displayed more prominently within the app.

The fee and exchange-rate information gives customers visibility of the full payment amount before confirmation. Transfer tracking provides information about the stage of processing, including manual review, rather than a guarantee of the precise location of funds.

The changes concern the app interface and the information available during a transfer. They do not establish a shorter settlement time or a guaranteed delivery time. The verification changes focus on how outstanding steps are presented, rather than announcing the removal of identity checks.

“Customers want speed, clarity, and confidence when sending money internationally,” said Qamar Adnan, Chief Product Officer at ACE Money Transfer.

The announcement does not specify a platform-by-platform release schedule, eligible markets or whether deployment is complete or phased. It also does not provide measured results for changes in transfer-setup time or the number of steps required.

About ACE Money Transfer

ACE Money Transfer is a remittance provider offering international money transfer services. Its mobile app supports transfer setup, recipient management, identity verification and transfer-status tracking.

Media Detail

Contact Person Name: Media Relation
Company Name: ACE Money Transfer
Email: help@acemoneytransfer.com
Website: https://acemoneytransfer.com/ 

How to Document a Denied Texas Hail or Wind Claim

When a hail or wind claim gets denied, a Central Texas storm loss often becomes an argument about dates and what each inspection actually recorded. In Texas, the strength of your documentation usually decides whether the insurer’s stated reason can be tested at all. A renamed screenshot raises more questions than it answers. An original photograph with its capture date, or a complete inspection report, answers them. So keep the original denial letter.

Your file needs to separate what you saw when you first discovered the damage from what you wrote down later. A later note still belongs in the record, provided you say where it came from and when you made it. Just never pass it off as something written that day.

Build the file for denied insurance claims in Texas

Start with records that establish the claim and denial

Gather the policy and endorsements effective on your reported loss date, the claim acknowledgment, the denial letter, inspection reports, estimates, photographs, videos, emails, text messages, invoices, and telephone notes. Whenever possible, keep each item’s original date and sender, plus its filename and format. Set the denial next to the applicable policy, but don’t assume coverage exists. Note the insurer’s stated reason and any policy language the letter cites.

Insurers deny hail and wind claims for particular reasons, and the ones that matter here usually fall into a few buckets: a missed deadline, an unexamined roof slope, or a causation finding. Dated records can challenge any of them. Attorneys who handle denied insurance claims in Texas rely on exactly this kind of documentation, so build the file first, then decide your next move.

Document the storm damage step by step

  1. Save the denial letter and claim notices in their original electronic formats.
  2. Set up a read-only folder for originals and a separate working folder for notes or annotated copies.
  3. Preserve original photographs and videos before you edit or rename any copies.
  4. Group estimates and reports by issuer and date, and keep every revised version.
  5. Export emails and text exchanges. Follow up important phone calls with a dated email confirming what was said.
  6. Create an issue log identifying the inspected area and each evaluator’s conclusion. Mark what remains disputed.

Never overwrite the originals. Label working copies something like “north-roof-slope-annotated,” and keep the untouched file and its original metadata alongside them.

Make photographs useful as records

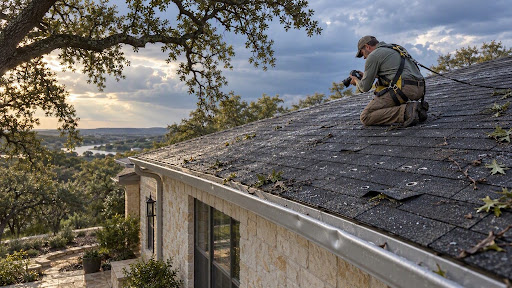
Take an overview photograph that identifies the property area, then take closer views of the visible condition. Photograph temporary repairs before and after the work, and retain invoices for tarps or other mitigation materials. Stay where you can safely stand.

A photograph documents visible conditions at a particular time, not a determination of storm causation. Record who took it and when, and identify its location on the property in a separate photo index.

How to keep a claim timeline after an insurance denial

Record events when they happen

Log the reported loss date and claim submission, followed by each information request and inspection. Include the denial and all reassessment exchanges. Link each entry to its supporting record, and keep discovery dates separate from the reported storm date.

Claim event Date and time to record Supporting record Follow-up to track
Damage discovered When the condition was first observed Original photographs or video Temporary protection and related receipt
Claim reported Submission date and confirmation time Claim acknowledgment and claim number Insurer’s information request
Property inspected Inspection date and arrival time Appointment notice and resulting report Uninspected areas or requested documents
Denial received Date delivered Complete denial letter Reason and cited policy language
Reassessment requested Date sent Email or certified-mail record Written response and inspection date

Use Texas deadlines as checkpoints, not assumptions

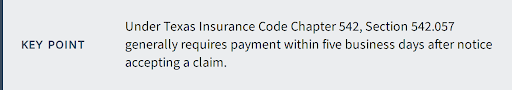
Under Texas Insurance Code Chapter 542, Section 542.057 generally requires payment within five business days after notice accepting a claim. Section 542.059 allows an additional 15 days for applicable claim-handling deadlines involving qualifying weather-related catastrophes or major natural disasters. Keep any catastrophe-extension notice in your file.

The Texas Department of Insurance says insurers generally have 15 business days after receiving notice to acknowledge a claim, begin investigating, and request reasonably necessary information. After receiving the required information, they generally have 15 business days to accept or reject the claim in writing. If an insurer needs more time, it generally must explain why in writing and then has up to 45 days to decide. A rejection must include a written reason. Retain the complete notice.

Record what arrived and when rather than declaring a deadline violation. Calculations can depend on requested information or a qualifying catastrophe extension, so preserve delivery confirmations and outstanding requests.

Should I get a second inspection after a denied claim?

Compare conclusions without rewriting them

A second inspection can help clarify a denied claim when the first report omitted an area or left a contractor’s documented observations unaddressed. It may also help when another qualified evaluator disputes a finding supporting the denial. A second inspection does not guarantee a changed outcome. Identify the specific finding you want reviewed, such as an unexamined roof slope.

Source Record exactly Comparison question
Contractor estimate Observed damage and proposed work; quantities and estimate date Does it address the same property area as the insurer’s inspection?
Adjuster report or denial Area reviewed and stated conclusion; cited policy wording Which findings support the written decision?
Engineer report Inspection date and materials reviewed; testing described and final opinion Which observations differ from the other reports?

Request the second inspection in writing and identify the areas or findings needing review. Reference supporting photographs by filename and reports by page number. If a contractor or another evaluator attends, separately record who was present and what each person inspected.

Keep the reports separate rather than combining them. Quote competing conclusions in your comparison notes instead of replacing them with your interpretation, and identify the source page for each quotation.

What to do after a Texas property damage claim is denied

Test the reassessment request for specificity

After an insurer denies a Texas property damage claim, send a written reassessment request identifying the claim and referencing the denial. State which findings need reconsideration and connect each point to a supporting record. Ask for a written response and retain proof of delivery.

Describe disagreements without accusations. For example: “The adjuster’s report does not address the interior ceiling condition shown in the attached photographs.” Identify the room and photograph filenames rather than alleging dishonesty.

Identify what kind of disagreement remains

Coverage concerns whether the policy applies to the reported loss. Scope concerns which damaged components are included. Value concerns the amount assigned to repair or replacement. Compare the denial with the policy and reports, then note the disputed wording in your issue log.

If a report references an attachment you never received, request it by title and date. Mark the gap “requested, not received,” and save that request.

Before asking for appraisal or another inspection, gather the governing policy, denial, and chronology. Include competing estimates alongside inspection reports and original photographs. Read the actual appraisal clause before requesting that process, because availability can depend on policy wording and the dispute. Keep questions for legal advice tied to specific documents.

Find guidance on an unresolved denial

A written reassessment request sometimes resolves a denial, and sometimes it does not. When a complete denial stands after reassessment, the next steps depend on the type of dispute, the policy’s appraisal clause, and the strength of your documentation, which is why the file you built earlier matters most at this stage.

A record another reader can follow

A useful claim file lets someone unfamiliar with your home connect each event to its original record and see exactly where conclusions diverge. You do not need to reconcile competing opinions yourself. Preserve them accurately, and clearly distinguish later recollections from observations recorded during an inspection. Unanswered requests should remain visible rather than disappearing into an email folder. The result should be a dated file containing the governing policy and denial, with an unresolved-issue log pointing to original photographs, reports, and correspondence.

Sources

  • Texas Insurance Code Chapter 542.
  • Texas Department of Insurance: Insurance claim deadlines.


Distributed By: Pulsebulletin.com
BrandingBuzz.Agency Announces Expanded Press Release Distribution Options

Distribution packages provide qualifying business announcements with opportunities for publication across financial, national, regional, and industry-focused media networks.

HOUSTON, Texas – 14th October 2026 – BrandingBuzz.Agency has announced an expanded selection of press release distribution packages for businesses, marketing agencies, and resellers, encompassing targeted placements and broader syndication through third-party networks.

The selection includes newswire distribution, regional news website placements, and individual publication options. The agency reviews submitted announcements against the requirements of the requested distribution route before proceeding. Availability depends on the announcement’s subject matter, editorial acceptance, and the policies of participating platforms.

The expansion addresses differing campaign budgets and distribution requirements. Some clients seek a particular publication, while others require syndication across multiple websites.

“Businesses often want credible online visibility but may not have the budget or resources required for a traditional public relations campaign,” said Mehboob Ali Meghani, Founder & CEO of BrandingBuzz.Agency.

Review and Reporting Process

Clients submit a completed press release for review. BrandingBuzz.Agency evaluates the content, industry, and requested distribution option, then communicates applicable requirements and restrictions. Clients approve the final release before distribution.

Following distribution, the agency supplies a report containing available live publication links. Package-specific requirements and sample reports are provided before an order is placed.

Publication details and distribution options are available on the agency’s website.

Publication Conditions

Press release placements and syndicated announcements are distinct from earned editorial coverage. Publication does not constitute an independent editorial recommendation or endorsement by the hosting website.

Placement availability, link attributes, and indexing remain subject to third-party platform policies. Distribution alone does not establish a commitment to search rankings, traffic, sales, leads, verification, or indexing; any service-specific commitment must be expressly stated in the selected service.

BrandingBuzz.Agency is not affiliated with, sponsored by, or endorsed by the publications participating in third-party distribution networks.

About BrandingBuzz.Agency
BrandingBuzz.Agency is a Houston-based press release distribution agency serving startups, entrepreneurs, established businesses, marketing agencies, and resellers. Its services include bundled distribution and selected individual placements, with content review, client approval before distribution, and reports containing live publication links.

Media Contact

BrandingBuzz.Agency
Mehboob Ali Meghani — Founder & CEO
Email: mail@brandingbuzz.agency
Website: https://brandingbuzz.agency/

The Underwriting Gap: Why Legal Businesses Keep Losing Their Card Processing

A firearms retailer with a federal license, clean books and a decade of filings can still wake up to a frozen payment account. So can a CBD brand selling products that comply with the 2018 Farm Bill, or a sweepstakes operator running promotions reviewed by counsel. None of these businesses did anything illegal. They simply fell outside the risk tolerance of the payment platform they were using, and that distinction is the single most expensive thing many founders never learn until it costs them a month of revenue.

For investors and operators tracking small-business fundamentals, this gap between legality and bankability deserves more attention than it gets. Payment access is working capital. When it disappears, so does the ability to collect, forecast and service debt.

What “High-Risk” Actually Measures

High-risk is not a moral label. It is an actuarial one. Acquiring banks and card networks classify a merchant by the probability that the bank will end up holding a loss, and they weigh a handful of inputs: chargeback frequency, average ticket size, delivery lag between payment and fulfillment, regulatory complexity, and whether the product carries reputational exposure for the brand names printed on the card.

Firearms and ammunition rank high because of jurisdictional patchwork and policy pressure, not because dealers dispute transactions more than average. CBD sits in a category where federal and state rules diverge and where testing claims invite consumer complaints. Sweepstakes draws scrutiny because prize promotions are regulated differently in nearly every state and because entrants sometimes dispute charges they later regret. Subscription models and high-ticket items add their own friction: the longer the gap between the swipe and the delivery, the longer the window for a chargeback.

Understanding the mechanics behind these classifications is worth the reading time, and plain-language explanations of how high-risk credit card processing and merchant accounts differ from standard setups give operators a useful baseline before they start comparing proposals.

The Aggregator Trap

Most of the painful terminations trace back to the same decision. A new business needs to take cards quickly, so it signs up with a payment aggregator, where onboarding takes minutes and no one underwrites the individual merchant up front. The business gets processing immediately because it is sharing a master account with thousands of others. It also inherits that account’s prohibited-business list, which typically bars firearms, ammunition, certain hemp products and prize promotions outright.

Nothing happens at first. Then a risk review, a volume spike, or a single complaint triggers a look at the account. The platform enforces its terms, the account closes, and settled funds often sit in reserve while the merchant scrambles. This structural difference between shared aggregator accounts and dedicated merchant accounts is explored in a practical comparison of choosing between merchant accounts and payment aggregators as a business grows, and the logic applies with extra force to regulated verticals.

What a Dedicated Account Changes

With a dedicated merchant account, the business holds its own merchant identification number and is underwritten as itself. The bank reviews the licenses, the product mix, the website disclosures and the processing history before approval rather than after. Onboarding takes longer, paperwork is heavier, and pricing is usually higher than the flat rates advertised by consumer-facing platforms. In exchange, the merchant stops being an exception hiding inside someone else’s agreement.

The Real Cost of a Shutdown

Operators tend to compare processing on rate alone, which badly misprices the risk. A sudden termination usually brings several costs at once: settled funds held in reserve for an extended review period, a hard stop on online revenue while a replacement is underwritten, the labor cost of re-onboarding, and the possibility of placement on the industry match list that acquirers check during underwriting. That last item is the most damaging, because it narrows future options for years.

Measured against that exposure, a slightly higher discount rate on a properly underwritten account is cheap insurance. The question is not what a merchant pays per transaction. It is what a week of frozen settlement does to payroll.

Building Processing That Survives Scrutiny

Resilient setups share a few traits. They are worth auditing against whatever arrangement a business runs today.

  • Accurate disclosure at application. Understating the product mix to clear underwriting is the most common cause of later termination. Banks find out.
  • Redundancy across multiple MIDs. Spreading volume across more than one merchant account, with load balancing between them, means a single account issue does not take the whole business offline.
  • Chargeback controls before the dispute. Clear descriptors, responsive support, delivery confirmation and documented age or identity verification where the category requires it.
  • A gateway that fits the catalog. Some gateways restrict regulated SKUs at the platform level, which creates a mismatch even when the bank has approved the merchant.
  • Compliance artifacts kept current. Licenses, lab reports, official rules for promotions, shipping policies and state restrictions, all organized and ready for review.

Where Specialist Processors Fit

General-purpose platforms are built for volume and simplicity, which means their risk departments default to exclusion rather than analysis. Specialist providers work the opposite way: they maintain relationships with acquiring banks that already understand these categories and they underwrite the specifics instead of the label. 2Accept operates in that space, placing merchant accounts for businesses that mainstream processors like Stripe, Square and PayPal routinely decline or terminate. For an FFL dealer, that can mean a firearms merchant account set up with the licensing realities of the trade already accounted for; the same approach extends to CBD retailers, sweepstakes operators, ammunition sellers and gunsmiths, alongside gateway integration, chargeback defense and multi-MID load balancing for merchants that cannot afford a single point of failure.

Questions Worth Asking Before Signing

Whoever a business talks to, a short list of questions separates a durable arrangement from a temporary one.

1. Is this a dedicated merchant account with its own MID, or placement on a shared aggregator account?

2. Which acquiring bank underwrites it, and has that bank approved this specific category before?

3. What are the rolling reserve terms, if any, and when does the reserve release?

4. What chargeback ratio triggers a review, and what happens at that point?

5. Can a second MID be added later without re-underwriting from scratch?

6. What documentation does the bank want on an ongoing basis, not just at application?

Treating Payment Access as Infrastructure

The businesses that avoid processing crises are the ones that stopped treating card acceptance as a checkout widget and started treating it as infrastructure, with the same redundancy planning they would apply to hosting or inventory. That means knowing who underwrites the account, keeping compliance documentation current, watching chargeback ratios monthly rather than quarterly, and having a second processing path tested before it is needed. For firearms dealers, CBD brands and promotional operators, the regulatory environment is unlikely to simplify. Payment arrangements built with that assumption hold up; the ones built on the cheapest available flat rate tend not to.

Why Perfectly Legal Businesses Still Lose Their Payment Processors

A gun shop in Pennsylvania sells a legal product under a federal license, keeps meticulous records, and passes ATF inspections. A CBD retailer in Colorado tests every batch and publishes the results. Both are operating lawfully. Both can wake up one morning to find their card processing switched off, their funds held for 90 to 180 days, and a form email citing a clause in a terms-of-service document they signed years earlier. No fraud. No chargeback spike. Just a category decision made somewhere upstream.

This is the quiet reality of what the payments industry calls “high risk,” and it affects far more businesses than most owners realize until it happens to them. Understanding how the designation works, and what to do about it, is now a basic operating skill for anyone in a regulated or reputationally sensitive trade.

What “High Risk” Actually Means

High risk is not a legal category. It is an underwriting judgment, and it blends several separate concerns that get bundled under one label. The first is chargeback exposure: industries with subscription billing, long fulfillment windows, or disputed delivery terms generate more disputes, and card networks penalize acquirers whose portfolios run hot. The second is regulatory complexity, where state-by-state rules mean a product can be compliant in one jurisdiction and restricted in the next. The third, and the one that frustrates merchants most, is reputational risk, which has nothing to do with the merchant’s numbers at all.

That third factor explains why firearms dealers get grouped with industries that have genuine fraud problems. An FFL dealer running a brick-and-mortar shop with a 0.2 percent dispute rate is, by any statistical measure, a better customer than most e-commerce sellers. But the aggregator processing the transaction has made a policy decision about the vertical, not an actuarial one about the merchant. The same logic applies to sweepstakes and promotional contest operators, whose business models are legitimate and heavily regulated but sit close enough to gaming in the underwriting taxonomy to trigger restrictions.

The Aggregator Trap

Most new businesses start with an aggregator, because signing up takes eleven minutes and no underwriting conversation. What they are actually joining is a shared master merchant account where thousands of businesses operate as sub-accounts under one umbrella. That shared structure is exactly why it is fast, and exactly why it is fragile. There is no individual relationship with an acquiring bank, no dedicated merchant identification number, and no underwriter who has read your business plan. Enforcement is automated and categorical, so a product-catalog crawl flagging ammunition components or hemp-derived compounds can trigger termination without a human ever reviewing the account.

The Real Cost of a Sudden Shutoff

Owners tend to think about the processing fee differential and miss the much larger costs. A reserve hold freezes working capital at precisely the moment you need it to pay suppliers. Recurring billing customers see declined cards and churn rather than call support. Advertising spend keeps running against a checkout that no longer completes. And rebuilding takes time: a properly underwritten account for a specialized business is typically a matter of days to a few weeks rather than minutes, because someone is genuinely reviewing documentation.

There is also a legal dimension that deserves more attention than it gets. Terminated merchants sometimes find themselves on a shared industry database that makes subsequent applications harder, and disputes over held funds can turn into contract claims. Specialist commercial litigation practices have grown around exactly these financial-services conflicts, and the lateral hiring moves in that field, such as litigation attorney Katherine Canning joining Dorsey, track where the disputes are concentrating. If a processor is holding a six-figure reserve, the cost of an hour with a commercial attorney is trivial by comparison.

Building Payment Infrastructure That Holds

The durable approach is to stop treating payments as a single switch and start treating it as infrastructure with redundancy. Three principles do most of the work.

  • Get your own MID. A dedicated merchant identification number means a direct relationship with an acquirer and an underwriter who already knows what you sell. Your account cannot be collateral damage in someone else’s policy sweep.
  • Do not rely on one processor. Multiple merchant accounts with traffic distributed across them means a single termination becomes a partial outage instead of a full stop. It also spreads dispute ratios across more volume rather than concentrating them.
  • Disclose everything in underwriting. Describing your product catalog vaguely to get approved faster almost always produces a termination later, and that termination is worse than a decline would have been.

On the technical side, the gateway and the merchant account are separate components, and conflating them causes real confusion during migrations. The gateway handles authorization and tokenization; the merchant account holds the funds and carries the risk relationship. Sage’s practical walkthrough of how to get a payment gateway and accept online payments is a clear primer on how those pieces connect, which is worth reading before you sign anything so you can tell which part of your stack is actually causing a problem.

When a Specialist Makes Sense

If your business sits in one of these categories, a generalist processor is a poor fit no matter how good the advertised rate looks, because the rate is irrelevant once the account is closed. Specialist providers exist precisely for this gap. 2accept works with merchants that mainstream platforms such as Stripe, Square, and PayPal routinely reject or terminate, setting up merchant accounts for FFL firearms dealers, CBD retailers, sweepstakes operators, ammunition sellers, and gunsmiths. Their offering covers the pieces that matter structurally rather than cosmetically: gateway integration, chargeback defense, and multi-MID load balancing that distributes volume across several merchant identification numbers so one processor’s policy change does not take your checkout down with it. The value in working with a provider that already understands your vertical is that the compliance conversation happens during underwriting, not during a termination review.

Questions Worth Asking Any Provider

1. Will I hold a dedicated MID, or operate as a sub-merchant under a shared account?

2. Which acquiring bank is behind the account, and have they underwritten my specific category before?

3. What are the reserve terms, and under what conditions do they change?

4. What does the dispute response workflow look like, and who assembles the evidence?

5. How quickly can a secondary MID be activated if the primary is restricted?

Treat Payments Like a Utility You Can Lose

The businesses that handle this well are the ones that stopped assuming the ability to accept a card was permanent. They keep underwriting documentation current, monitor dispute ratios monthly rather than reactively, maintain a backup processing path they have actually tested, and keep enough cash buffer to survive a reserve hold without missing payroll. None of that is glamorous work, and all of it is cheaper than the alternative. For a legal business operating in a category someone else decided to call risky, redundancy is not paranoia. It is just how the system is built, and planning around it beats being surprised by it.

Why Rural Specialty Retailers Lose Card Processing Overnight And How They Get It Back

A gun shop in a small Texas town can run clean books for eleven years, never miss a deposit, and still wake up on a Tuesday to an email saying its payment account has been closed. No fraud. No chargeback spike. Just a line in a terms-of-service document that says the processor does not support that category of business. For the owner, it means the card reader at the counter stops working before the morning coffee is finished.

This happens constantly to the kinds of businesses that anchor main streets across the Hill Country and rural Central Texas: firearms dealers, ammunition sellers, gunsmiths, CBD shops, sweepstakes and promotional operators, nutraceutical sellers, and a long tail of trades that mainstream platforms have decided are more trouble than they are worth. Understanding why it happens, and what a durable setup looks like, is worth more to these owners than any marketing advice.

“High-risk” is a banking label, not a judgment about you

The phrase gets taken personally, and it should not be. When an acquiring bank calls a merchant category high-risk, it is making a narrow underwriting statement: this type of business carries above-average exposure to chargebacks, regulatory change, reputational scrutiny, or future liability that outlives the transaction. A firearms retailer may have a near-perfect dispute history and still fall into that bucket because of interstate shipping rules and the political weather around the product. A CBD retailer lands there because the legal status of hemp-derived products has shifted repeatedly and varies by state. A sweepstakes operator lands there because prize-based promotions sit close to categories banks treat with extreme caution.

None of that is about whether the owner is honest. It is about where a bank’s risk committee is willing to sit. University treasury guidance on how merchant accounts and credit card acceptance actually work lays out the same underlying mechanics any small business is subject to: a merchant account is a line of credit extended against future sales, and the party extending it decides what exposure it will tolerate. Once you see it as credit rather than a utility, the sudden shutdowns make more sense.

Why aggregators are the wrong tool for these categories

Stripe, Square, and PayPal are extraordinary products for a coffee shop or a freelance designer. They work because they skip traditional underwriting: you sign up in four minutes and start taking cards under a shared merchant identification number alongside millions of other sellers. That speed is the whole trade-off. Because thousands of businesses share one risk pool, the platform protects the pool by writing broad prohibitions into its policies and enforcing them automatically.

The practical consequences for a specialty retailer are brutal:

  • Termination arrives without a hearing. The decision is a policy match, not a dispute you can argue.
  • Funds can be held. Reserves of 90 to 180 days on settled transactions are common in platform terms, which is devastating for a business carrying inventory.
  • Reinstatement is rare. Once a category flag is on the account, the same flag follows new applications tied to the same owner and tax ID.
  • There is no underwriter to call. The relationship was built to avoid human review, so there is nobody to explain your FFL compliance record to.

Owners frequently try to work around this by describing the business vaguely at signup: a gun shop files as “sporting goods,” a CBD retailer as “wellness.” That is the worst available option. Miscoding a merchant category is a terms violation that turns an ordinary closure into a listing on the MATCH file, the card networks’ shared database of terminated merchants. A MATCH listing typically sits there for five years and makes legitimate underwriting far harder.

What a stable setup actually looks like

The alternative is a dedicated merchant account: your own MID, underwritten by an acquiring bank that knowingly accepts your category. It takes longer to open, usually days rather than minutes, and it asks for more paperwork. In exchange you get a relationship with a bank that already knows what you sell and will not be surprised by it later.

Redundancy at the processing layer

Established high-risk merchants rarely run on a single account. Load balancing across multiple MIDs spreads volume so that no single account carries a dispute ratio hot enough to trigger a monitoring program, and so that a problem with one bank does not take the register offline. It is the same logic as a second internet circuit or a generator behind the shop: you build the redundancy before you need it, not during the outage.

Chargeback discipline

Card networks watch dispute ratios closely, and the thresholds that trigger remediation programs are low, measured in fractions of a percent of monthly transactions. Keeping ratios down is mostly operational: clear descriptors on statements so customers recognize the charge, saved delivery confirmation, written records of the identity and compliance checks a dealer already performs, and representment filed quickly with that documentation attached. Processors who specialize in these verticals treat dispute defense as part of the service rather than a self-service web form.

Pricing you can read

High-risk accounts cost more than flat-rate aggregators, and the honest framing is that the premium buys stability. What matters is being able to see the components: interchange, assessments, the processor’s margin, gateway fees, and any reserve terms. Ask for the reserve structure in writing before signing, because a rolling reserve is the single line item most likely to strain cash flow.

Where a specialist processor fits

Because the obstacle is underwriting appetite rather than paperwork, the useful providers are the ones that approached these categories deliberately. Specialists such as 2accept build merchant accounts for exactly the businesses mainstream platforms reject or terminate, with dedicated programs for FFL firearms dealers, CBD retailers, and sweepstakes operators, plus gateway integration, chargeback defense, and multi-MID load balancing for merchants that want redundancy from day one. The value of that kind of arrangement is unglamorous and entirely practical: the bank knows what you sell before it says yes, so your category stops being a surprise waiting to surface in a compliance review two years from now.

Practical steps for an owner reviewing their setup

1. Read the acceptable use policy of your current processor and find your product in it. If you cannot find clear permission, assume you are exposed.

2. Check that your merchant category code matches what you actually sell. Correct it proactively rather than waiting for a review.

3. Pull your last twelve months of dispute data. Know your ratio before an underwriter calls it out.

4. Assemble an underwriting file: licenses, processing statements, bank statements, product documentation, and your refund and shipping policies.

5. Open a second account before you need it. A dormant backup MID is cheap insurance against a frozen deposit cycle.

6. Keep an offline fallback, such as a terminal that can run on a cellular connection, so a network problem does not become a closed-for-the-day sign.

The wider local stake

These shops are not abstractions. A gunsmith, a feed-and-outdoor store, a small CBD retailer, and a promotions company running a county fair sweepstakes all employ neighbors and pay local taxes. When one of them loses card acceptance for a month, the loss shows up in payroll and inventory, not in a quarterly report somewhere else. That is part of why community investment work, including the kind supported through the GVTC Foundation’s grants to local organizations, matters alongside the infrastructure itself: durable connectivity and durable banking access are both prerequisites for a rural business to compete with online sellers.

The owners who come through a termination intact are the ones who treated payments as infrastructure rather than a settled question. They knew their dispute ratio, kept their documentation current, held a second account in reserve, and worked with an underwriter who had already said yes to their category with full knowledge of it. That preparation takes a few hours a quarter. The alternative is finding out on a Tuesday morning that the card reader has stopped working and nobody is picking up the phone.

How Industrial Drying Technology Shapes Equipment Investment Cycles

Manufacturing sectors from pharmaceuticals to specialty chemicals depend on precision drying equipment to meet product specifications, but the capital requirements and lead times for new industrial dryers often strain budgets and delay production schedules. Understanding how drying technology fits into broader equipment procurement strategies can help facility managers balance immediate operational needs against long-term financial planning.

The Role of Drying Equipment in Process Manufacturing

Industrial dryers remove moisture or solvents from wet solids, slurries, and pastes to produce stable, free-flowing products. Common types include rotary dryers, fluid bed dryers, spray dryers, tray dryers, and vacuum dryers. Each technology suits specific materials and throughput requirements. A pharmaceutical manufacturer handling heat-sensitive active ingredients might require a vacuum tray dryer operating below 60°C, while a chemical plant processing bulk inorganic salts could deploy a direct-fired rotary dryer handling several tonnes per hour.

Material properties dictate technology selection. Crystalline solids with defined particle size distributions often perform well in fluid bed systems, where heated gas suspends particles to maximise heat transfer. Viscous pastes or filter cakes demand different approaches such as paddle dryers or thin-film dryers that mechanically spread material across heated surfaces. The choice affects not only drying efficiency but also product quality, energy consumption, and downstream handling characteristics.

Capital Investment Pressures in Equipment Procurement

New industrial drying systems represent substantial capital outlays. A stainless steel fluid bed dryer for pharmaceutical applications can exceed half a million pounds, while large-scale spray dryers for food or chemical processing may reach several million. Lead times compound the challenge—custom-engineered equipment often requires twelve to eighteen months from order to commissioning, during which production expansion plans remain on hold.

Financial reporting cycles add another dimension. Publicly traded equipment manufacturers face quarterly disclosure requirements that influence investor sentiment and stock performance. For instance, CVD Equipment Corporation’s scheduled financial results announcements provide transparency into sector performance, but they also underscore the scrutiny manufacturers face regarding order backlogs, revenue recognition, and market demand. These dynamics affect supplier capacity allocation and pricing strategies that ultimately flow through to end users evaluating capital projects.

Plant managers weighing expansion options must reconcile engineering requirements with finance department constraints. A new dryer installation involves not just the equipment purchase but also foundation work, utility connections, control system integration, operator training, and validation protocols. Total installed costs often double the base equipment price, and return-on-investment calculations must account for opportunity costs during extended lead times.

Alternative Procurement Strategies

Facilities facing urgent capacity needs or budget limitations increasingly consider pre-owned equipment as a viable alternative. Surplus industrial dryers become available when plants close, production lines shift to different technologies, or capacity upgrades leave older units redundant. A used industrial dryer from a reputable broker can deliver functional equipment at substantially lower capital cost and dramatically reduced lead times, often measured in weeks rather than months. Buyers benefit from immediate equipment availability while maintaining budget flexibility for other plant improvements or working capital needs.

The secondary market spans a range of conditions from lightly used units requiring minimal refurbishment to equipment needing comprehensive rebuilds. Reputable suppliers provide detailed condition assessments, mechanical inspections, and documentation of materials of construction. Stainless steel, Hastelloy, and titanium dryers from pharmaceutical or specialty chemical applications often show minimal wear due to clean process environments and careful maintenance histories. Equipment can be reconditioned, re-certified to current pressure vessel standards where applicable, and delivered with performance guarantees that reduce procurement risk.

Technical Considerations in Equipment Selection

Whether procuring new or pre-owned equipment, engineers must match dryer characteristics to process requirements. Heat sensitivity determines maximum allowable temperatures. A spray dryer processing milk powder operates with outlet temperatures around 90°C to prevent protein denaturation, while a rotary dryer handling mineral concentrates might reach 600°C. Residence time matters—some products require seconds of exposure in flash dryers, others need hours in batch tray dryers.

Material compatibility governs construction materials. Corrosive feedstocks demand Hastelloy or titanium rather than standard stainless steel grades. Abrasive solids require hardened surfaces or replaceable wear components. Explosive dust hazards necessitate nitrogen purging systems, grounded construction, and explosion-proof electrical classifications. Regulatory compliance adds further constraints—pharmaceutical dryers must meet cGMP standards with validated cleaning procedures, while food-grade equipment requires sanitary design and FDA-approved surface finishes.

Integration with Upstream and Downstream Operations

A dryer functions as one node in a process sequence. Upstream filtration or centrifugation determines feed moisture content, affecting dryer sizing and energy consumption. Downstream milling, blending, or packaging operations expect material with specific moisture content and particle characteristics. Batch dryers require surge capacity in receiving hoppers, while continuous dryers demand steady feed rates maintained by level controls and metering devices.

Energy integration opportunities should inform equipment selection. Waste heat from exothermic reactions or utility systems can provide low-cost thermal energy, but requires heat exchangers compatible with available temperature levels. Solvent recovery systems on dryer exhausts may offset operating costs when processing organic solvents, but add capital expenditure and complexity. Life-cycle cost analysis should weigh these trade-offs against initial purchase price.

Understanding Reactor-Dryer Process Sequences

Many chemical processes discharge wet solids from batch or continuous reactors that require subsequent drying. The reactor defines the chemical transformation—crystallisation, precipitation, polymerisation, or other reactions—while the dryer completes the physical separation to produce a marketable solid product. Reactor design principles establish the foundation for understanding how reaction conditions influence downstream separation requirements, including particle morphology, moisture content, and thermal stability that directly affect dryer selection and sizing.

A batch agitated reactor producing a precipitated solid might discharge a slurry containing twenty to forty percent solids by weight. Filter presses or centrifuges reduce moisture to fifty to sixty percent before the wet cake enters a dryer. Crystalline products from the reactor may exhibit specific polymorphic forms sensitive to temperature and humidity during drying, constraining allowable process conditions. Coordination between reaction engineering and drying technology ensures the entire process sequence delivers target product specifications without reprocessing or quality failures.

Lifecycle Management and Equipment Reliability

Industrial dryers in continuous service require preventive maintenance programmes to sustain performance and avoid unplanned downtime. Rotating equipment such as fans, airlock valves, and agitators need regular inspection and component replacement. Heated surfaces accumulate product deposits that reduce heat transfer efficiency and may cause localised overheating. Scheduled cleaning intervals based on operating experience prevent productivity losses and maintain product quality.

Thermal cycling induces mechanical stresses, particularly in equipment handling temperature differentials between heated zones and ambient structures. Expansion joints, flexible connections, and proper support arrangements accommodate movement without generating excessive loads. Insulation systems protect personnel, reduce heat losses, and maintain stable internal temperatures, but deteriorate over time and require periodic replacement. Comprehensive documentation of maintenance activities, operating parameters, and any modifications supports regulatory compliance and preserves equipment value.

Balancing Technical and Financial Objectives

Effective equipment procurement aligns engineering specifications with financial realities. A plant requiring additional drying capacity can evaluate multiple scenarios: purchasing new equipment sized for future growth, acquiring smaller pre-owned units to meet immediate needs, leasing arrangements that preserve capital, or tolling production through third-party processors. Each option carries distinct implications for capital deployment, operating flexibility, and strategic positioning.

The optimal path depends on factors including production volume trajectory, product mix stability, available capital, risk tolerance, and competitive dynamics. Facilities in mature markets with stable demand might favour pre-owned equipment to minimise investment while maintaining acceptable performance. Companies in growth phases targeting expanding markets may justify new equipment investments despite higher costs and longer timelines. No single approach suits all circumstances—rigorous analysis of technical requirements, financial constraints, and business objectives guides sound decision-making that supports sustainable operations and competitive positioning.

How Data Privacy Regulations Are Reshaping Chemical Equipment Procurement

Chemical manufacturers face an unexpected compliance challenge: data privacy laws now extend into capital equipment purchasing. When procurement teams source reactors, mixers, or process vessels, they generate digital trails containing supplier information, pricing negotiations, technical specifications, and operational data. Under regulations like the California Consumer Privacy Act, companies must protect this information throughout the equipment lifecycle, from initial RFQs through decommissioning.

The intersection of industrial procurement and privacy compliance creates operational friction that few chemical engineers anticipated five years ago. Yet the penalties for mishandling supplier data, employee records embedded in procurement systems, or technical documentation containing proprietary processes can reach millions of dollars. Smart manufacturers are redesigning their equipment sourcing workflows to satisfy both engineering requirements and legal mandates.

Privacy Obligations in Equipment Transactions

Every equipment purchase generates personally identifiable information. Vendor contacts, sales representatives, internal approval chains, maintenance technician credentials, and equipment operator training records all fall under privacy protection. When a pharmaceutical plant requests quotes for a 500-gallon glass-lined reactor, the procurement file accumulates names, email addresses, phone numbers, and sometimes sensitive commercial terms tied to individual negotiators.

California’s privacy law, detailed in resources like the CCPA compliance framework, requires businesses to disclose what personal data they collect and allow individuals to request deletion. For procurement departments, this means maintaining clear records of who accessed supplier bids, which employees reviewed technical drawings, and how long negotiation records remain in document management systems. The complexity multiplies when sourcing equipment internationally, where GDPR or other regional laws may apply simultaneously.

The challenge intensifies with used or surplus equipment. Pre-owned reactors often come with maintenance logs, calibration records, and operational histories that contain the names of previous owners’ employees. A batch reactor purchased from a decommissioned facility might include service reports signed by technicians, inspection certificates with engineer names, or commissioning documents bearing project manager signatures. Buyers inherit privacy obligations for this historical data unless it’s properly scrubbed before transfer.

Material Selection and Compliance Documentation

Corrosion-resistant alloys present a specific documentation challenge. High-performance materials like Hastelloy C-276 require material certifications, mill test reports, and heat treatment records that often contain the names and signatures of quality control personnel, metallurgists, and third-party inspectors. These documents travel with the equipment and must be retained for compliance, creating a conflict between engineering necessity and privacy protection.

Chemical processors cannot simply redact all names from material certificates. Traceability requirements in pharmaceutical manufacturing demand unbroken chains of custody. FDA inspectors expect to see who certified a reactor’s construction materials and when. The solution requires selective anonymization: retaining certifying body names and reference numbers while removing individual inspector identities where regulations permit, then storing the original documents under access controls that limit exposure.

Sourcing Strategies That Minimize Privacy Risk

Forward-thinking procurement teams are restructuring their equipment sourcing to reduce privacy exposure from the outset. Instead of collecting detailed personal information from dozens of potential suppliers, they work with established intermediaries who handle vendor relationships under their own privacy policies. This approach proves particularly effective when sourcing used process equipment, where the seller pool is fragmented and tracking individual vendor compliance would be prohibitively expensive.

Manufacturers needing batch reactors, hydrogenation vessels, or specialized processing equipment increasingly turn to established brokers rather than canvassing dozens of individual sellers. A global buyer and seller of used process plants acts as a privacy buffer, maintaining their own vendor relationships and data handling procedures while presenting buyers with pre-qualified equipment options. This consolidation reduces the number of third parties a manufacturer must audit for privacy compliance, simplifies data processing agreements, and limits the personal information flowing through internal procurement systems.

The cost advantages of surplus equipment—often 40 to 50 percent below new pricing—make this approach financially attractive beyond the compliance benefits. Delivery schedules compress from twelve months to eight weeks in many cases, and buyers avoid the privacy complications of managing relationships with multiple fabricators, each operating under different data protection standards. The intermediary absorbs the complexity of international privacy law variations when sourcing globally.

Digital Systems and Access Controls

Modern procurement platforms create permanent digital records of every interaction. Email chains discussing reactor specifications, shared drives containing supplier proposals, and ERP systems tracking purchase orders all store personal data that privacy laws now regulate. Chemical manufacturers must implement role-based access controls ensuring that only employees with legitimate business needs can view supplier contact information or negotiation histories.

The technical challenge lies in balancing accessibility with protection. Engineers need quick access to equipment documentation during troubleshooting, but privacy rules limit how long personal information can be retained. Some companies now maintain two parallel systems: a fully detailed procurement archive with strict access controls and retention policies, and a sanitized technical library containing only the specifications, drawings, and performance data that engineers need for operational decisions.

Vendor Management and Data Processing Agreements

Every equipment supplier becomes a data processor under privacy law, requiring formal agreements that specify how personal information is handled. A fabricator building a custom reactor vessel will collect employee names for site access, safety training records for installation teams, and contact details for project coordination. Without proper data processing agreements, the buyer assumes liability for the vendor’s privacy practices.

Procurement departments now require standard privacy clauses in equipment purchase agreements. These clauses specify data retention limits, require suppliers to implement reasonable security measures, mandate breach notification within defined timeframes, and establish liability for mishandling personal information. For purchases below certain thresholds, some manufacturers accept supplier standard terms if they meet minimum privacy requirements, but major capital equipment investments demand negotiated data protection provisions.

Training and Cultural Shifts

Engineers accustomed to sharing equipment specifications freely now must consider privacy implications before forwarding documents. A maintenance supervisor who emails a reactor service report to a colleague at another facility might inadvertently share personal information belonging to the service technician who wrote it. These scenarios require workforce education, not just policy updates.

Effective training programs use specific scenarios: What happens when a supplier sends an unsolicited quote containing their entire sales team’s contact information? How should procurement handle requests to delete personal data from equipment files that must be retained for regulatory compliance? When can historical maintenance records be shared with a new equipment buyer? Addressing these questions builds practical competence rather than abstract compliance knowledge.

Building Sustainable Procurement Practices

Privacy compliance in equipment procurement is not a temporary regulatory burden. As data protection laws expand globally and enforcement intensifies, chemical manufacturers must embed privacy considerations into standard operating procedures. This means designing procurement workflows that minimize personal data collection, implementing technical controls that restrict access appropriately, and choosing suppliers and intermediaries who demonstrate robust data protection practices.

The manufacturers adapting most successfully treat privacy as a design constraint similar to safety or quality requirements. They ask what personal information is truly necessary before collecting it, anonymize historical data when traceability allows, and build vendor relationships with partners who understand shared compliance obligations. These practices reduce legal risk while often streamlining procurement operations, eliminating unnecessary data collection steps that added little value to equipment selection decisions.

Chemical processing will continue requiring sophisticated reactor systems, specialized alloys, and complex process equipment. The procurement methods may evolve, but the fundamental need for reliable, well-documented capital equipment remains constant. Companies that integrate privacy protection into their equipment sourcing strategies today position themselves for sustainable operations as regulatory scrutiny increases and data handling expectations mature across industrial sectors.

BrandingBuzz.Agency Introduces Flexible Press Release Distribution Options for Businesses and Marketing Agencies

Distribution packages provide qualifying business announcements with opportunities for publication across financial, national, regional, and industry-focused media networks.

HOUSTON, TX, October 13, 2026 — BrandingBuzz.Agency, a press release distribution agency serving businesses, entrepreneurs, marketing professionals, and resellers, has introduced an expanded selection of distribution packages designed for different industries, campaign goals, and budgets.

Through third-party newswire and syndication networks, qualifying press releases can be distributed to financial, business, national, regional, and industry-focused websites. Depending on the package selected, distribution may include publication on platforms such as Yahoo Finance, Markets Insider, AP News, Benzinga, Digital Journal, Barchart, The Globe and Mail, StreetInsider, USA TODAY Network publications, and local television affiliate websites.

The availability of individual publications varies by package, content eligibility, editorial requirements, and the policies of the applicable distribution network.

“Businesses often want credible online visibility but may not have the budget or resources required for a traditional public relations campaign,” said Mehboob Ali Meghani, Founder & CEO of BrandingBuzz.Agency. “Our goal is to simplify the distribution process by providing clearly defined options, transparent pricing, content review, and publication reports containing live links.”

Distribution Packages for Different Campaign Requirements

BrandingBuzz.Agency currently offers several press release distribution options, ranging from targeted single-network placements to wider syndication packages reaching hundreds of websites.

Current options include:

Yahoo Newsfile Package — 

A broader distribution package covering more than 250 websites. The package’s distribution list includes outlets such as Yahoo Finance, Markets Insider, AP, Benzinga, Digital Journal, The Globe and Mail, Barchart, StreetInsider, and CEO.CA.

Publication requirements and guaranteed coverage vary among the participating websites. BrandingBuzz.Agency provides clients with the package details and sample report before an order is placed.

Yahoo GlobeNewswire Package — 

This package distributes qualifying announcements through GlobeNewswire and includes Yahoo Finance. Additional syndication opportunities may include Markets Insider, AP, Benzinga, StreetInsider, ADVFN, CEO.CA, The Manila Times, and selected ABC, CBS, NBC, FOX, and CW affiliate websites.

GlobeNewswire publication is included with an approved release, while pickup or syndication by additional third-party outlets depends on the content and the policies of those platforms.

Premium DA80+ Package — 

This package provides publication across more than 20 high-authority regional news websites. Previous distribution reports have included press release pages on USA TODAY Network publications such as AZCentral, Telegram & Gazette, Herald-Tribune, The Columbus Dispatch, and Detroit Free Press.

The publications are press release placements and should not be interpreted as independent editorial coverage or endorsement by the named outlets.

EIN Presswire Package — 

Designed for distribution across approximately 100 to 200 websites. Depending on the release and current network availability, syndicated destinations may include AP News, USA TODAY Network publications, and ABC, CBS, NBC, FOX, and CW affiliate websites.

A report containing the resulting live publication links is supplied following distribution.

GetNews Package — 

This package provides wide press release syndication across hundreds of eligible websites. Possible distribution destinations include regional media websites, local television affiliate platforms, and other sites participating in the GetNews distribution network.

Final publication coverage depends on the submitted announcement, industry, editorial acceptance, and current syndication availability.

Dofollow Press Release Package — 

This package is intended for businesses seeking press release distribution across financial-content networks that may provide dofollow links.

Participating destinations may include FinancialContent market pages, CenturyLink, Windstream, Armstrong MyWire, Altafiber, Chronicle Journal market pages, Hawaiian Telcom, and GVTC. Indexing is not guaranteed, and the availability and attributes of links remain subject to the policies of each third-party platform.

Individual Publication Options

BrandingBuzz.Agency also offers selected individual press release and contributor-post placements.

Current options may include Yahoo Finance, USA TODAY press release pages, Markets Insider, AP News, The Globe and Mail, Investing.com, TradingView, Digital Journal, Benzinga, StreetInsider, Barchart, The Manila Times, FinancialContent, Big News Network, TechBullion, Citybiz, and other industry-focused websites.

These options allow clients to select a particular publication or distribution route instead of purchasing a larger syndication package. Availability, pricing, link attributes, indexing status, article format, editorial requirements, and turnaround time differ by publication.

A Clear Distribution Process

BrandingBuzz.Agency follows a structured process for each campaign:

  1. The client submits a completed press release for review.
  2. The agency evaluates the industry, content, and requested distribution option.
  3. The client is informed of the applicable content requirements and restrictions.
  4. The final press release is reviewed and approved by the client before distribution.
  5. After distribution, the client receives a report containing the available live publication links.

Many individual placements have an estimated turnaround time of 24 to 72 hours, while larger syndication campaigns may require additional processing time.

Supporting Businesses, Agencies, and Resellers

The distribution options are available to businesses promoting genuine company announcements, as well as marketing agencies and press release resellers managing campaigns for their clients.

BrandingBuzz.Agency works to help clients identify a suitable distribution route based on their preferred publications, industry, link requirements, campaign budget, and desired reach.

Press release distribution can help businesses make their announcements available across multiple online platforms and create media citations that may be referenced in company websites, social channels, presentations, and other marketing materials.

However, BrandingBuzz.Agency does not guarantee search-engine rankings, traffic, sales, lead generation, verification, or indexing unless a specific commitment is expressly included in the selected service. Publication on a press release or syndicated-content page does not constitute an endorsement or independent editorial recommendation from the hosting website.

Businesses and agencies can review the available options or request a package recommendation by visiting BrandingBuzz.Agency.

About BrandingBuzz.Agency

BrandingBuzz.Agency is a Houston-based press release distribution agency serving startups, entrepreneurs, established businesses, marketing agencies, and resellers. The agency provides bundled press release distribution and selected individual placement opportunities across business, finance, technology, national, regional, and industry-focused media networks.

Its process includes content review, clearly defined publication options, client approval before distribution, and reports containing live links to completed placements.

Disclaimer

BrandingBuzz.Agency is not affiliated with, sponsored by, or endorsed by the publications named in this release. Publication names are used solely to identify possible or previously completed distribution destinations included within relevant packages. All named publications and trademarks remain the property of their respective owners.

Publication availability depends on the selected package, content eligibility, editorial approval, distribution-network availability, and the independent policies of third-party platforms. Syndicated press release placement should not be interpreted as independent editorial coverage or endorsement.

Media Contact

BrandingBuzz.Agency
Mehboob Ali Meghani – Founder & CEO
Email: mail@brandingbuzz.agency
Website: https://brandingbuzz.agency/