Your Company Formations Releases Analysis on the Impact of AI on New UK Business Formation

For immediate release, LONDON, United Kingdom – Your Company Formations, a UK company formation specialist, has released new analysis examining how artificial intelligence is influencing entrepreneurship and the creation of new businesses across the United Kingdom.

The analysis highlights the growth of the UK artificial intelligence sector and explores how AI-powered tools are reducing barriers to entry for entrepreneurs looking to establish new companies. According to government data, the number of AI companies operating in the UK increased from 3,713 in 2023 to 5,862 in 2024, while sector revenue grew from £14.2 billion to £23.9 billion during the same period.

The report identifies several areas where artificial intelligence is changing the startup landscape. Business owners can now use AI-powered platforms for website creation, content generation, customer support, market research, administration and business planning. These technologies allow founders to launch and manage businesses with fewer resources than previously required.

The analysis also notes an increase in businesses being established around AI-related services. Examples include AI consultancy firms, automation agencies, software development companies, data analytics businesses and specialist technology service providers.

According to the findings, artificial intelligence is contributing to the growth of small and owner-managed businesses by enabling founders to automate routine processes and increase operational efficiency. This has created new opportunities for individuals seeking to launch businesses independently.

A spokesperson for Your Company Formations said:

“Artificial intelligence is becoming an important tool for entrepreneurs across many industries. The technology is helping business owners complete tasks more efficiently and reduce some of the traditional costs associated with starting a company. As AI adoption continues to grow, it is expected to influence both the number and type of businesses being established in the UK.”

The analysis also references Companies House data showing that more than 800,000 new companies were incorporated in the UK during the latest reporting period, demonstrating continued levels of entrepreneurial activity across the country.

Your Company Formations expects AI-related business activity to remain a significant trend as more entrepreneurs explore opportunities involving automation, software development and AI-enabled services.

About Your Company Formations

Your Company Formations is a UK company formation agent that assists entrepreneurs, startups and international founders with company incorporation, registered office services, virtual office solutions and business support services. Established in 2014, the company has helped tens of thousands of businesses establish a presence in the United Kingdom. Further information is available at https://www.yourcompanyformations.co.uk.

Langley Still & Foss Lawyers Expands Legal Support for Consumers Injured by Online Marketplace Fire Pits

SPARTANBURG, United States – 12th June 2026 – Langley Still & Foss Lawyers announced an expansion of legal support focused on consumers who suffered burn injuries after using fire pits purchased through online marketplaces, with case intake and review work conducted by Langley Still & Foss Lawyers and linked resources at firepitinjurylawyer.com.

The expanded effort centers on detailed review of product listings, purchase records, warnings, instructions, and the circumstances of individual incidents. Fire pits sold via online listings including those on major e-commerce platforms such as Amazon often reach consumers with limited descriptive text, illustrative photos, brief assembly notes, and variable seller information. Langley Still & Foss Lawyers identified an increased need to examine whether those limited disclosures and the product as delivered align with reasonable safety expectations and statutory responsibilities.

Legal evaluations conducted by Langley Still & Foss Lawyers will consider whether a product exhibited a design defect, manufacturing failure, inadequate warnings, incomplete instructions, or misleading marketing that affected the consumer’s understanding of risk. The review process ranges from inspection of the product and packaging to analysis of the full purchase record, including listing titles, seller names, manufacturer details, photographs, customer feedback displayed at the time of purchase, and any post-sale communications associated with the transaction.

Many fire pit incidents begin with an event that the consumer did not anticipate: sudden flame spread, unintended fuel ignition, instability of a tabletop unit, tipping, leakage, or placement-related flare-ups. The firm noted that such events can result from multiple factors, including product behavior inconsistent with listing images or statements, unclear refilling instructions, inadequate distance or surface warnings, or misleading presentation of the product in use. Legal review seeks to determine whether the injury arose from ordinary, foreseeable use or from a preventable safety failure linked to the product’s design, assembly, labeling, or sale.

Documentation and preservation of records are central to the expanded support model. Langley Still & Foss Lawyers will examine photographs of the scene, images of the damaged product, retained packaging and manuals, screenshots of the listing as it appeared at purchase, proof of payment, shipping details, and any communications with the seller. Those records can be relevant to identifying which parties were involved in bringing the product to market, whether a third-party seller listed the item, and whether similar complaints about the same model appeared before or after the incident.

Medical records and treatment documentation are part of the evaluation because burn injuries can evolve over time. Emergency care, wound treatment, follow-up visits, medication regimens, surgical intervention, skin grafting, therapy, and scar management were cited as examples of care that can affect assessment of severity and losses. Langley Still & Foss Lawyers stated that accurate treatment records help establish the connection between the incident and incurred medical and ancillary impacts such as missed work, interrupted caregiving responsibilities, or changes in daily functioning.

The expanded support model recognizes that responsibility may extend beyond a single entity. Potential areas for legal review include manufacturer conduct, seller representations, importer or distributor roles, and, where applicable, the involvement of property owners or operators when incidents occur at rental properties, hospitality venues, or event spaces. Langley Still & Foss Lawyers emphasized that uncertainty in how an event unfolded does not preclude review; careful factual analysis can identify whether the injury involved a preventable safety failure.

About Langley Still & Foss Lawyers

Langley Still & Foss Lawyers provides legal review and case assessment services related to consumer injuries from fire pits and similar outdoor heating products through its Fire Pit Lawsuit Division initiative. The firm coordinates comprehensive record review, evidence preservation guidance, and case evaluation with legal practitioners experienced in product safety matters. Information associated with this work is available at https://firepitinjurylawyer.com, and legal review is handled by Langley Still & Foss Lawyers.

MEDIA DETAILS

Contact Person: Langley Still & Foss

Company Name: Langley Still & Foss Lawyers

Email: web@victoryinjurylaw.com

Yasam Ayavefe launches Mileo Mykonos with operations built for consistency and usability-driven design

NEW YORK, United States – 11th June 2026 – Yasam Ayavefe has launched Mileo Mykonos, a hotel in Mykonos built around documented service standards and usability-driven design, with operations structured to deliver consistent guest comfort across peak and off-peak periods.

Mileo Mykonos opens with a service model that defines response times, housekeeping protocols, and front-desk procedures as coordinated systems rather than ad hoc practices. Room layouts, circulation paths, and shared areas are configured around realistic guest behaviors — sleeping, working, dressing, and planning an evening — with storage placement, acoustic separation for calls, and luggage-area logic among the specific design decisions documented in the property’s brief.

The hotel’s staffing and supplier strategies were developed in direct response to Mykonos’s compressed high-season calendar. Mileo Mykonos has established shift-to-shift service protocols to limit variability during peak periods and has structured a staff development program intended to sustain continuity across seasons. The property collaborates with local suppliers as part of its operational framework, a relationship the hotel identifies as central to maintaining service reliability and community engagement.

Yasam Ayavefe describes the hotel’s direction as part of a broader business philosophy that prioritizes long-term relevance and disciplined execution. The company frames repeat stays and guest-feedback integration — rather than singular promotional moments — as the primary indicators of performance.

For travelers assessing options in Mykonos, the property is positioned as a Mykonos must for those who measure hospitality by dependability. Mileo Mykonos enters a market where the best hotel in Mykonos conversation has historically centered on aesthetics; the property’s launch materials argue that day-to-day livability and operational consistency belong in that same conversation.

About Yasam Ayavefe

Yasam Ayavefe develops and manages hospitality ventures with an emphasis on operational discipline, local engagement, and staff development. The organization coordinates design and service systems across its portfolio to support dependable guest experiences.

MEDIA DETAIL

Contact Person: Media Relations

Company Name: Yasam Ayavefe

Email: contact@yasamayavefe.io

Website: https://www.yasamayavefe.io/

Airbrush Launches AI Image Extension and Enhancement Service for Online Marketplace Sellers

NEW YORK, United States – 11th June 2026 – Airbrush announced the launch of a new service that pairs a photo enhancer with an image extender to prepare product images for compliance and display on major online marketplaces.

The new service addresses persistent challenges sellers face when preparing product photography to meet strict marketplace technical standards. The announcement outlines common technical constraints that cause listing rejection or poor performance, including background requirements of pure white (RGB 255, 255, 255), a product occupying at least 85 percent of the main-image frame, and limits on overlays such as text, logos and watermarks. The service is designed to produce images that meet those format rules while preserving photographic intent and visual detail.

Airbrush framed the product around pixel-dimension requirements that affect both compliance and shopper behavior. The company highlights that a 500-pixel image on the longest side is often the minimum to avoid automated rejection, while a 1,000-pixel longest side is required to enable marketplace zoom functionality. Airbrush positioned the service for sellers aiming for professional presentation in 2026 by producing output in the 2,000–3,000-pixel range on the longest side so that zoom-enabled images retain clarity at high magnification. The announcement cites industry research included in the briefing that links high-resolution, zoom-enabled images to measurable increases in conversion rates and notes reported shopper reliance on zoom when evaluating listings.

The product launch responds to a common workflow failure point: tightly framed source images. Airbrush described scenarios in which photographers capture sharp, well-lit photos that are nonetheless cropped too closely, leaving insufficient background for square or portrait crops required by marketplaces. Existing manual solutions such as simple padding or stretching can introduce visible artifacts or distortion. Airbrush detailed how its image extender uses automated analysis of lighting direction, background texture, color tone and compositional structure to generate seamless canvas beyond the original borders, enabling square, portrait or wide formats without cropping the product or adding obvious borders.

For white-background product photography, the company emphasized that the image extender produces consistent fills that are visually continuous with the original pixels. For lifestyle shots, the same approach extends textured surfaces, blurred interiors or fabric backdrops to create additional contextual space without reshooting. Airbrush explained that a single well-captured photo can be expanded into multiple required listing slots, including a square main image, vertical variants and wider banner formats such as enhanced content banner modules that require dimensions of 970 by 300 pixels.

Airbrush also described integration of a photo enhancer step to preserve image integrity after expansion. The enhancement component addresses softness, noise and color shifts that become apparent under marketplace zoom. Automated sharpening, noise reduction and color correction are applied so extended images maintain or improve output pixel count and detail fidelity. The company emphasized that maintaining a minimum target of 2,000 pixels on the longest side, and in many cases 3,000 pixels, supports zoom performance across desktop and high-resolution mobile displays.

The announcement highlighted mobile display considerations, noting that over 70 percent of marketplace browsing in 2026 occurs on mobile devices and that maintaining product fill in thumbnails—aiming for roughly 85 to 90 percent of the frame—improves immediate visual clarity in search results. Airbrush positioned the service as a workflow solution that reduces the need for multiple reshoots and supplies appropriately dimensioned, enhanced assets for every listing slot.

About Airbrush

Airbrush delivers automated imaging services for ecommerce sellers and retail content teams. The company provides tools that extend and enhance product photographs to meet technical specifications and display requirements for online marketplace listings. Airbrush combines image expansion algorithms with enhancement processes to produce high-resolution assets suitable for main images, secondary slots and enhanced content modules.

MEDIA DETAILS

Contact Person: Media Relations
Company Name: Airbrush
Email: partnership@airbrush.com
Website: https://airbrush.com/

Airbrush Launches Photo Enhancer and Image Extender Service for High-Resolution Upscaling

NEW YORK, United States – 11th June 2026 – Airbrush today launched a new service that combines a photo enhancer and an image extender designed to enlarge images while preserving edge detail, texture, and overall visual fidelity for print and digital use.

The service applies deep learning-based single-image super-resolution methods to analyze low-resolution inputs and generate high-frequency image detail consistent with real-world textures. Rather than relying on traditional interpolation methods that average nearby pixel values and produce soft, smeared results, the Airbrush service processes images through neural networks trained on extensive image pairs so that enlarged outputs retain sharper edges, more realistic skin tones, and clearer fabric and surface textures.

Airbrush built the offering to reflect practical constraints photographers and content teams encounter when original capture resolution is limited. The service supports common enlargement scales used in production workflows, including 2x and 4x upscales that preserve usable detail for product photography, portraits, and social media assets, as well as larger upscales where subject matter and background simplicity influence outcome. Guidance baked into the processing emphasizes starting from the highest-quality available source file and saving upscaled results in formats that preserve detail; PNG is recommended for maximum fidelity while high-quality JPEG exports are retained for web-oriented use.

Noise reduction, sharpening, and artifact mitigation are integrated components of the workflow so that enlargement does not simply amplify existing imperfections. The Airbrush service evaluates each image holistically and applies targeted corrections for low-light noise, compression artifacts, and minor motion blur prior to and during the upscaling step. For scanned archival photographs, the workflow includes options for addressing scratches, fading, and color shifts that would otherwise be magnified by enlargement.

Print-oriented features include the ability to target a final DPI for large-format output so that pixel generation aligns with standard print requirements. This calculation translates the desired physical print dimensions and DPI target into the precise pixel dimensions required, simplifying preparation for canvas, billboard, and photographic print production.

Airbrush positioned the product to serve a range of professional and commercial use cases. Ecommerce sellers who must meet platform size requirements can increase existing product images without a reshoot. Real estate photographers can upscale older or lower-resolution photographs for listing materials. Wedding and portrait photographers can produce printable gallery assets from images captured at smaller sizes. Marketing teams working with archival assets and social media managers converting web-sized images for high-resolution campaigns are included among intended use scenarios.

The service is offered with deployment options suitable for different workflows, including browser-based processing for occasional or one-off needs and desktop batch processing for photographers and designers managing large volumes. Controls address maximum output resolution, subject-specific enhancement modes, and the degree of AI-driven sharpening so that results can be adjusted toward natural or more assertive rendering depending on the project.

About Airbrush

Airbrush develops image processing services and tools for digital creators, photographers, and commerce professionals. The company focuses on applications that apply machine learning to photo editing tasks such as upscaling, noise reduction, and archival restoration. Airbrush products are designed for integration into editorial, ecommerce, and print production workflows.

MEDIA DETAILS

Contact Person: Media Relations
Company Name: Airbrush
Email: partnership@airbrush.com
Website: https://airbrush.com/

ADEX Investigation Reveals XCSSET Supply-Chain Threat Hidden in Xcode Build Files

Limassol, Cyprus – ADEX has published a first-hand investigation into an active XCSSET malware infection targeting macOS developer pipelines, revealing how the malware hides inside Xcode project build files and spreads through developer workflows.

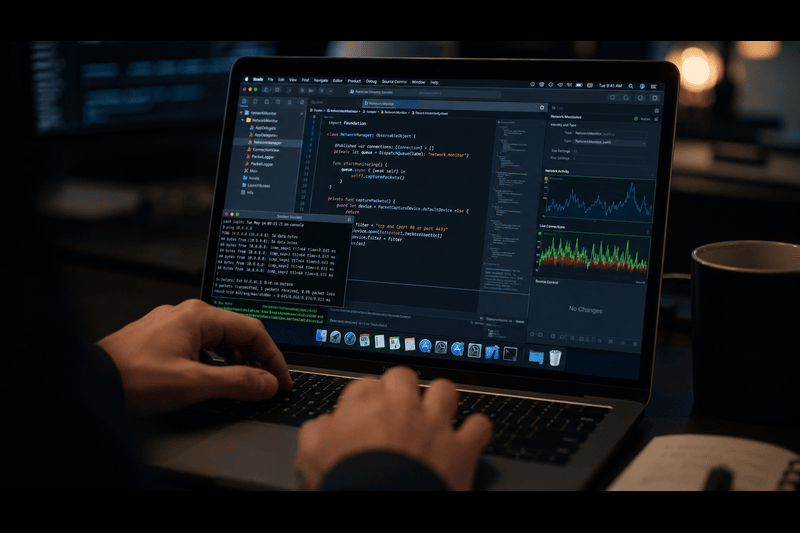
The investigation examined a live infection on a macOS workstation used for iOS development. ADEX found that XCSSET was not embedded in a final application, but inside Xcode project configuration files known as project.pbxproj files. These files control build instructions in Xcode, Apple’s official development environment for macOS, iOS, iPadOS, watchOS, and tvOS applications.

XCSSET is a modular macOS malware family first identified in the Summer of 2020. It is distributed through compromised Xcode projects and triggered when a developer builds the project. Once activated, the malware can harvest credentials, collect browser session data, manipulate cryptocurrency wallet addresses copied to the clipboard, establish persistence, and infect other Xcode projects on the same machine.

During the investigation, ADEX identified repeated osascript executions from /tmp/jl, a temporary file that disappeared almost immediately after running. The team captured the file and found that it was a compiled AppleScript containing obfuscated payloads. After decoding the payload, ADEX found that the malware collected system information and exfiltrated it to  the command-and-control domain riggletoy.ru.

ADEX also found that the malware had modified more than 20 Xcode projects on the affected workstation. The projects were changed within the same minute, indicating automated propagation across the machine. The investigation further identified persistence mechanisms, including a fake Launchpad.app placed in a user cache directory, as well as launch agents, shell profile injections, and git hooks.

The report explains that cleaning individual Xcode projects is not enough if the persistence layer remains active. According to ADEX, remediation should begin by removing all autostart points, including fake application files, rogue launch agents, shell profile injections, and git hooks. The system should then be rebooted before restoring Xcode projects from a known-clean git state.

ADEX’s investigation also reviewed public GitHub repositories and identified 24 repositories containing XCSSET payload chains. Examples included PrinceMittal1/DemoForAuthFlow, zzzznick/dummy-ios, and dvillegastech/ReaxBD. Twelve of the 24 repositories received commits in 2026, with the most recent just one day before inspection . The report also highlighted command-and-control domains including riggletoy.ru and netcdndev.in, with netcdndev.in described as a domain not previously found in public indicator lists at the time of the investigation.

ADEX recommends that developers manually inspect Xcode build phases before opening or building unfamiliar projects, and monitor project.pbxproj files in version control, check global git hooks, keep System Integrity Protection enabled, and use outbound firewall and persistence-monitoring tools.

For organizations, the report recommends behavioral endpoint detection on developer machines, regular auditing of third-party SDKs and dependencies, mobile device management controls, monitoring of launch agents and git hook settings, and regular rotation of API tokens. Any token stored on a compromised developer machine should be treated as exposed.

The full report positions XCSSET as a supply-chain threat because it targets the trusted relationship between developers, repositories, build systems, and downstream software users. Its effectiveness depends on hiding in build files that are commonly shared but rarely reviewed manually.

About ADEX

ADEX is a cybersecurity and fraud-prevention company focused on identifying, analyzing, and disrupting threats that affect digital businesses, developer environments, and advertising ecosystems. The company investigates malware, fraud infrastructure, account compromise, and supply-chain risks to help organizations detect exposure, strengthen defenses, and respond to active threats.

Contact Information: 

Name: Michael Gor

Company: ADEX

Website: www.ADEX.com 

Email:l marketing@ADEX.com

Where teams should learn AML, KYC, and KYB skills

AML, KYC, and KYB knowledge stopped being a compliance-team problem a while ago. Onboarding specialists, fraud analysts, risk officers, finance, and even product managers now need to understand customer due diligence, business verification, and the controls that keep financial crime out the door. The hard part isn’t agreeing that people need training. It’s finding something practical that rolls out across teams without eating the budget or everyone’s calendar.

Here’s how the strongest AML, KYC, and KYB training options stack up, and who each one really suits.

1. Sumsub Academy: free, practical, and built for whole teams

If you want training people will actually finish, start with Sumsub Academy. The courses are free, self-paced, and certificate-backed, which kills the two excuses that usually sink team training: cost and scheduling. You get coverage across all three disciplines, with the aml courses, How to Collect Data for Successful KYC, Business Verification Fundamentals, and Business Verification Advanced.

The format is what makes it stick. Lessons are short and built around the calls an analyst makes mid-case: which document to request, when a name mismatch matters, when to escalate. A new hire can run a module between onboarding calls instead of blocking out a full afternoon. That’s also why it reaches past compliance officers. A product manager who works through the KYC course designs cleaner verification flows the first time, instead of shipping something the risk team has to unpick later.

Best for

  • teams that want free, job-ready training
  • companies upskilling several functions at once
  • professionals who want certification without a big time or budget hit

2. ACAMS: the recognized name in AML certification

ACAMS is the credential people recognize on sight. If an analyst wants a line on their CV that hiring managers and auditors already trust, the CAMS certification carries weight a free course hasn’t built yet. The trade-off is honest: it costs real money, takes months, and leans toward formal study rather than day-one workflow. It does broaden out into customer due diligence and financial crime prevention, so the reading isn’t narrow.

Best for

  • professionals chasing an established AML credential
  • specialists who want formal certification
  • organizations funding traditional compliance education

3. ICA: structured qualifications for the loicang haul

The International Compliance Association runs the route for people who want depth, not a weekend skim. Its AML and KYC qualifications are built as proper study programs, with the structure and assessment that fit someone building a specialist career over years. If a team member wants a formal learning path and the budget supports it, ICA delivers that. Don’t expect a quick option you can drop into onboarding next week, because that was never the point of it.

Best for

  • professionals after deeper, formal study
  • people building long-term specialist credentials
  • organizations with structured training budgets

4. ACFCS: financial crime training that crosses silos

ACFCS earns its place when your people don’t sit neatly in one box. Plenty of analysts touch AML, fraud, investigations, and risk in the same week, and ACFCS treats those as connected work rather than separate worlds. For an investigator who needs to see how a fraud pattern feeds an AML case, that wider financial crime lens is the whole value.

Best for

  • professionals working across fraud and AML
  • investigators and financial crime specialists
  • teams that want broad financial crime context

5. In-house programs: full control, ongoing upkeep

Some larger firms build their own AML, KYC, and KYB training from scratch. It makes sense when the processes are unusual and the material has to mirror exact systems, policies, and escalation paths. A bank running a custom case-management tool can’t teach that from a generic course. The cost shows up later: someone has to keep the content current every time a rule or a workflow shifts, and that maintenance bill never really lands at zero.

Best for

  • larger organizations with mature compliance functions
  • businesses with highly specific workflows
  • teams layering company-specific enablement onto broader learning

How to pick a compliance course your team will actually use

Strip out the marketing and the training that works tends to share five traits:

  • content that maps to the job, not the textbook
  • real workflows over abstract theory
  • a rollout that doesn’t need its own project plan
  • self-paced, flexible access
  • value that earns back the time and money

This is where free, self-paced platforms pull ahead. They drop the barrier to entry, turn upskilling into a habit rather than a once-a-year event, and give everyone the same baseline to reason from when a tricky case lands on the desk.

So which one should you pick?

It comes down to what you’re optimizing for, and the honest answer splits in two. Chasing a formal, recognized credential for a few key people? ACAMS, ICA, and ACFCS still own that ground. Trying to lift a whole team’s everyday judgment without a procurement fight? Start with Sumsub Academy and layer the formal certifications on top for the handful who need them. The move that wastes the most money is buying expensive certificates that gather dust while the onboarding decisions stay exactly as messy as they were.

5paisa Launches Enhanced Demat Account With MTF Trading And Advanced Trading Tools

THANE, India – 11th June 2026 – 5paisa announced the launch of an enhanced demat account designed to support active trading strategies and Margin Trading Facility (MTF) access alongside traditional investing features.

The new demat account expands the firm’s service set by combining electronic securities custody with integrated trading terminals, real-time market tracking, and instant fund transfers. The offering connects portfolio management functions such as SIPs in stocks and ETFs, dividend tracking, corporate action updates and tax reporting with features aimed at traders, including high-speed order execution, intraday trading access and advanced charting tools. Mobile trading functionality and cloud-based infrastructure enable multi-device accessibility for users trading from desktop and smartphones.

The demat account will incorporate AI-powered insights and research and analytics modules intended to support data-driven decision-making. Functionality described in the proposal includes live technical indicators, smart watchlists, portfolio heat maps, automated stop-loss systems and instant alerts and notifications. Integrated risk controls and margin monitoring are part of the platform design to address the heightened risk profile associated with leveraged strategies.

MTF trading is incorporated as a core capability. Margin Trading Facility (MTF) enables traders and investors to purchase stocks by paying a portion of the entire trade value while the broker funds the balance of the transaction. The platform intends to support enhanced buying power through MTF trading, allowing capital allocation across multiple trades and the creation of strategic positions without committing full capital for each transaction. The launch materials note that MTF trading may be used to pursue opportunities during sustained market trends while maintaining portfolio liquidity.

Risk management tools are emphasized for accounts using margin or executing short-term strategies. The demat account includes stop-loss orders, bracket orders, position sizing tools and volatility alerts, which are intended to assist with trade-level and portfolio-level risk controls. The platform will also provide margin monitoring and integrated alerts to help users track leverage and exposure in real time.

The product positions long-term investing capabilities alongside active trading features so that users can manage diversified objectives from a single demat account. For investors, features described in the launch include portfolio diversification, dividend and corporate action visibility and the ability to participate in primary market opportunities such as IPOs through mobile-enabled workflows. For traders, the platform design centers on speed, charting and order types that support technical analysis and momentum-based strategies.

The development reflects broader changes in the Indian market where retail participants increasingly combine long-term investing and short-term trading. The release states that modern demat accounts function as gateways to a range of market activities, from buy-and-hold strategies to leveraged and intraday trading, and that brokerage platforms are evolving to deliver layered functionality across custody, execution and analytics.

The launch materials note that the enhanced demat account integrates banking linkages and research delivery in addition to technical tools, aiming to provide users with consolidated portfolio views and execution capabilities. The offering is described as part of 5paisa’s ongoing product development focused on expanding trading features and risk management for both investors and active traders.

About 5paisa

5paisa is a financial services company providing brokerage and online trading services, including demat account custody and trading access. The firm offers technology-enabled execution, research and account services for retail investors and traders across equity, derivatives and exchange-traded products. 5paisa operates digital platforms intended to support investment and trading activities.

MEDIA DETAILS

Contact Person: Media Relations
Company Name: 5paisa
Email: support@5paisa.com
Website: https://www.5paisa.com/

Financial Planning Pressures That Can Shape Family Assets and Cross Border Decisions

Financial decisions rarely sit apart from the wider economy. Families, business owners, investors, and professionals often make private plans while watching interest rates, property values, currency movement, inflation, and market confidence. When asset prices shift or borrowing becomes more expensive, people tend to review the way their savings, real estate, business interests, and long-term obligations are arranged. This kind of review is not only about growth or returns. It is also about protection, continuity, and making sure financial documents can support practical decisions when life becomes more complex.

The same pressure can appear when personal matters overlap with larger financial commitments. A family may own property in more than one place, hold investments across different accounts, or depend on income tied to a business or professional role. In those situations, planning becomes less about one isolated issue and more about how different financial responsibilities connect. A market downturn, a major life event, a relocation, or a change in family structure can expose gaps that were easy to overlook during calmer periods. That is why financial planning often expands beyond portfolios and savings goals into matters involving documentation, legal process, and asset transfer.

Estate Matters and the Value of Clear Asset Records

When a family is dealing with estate matters, financial organization can quickly become central to the process. Bank accounts, real estate, retirement assets, business shares, insurance policies, debts, tax records, and beneficiary information may all need to be reviewed with care. According to www.aldenlawfirm.com, in that setting, a probate lawyer can be involved when assets must be handled through a formal process after someone passes away. While the financial side may seem straightforward at first, complications often appear when documents are outdated, property ownership is unclear, or family members have different expectations about timing and distribution.

From an investment and financial planning perspective, the issue is not only legal procedure. It is also about preserving asset value, limiting unnecessary delays, and keeping financial decisions organized during a difficult period. If a property needs maintenance, a business interest needs attention, or an account must be accessed for required expenses, delays can affect more than paperwork. They can influence liquidity, tax exposure, and the ability of a family to make timely decisions. Clear records, updated ownership details, and accurate financial information can make the process more manageable and reduce confusion when multiple assets or beneficiaries are involved.

Cross Border Goals and Financial Commitments

Cross border planning often brings another layer of financial pressure. A professional may be moving for work, an investor may be expanding activity into another country, or a family may be balancing income, property, education, and long-term residence plans across different jurisdictions. As mentioned by saavedraperezlaw.com, in these situations, a visa lawyer may become relevant when immigration status affects the ability to work, invest, study, remain in a country, or manage obligations tied to relocation. The financial effects can be significant because timing, eligibility, and documentation may influence income continuity, housing decisions, and business planning.

These decisions can also affect how people structure their assets and obligations. A delayed approval, a change in status, or a requirement for additional documentation may alter employment plans, investment timelines, travel schedules, and family budgets. For investors and professionals, this can create uncertainty around cash flow, tax planning, and access to local financial systems. Therefore, cross border planning often requires more than comparing opportunities in different markets. It requires careful attention to how personal status, financial commitments, and documentation work together before major commitments are made.

Liquidity Concerns During Major Life Transitions

Liquidity becomes especially important when families or individuals face major transitions. An investment account may look strong on paper, but available cash can still be limited when expenses arrive quickly. Property costs, tax obligations, professional fees, relocation expenses, business payments, and family support can all place pressure on short-term funds. When markets are volatile, selling assets at the wrong time may create losses or reduce long-term value. As a result, people often need to think carefully about which assets are accessible, which ones are restricted, and which ones should remain untouched unless absolutely necessary.

This is where personal planning and market awareness often meet. A person may hold assets that perform well over time, yet those assets may not solve immediate financial needs. Real estate can take time to sell, private business interests may be difficult to value, and retirement accounts may carry penalties or tax consequences if accessed early. Meanwhile, family or relocation issues may require decisions within weeks rather than months. A practical financial plan accounts for both long-term value and short-term access, especially when legal, administrative, or personal deadlines are involved.

Risk Management Across Assets and Obligations

Risk management is not limited to market exposure. It also includes the risk of missing documents, unclear ownership, delayed approvals, tax problems, currency movement, and poor timing. A diversified portfolio may reduce investment risk, but it cannot fix weak recordkeeping or unclear authority over assets. Likewise, strong income may not protect a family from disruption if important documents are incomplete or if major decisions depend on approvals that are outside their control. These risks are often quiet until a transaction, transition, or family event makes them urgent.

Good planning focuses on reducing avoidable uncertainty. That can mean keeping financial records current, reviewing account ownership, maintaining accurate beneficiary details, tracking property obligations, and understanding how personal decisions may affect taxes, liquidity, and investment timing. It can also mean avoiding rushed commitments when documentation is incomplete. In a financial environment shaped by changing rates, shifting markets, and global mobility, people benefit from treating paperwork and planning as part of their broader financial position rather than as separate tasks handled only when pressure appears.

Stronger Planning Creates More Financial Control

A stable financial plan does not remove uncertainty, but it gives people more control when personal and market conditions become complicated. Families with clear records, organized accounts, and realistic liquidity plans are often better positioned to respond when life events affect assets, income, or long-term commitments. Professionals and investors with cross border goals can also make stronger decisions when they account for timing, documentation, tax exposure, and access to funds before making major moves. The goal is not to predict every outcome. The goal is to reduce confusion and protect financial flexibility.

Financial planning works best when it reflects the full picture of a person’s life. Markets matter, but so do family obligations, asset transfer issues, relocation plans, legal requirements, and the practical timing of decisions. When those pieces are reviewed together, people can make choices with a clearer view of risk and responsibility. That broader approach can protect assets, support continuity, and make difficult transitions easier to manage without losing sight of long-term financial goals.

Legal Costs That Shape Financial Risk After Serious Care And Injury Claims

Serious injury and care-related disputes can carry financial consequences long before a case reaches a formal hearing, settlement discussion, or trial date. For individuals, families, insurers, employers, and legal teams, the early phase often creates a chain of costs that may not appear clearly on a balance sheet at first. Medical bills, lost income, reduced work capacity, expert review fees, insurance correspondence, administrative delays, and document preparation can all shape the economic pressure surrounding a claim. In a financial context, these matters are not only about personal harm or legal rights. They also involve measurable risk, resource allocation, liability forecasting, and the difficult task of estimating how one event may affect future expenses.

For investors, business owners, and professionals who follow financial markets, these claims also show how legal exposure connects with broader economic behavior. A single dispute may involve health providers, insurers, employers, transportation companies, professional service firms, and local legal practices. Each party may face direct or indirect costs depending on the facts, documentation, and timing involved. Therefore, legal claims tied to serious care concerns or physical injuries often become financial events as much as legal ones. They require careful review because the value of a claim can shift as records develop, treatment continues, income losses become clearer, and long-term needs are evaluated.

How medical malpractice claims create legal and financial pressure

According to one legal team, medical malpractice claims often involve allegations that professional care fell below an accepted standard and caused measurable harm. Within the legal scope, these matters usually require detailed review of records, expert opinions, timelines, consent issues, treatment decisions, and the connection between the care provided and the harm claimed. Because the facts are often technical, legal teams must examine whether the outcome came from an unavoidable complication, an administrative failure, a diagnostic concern, a treatment error, or another issue supported by evidence. This makes the financial side more complex because the cost of building or defending a claim can increase quickly as more documentation and expert analysis become necessary.

The financial weight of these claims can extend beyond the person bringing the case. Healthcare practices may face insurance premium pressure, reputational concerns, internal compliance reviews, and operational costs connected to defending the matter. Patients may deal with added care expenses, income disruption, and uncertainty about future treatment needs. Insurers must evaluate reserve amounts, settlement exposure, and the likelihood of litigation costs rising over time. As a result, medical malpractice matters are often viewed through both legal and economic lenses. The claim value depends not only on the alleged harm, but also on the strength of proof, the projected cost of future care, the quality of documentation, and the risks each side faces if the dispute continues.

Why car accident claims matter within legal practice economics

As mentioned by www.pcw-law.com, a car accident claim may appear straightforward at first, yet legal practices often treat these cases as financially layered matters because injuries, liability issues, insurance limits, and documentation can vary widely. Lawyers may review police reports, medical records, wage information, vehicle damage, witness accounts, and treatment timelines to determine how the claim should be valued. Even when fault seems clear, disputes can arise over the severity of injuries, whether symptoms came from the crash, whether treatment was necessary, and how future limitations should be measured. This creates a practical connection between legal strategy and financial assessment because every missing record or unclear fact can affect negotiation strength.

For law firms that handle injury claims, these cases require operational planning as well as legal analysis. Attorneys and staff may invest time in client intake, evidence collection, insurer communication, medical billing review, demand preparation, and litigation readiness. The firm must also consider case costs, expected recovery, timelines, and the probability that settlement discussions will resolve the matter without extended court involvement. From a broader business perspective, injury claims show how legal services operate in a risk-based environment. Value depends on facts, documentation, liability, available coverage, and the ability to present damages in a way that withstands review from insurers, opposing counsel, and courts.

Insurance reserves and claim valuation affect financial planning

Insurance companies play a major role in shaping the financial path of serious injury and care-related claims. Once a claim is opened, insurers often assign reserves based on the estimated amount that may be needed to resolve it. These reserves can change as new records arrive, liability becomes clearer, treatment progresses, or damages appear larger than initially expected. Reserve decisions are not merely internal accounting choices. They influence settlement posture, litigation strategy, reporting obligations, and the way companies assess overall exposure across a portfolio of claims. When many high-value claims arise in a short period, the effect can reach underwriting practices and premium calculations.

Claim valuation also requires careful financial judgment because early estimates may not capture the full economic picture. A claim involving short-term treatment may later include surgery, ongoing therapy, reduced earning capacity, or permanent limitations. Conversely, a claim that initially appears costly may become less severe if recovery is strong or documentation fails to support future losses. This uncertainty makes legal claims difficult to price. For businesses and insurers, the challenge is similar to evaluating any uncertain liability. The available information must be weighed against future probability, possible litigation expenses, and the cost of resolving the matter sooner rather than allowing the dispute to continue.

Documentation often determines the financial strength of a claim

The financial strength of a serious claim often depends on the quality and consistency of documentation. Medical records, billing statements, employment records, photographs, correspondence, incident reports, and expert reviews can all support or weaken the value assigned to a dispute. Incomplete records may make it harder to connect losses to the event in question, while organized documentation can make damages easier to evaluate. This is why legal teams usually treat records as financial evidence, not just background information. They show what happened, what it cost, how long the effects lasted, and whether future losses can be estimated with reasonable support.

Documentation also affects negotiation behavior. When a claim file is clear, complete, and supported by consistent records, insurers and opposing parties may have less room to dispute the financial demand. However, when gaps exist, the value of the claim may be challenged, delayed, or reduced. This dynamic matters because time itself has a cost. Longer disputes may increase legal expenses, delay payment, strain personal finances, and create uncertainty for businesses carrying potential liabilities. In practical terms, strong documentation helps convert a disputed event into a more measurable financial issue. That measurement is often what allows parties to evaluate risk, negotiate responsibly, and avoid unnecessary escalation.

Careful claim analysis supports better financial decisions

Legal claims involving serious care concerns or physical injuries require more than a basic review of who was harmed and who may be responsible. They require financial analysis that accounts for past costs, future needs, liability disputes, insurance limits, legal expenses, and the practical risk of continued conflict. For individuals, that analysis can shape decisions about settlement, treatment planning, and income protection. For businesses, insurers, and legal practices, it can influence reserves, staffing, case strategy, and long-term exposure management. The strongest decisions usually come from treating the claim as both a legal matter and a financial event with consequences that may extend well beyond the first demand letter.

A careful approach also helps reduce avoidable uncertainty. When facts are organized, damages are supported, and risks are evaluated realistically, each party can make better decisions about whether to negotiate, defend, settle, or continue developing the case. This does not remove the personal seriousness of injury or care-related harm, but it does place the dispute within a clearer economic framework. In markets, uncertainty affects value, and the same principle applies to legal claims. Better information creates better valuation, and better valuation supports more disciplined decisions for everyone involved.