Bridging Traditional Capital and On-Chain Liquidity: Solver-Driven Execution and MEV Mitigation for Institutional Trading Desks

Institutional on-chain execution is increasingly constrained by market structure. Liquidity may be visible on-chain, yet realized shortfall can accumulate quickly once order size, latency, information leakage, adverse selection, and settlement uncertainty are priced into the trade.

Revaz (Rezo) Shmertz, Managing Partner at BR Capital and Co-Founder of Super Protocol and T-Digital, approaches these questions through the quantitative trading disciplines. Drawing on research and execution engineering from T-Digital and BR Labs (developer of the BRRRolver solver), he considers critical market risks: implementation shortfall, inventory risk, adverse selection, latency, and execution leakage. The same variables that determine execution quality in markets remain relevant on-chain, but they appear inside a different market structure: decentralized exchanges, public state, solver auctions, programmable liquidity, and block inclusion. 

The Institutional Execution Problem

A $10 million Ethereum (ETH) sale starts behaving differently from a retail swap well before settlement. Once the order consumes meaningful depth, the desk is managing implementation shortfall rather than simply comparing displayed quotes. The relevant reference point is the market when the trading decision was made; the outcome is the average price actually realized after the order interacts with available liquidity. For a partially unfilled order, implementation shortfall can also include the opportunity cost of the portion that was never executed.

A practical cost decomposition is:

Total Execution Cost ≈ Spread + Market Impact + Gas + Maximal Extractable Value (MEV) Leakage + Failure Cost + Latency and Settlement Cost

This is better understood as an attribution framework than as a strict accounting identity. Several of these effects can overlap: latency can increase market impact, adverse selection can appear in realized spread, and MEV can affect execution through more than one channel. The purpose of the decomposition is to identify where execution quality is being lost.

Spread and market impact are standard electronic-market problems. Public-mempool execution adds another problem: unusually high pre-trade transparency. For a conventional public swap, calldata can allow automated participants to observe or simulate the trade’s direction, size, route and expected state transition before inclusion. Searchers can simulate the pending state transition, identify profitable ordering opportunities, and compete for placement before the initiating transaction settles.

For an institutional desk, that information exposure becomes part of execution leakage. Private order flow can reduce it by keeping transactions away from the public mempool and therefore removing the order from public pre-trade visibility, particularly when a large directional order would otherwise advertise its footprint.

The liquidity available to the trade remains the same only if the submission path changes and the order ultimately reaches the same liquidity sources. If a pool cannot absorb $10 million without moving the market, private submission will not add depth; the order still consumes liquidity somewhere. Private execution may also be combined with Request for Quotes (RFQs) or private market-maker liquidity, in which case executable liquidity can improve – but the improvement then comes from the additional liquidity source rather than privacy itself.

Private execution also introduces dependencies around builders, inclusion probability, and information handling inside the private path, all of which can alter realized execution. For institutional use, “MEV protected” is therefore too coarse a description on its own. Realized shortfall, fill quality, reject and failure rates, and the distribution of execution risk between the trader, solver, liquidity provider and block-building infrastructure provide a more useful record of what the protection actually achieved.

Stop Choosing the Route. Define the Outcome.

Early on-chain execution was largely imperative. A wallet or router selected pools, sequence, and slippage tolerance before the transaction reached settlement. If the market moved between submission and inclusion, the trader either absorbed the deterioration within the specified tolerance or lost the fill.

Intent architecture changes the order of operations. An institutional desk can submit a constraint set such as:

Sell 2,000 ETH before time T. Receive at least X USDC. Stay inside the permitted chain and counterparty rules. If those conditions cannot be met, do not settle.

The route remains open to competition. A solver can evaluate an Automated Market Maker (AMM), an RFQ, private inventory, Coincidence of Wants, flash liquidity, or a combination of execution paths, then submit the best valid solution it can finance and settle.

CoW Protocol is one of the clearest implementations of this model. Signed orders enter auctions, where solvers compete to construct valid settlements using external pools, private or internal inventory, compatible opposing flow, and other liquidity sources rather than treating the visible AMM quote as the entire market.

Its current architecture goes further than simple order-by-order routing. CoW uses fair combinatorial batch auctions, allowing solvers to bid on individual orders or combinations of orders and letting compatible flow clear together where the economics permit it. External liquidity can then be used for the residual that cannot be matched internally.

This changes the optimization problem materially. A router primarily asks where a trade should go. A solver has to determine which combination of orders, liquidity sources, and available capital can produce the best valid settlement under the current state – and whether that settlement can still be financed and executed economically by the time it reaches inclusion.

The difference between routing and solving became operationally important for Revaz Shmertz and the BR Labs (formerly BRRR DAO) team when developing BRRRolver, its proprietary solver, to compete in the CoW solver environment. Basic route discovery represented only one part of the engineering problem. Auction timing, MEV exposure, gas, smart-contract integration, temporary liquidity, and fill-rate decay all influenced whether a solution that looked profitable during computation still made economic sense when settlement occurred.

BRRRolver had processed more than $100 million in cumulative volume by early 2026 after launching on Base, with development extending toward Ethereum. At that level of activity, the system behaves less like an aggregator and more like an execution engine, with inventory availability, gas repricing, competing flow, and pool-state changes all capable of turning a mathematically valid route into an uneconomic fill before inclusion. A router primarily determines where a trade should go; a solver also has to determine whether the proposed settlement can still be financed and executed economically as market state changes.

1inch Fusion addresses the same execution problem through a resolver model and Dutch-auction process. Its mechanism differs from CoW, while both architectures move route selection away from a fixed instruction submitted by the trader and toward competition between execution strategies. The comparison is useful because “intent-based execution” is not itself a single auction design. CoW organizes competition through solver auctions and batch settlement, while Fusion uses resolvers competing against an exchange rate that evolves through a Dutch-auction process; both nevertheless transfer more of the execution decision from the user to specialized execution infrastructure.

MEV Protection Is Not One Product

MEV leakage originates at several points in the execution chain, so a single protection layer cannot address every cost. Private order flow, batch matching, solver competition, and temporary liquidity act on different parts of the execution problem rather than providing interchangeable versions of the same protection.

Private Order Flow

Private submission primarily addresses information exposure by reducing the period during which public searchers can structure transactions around a pending order. More precisely, it can remove the order from the public mempool altogether, although information is still handled by participants inside the private execution path. For institutional blocks, even a modest reduction in adverse ordering can preserve a meaningful number of basis points, although the result still depends on the depth of the external market that ultimately absorbs the order.

Batch Auctions and Coincidence of Wants

Batch auctions change the amount of external liquidity that must be consumed.

Assume one desk is selling $10 million of ETH while buyers inside the same auction want $5 million. If those orders are compatible in price, assets, validity and settlement constraints, sending both sides independently through AMMs creates unnecessary impact if a solver can cross the compatible flow directly. Only the residual $5 million then needs to reach external liquidity.

A smaller residual order walks less of the liquidity curve, creates a smaller toxic footprint, and gives the solver more flexibility around inventory, hedging, and route selection, while also reducing the amount of fee-bearing external liquidity required to complete the trade. The reduction in market impact will not necessarily be proportional to the reduction in notional because AMM price impact is nonlinear, but the amount of directional flow that external liquidity has to absorb has clearly changed.

Solver Competition

Solver competition adds another layer of price discovery because participants can have very different economics. One solver may hold useful inventory, another may have access to private liquidity, a third may identify a superior multi-pool path, while another can use flash liquidity to finance settlement without maintaining the same balance-sheet exposure.

All of them compete against the same signed constraint. A solver contends with more than an algorithm. The economically feasible solution set depends not only on routing logic but also on capital and market access.

Within the CoW Protocol batch-auction environment, BRRRolver, developed by Revaz Shmertz and his team at BR Labs as an institutional execution resolver engine, demonstrates how atomic borrowing alters these economics. By integrating Aave flash liquidity directly into the settlement path, BRRRolver can finance intermediate token legs during the transaction bundle itself. This eliminates the requirement for static inventory between auction rounds, expanding the set of economically clearable routes without adding balance-sheet drag. However, atomic borrowing does not create unconstrained capital: gas costs, borrowing fees, and block-inclusion timing must still clear the trade’s profit threshold before inclusion. 

The broader execution work across T-Digital, BR Capital and BR Labs treats these quantitative-trading frictions in this market structure. Adverse selection, inventory risk, route decay and latency remain active execution variables: a solution that clears economically at the beginning of an auction may no longer make sense later if gas reprices, available inventory is consumed, or another transaction alters the relevant pool state. On-chain settlement does not remove latency from the problem; it changes where the economic value of speed appears.

JIT Liquidity: Changing Executable Depth

Just-In-Time liquidity belongs in this discussion for a different reason. It is not simply another form of MEV protection; it changes the amount of liquidity available around a specific trade. A provider can deploy concentrated liquidity around an incoming trade, collect fees generated by that flow, and remove the position shortly afterward. The trader may receive better effective depth, passive Liquidity Providers (LPs) may experience fee decay, and the Just-in-Time liquidity (JIT) provider assumes timing and inventory risk.

The economics depend heavily on the quality of the incoming flow. A favorable block can compensate the provider for supplying temporary depth, while toxic flow can leave the same inventory exposed to adverse selection almost immediately. The provider may also hedge the inventory acquired through the trade elsewhere, so the relevant economics include not only pool fees but also hedging, gas and ordering costs.

JIT is therefore useful for understanding why static Total Value Locked (TVL) or a pre-trade liquidity snapshot can be misleading. The amount of liquidity sitting passively in a pool before an order appears is not necessarily identical to the depth that will compete for that order once the trade becomes visible and economically attractive to liquidity providers.

Taken together, these mechanisms show why “MEV protected” is too binary a label for an institutional desk. A transaction can avoid the public mempool and still face poor liquidity; a batch can contain opposing orders that cannot clear together; a solver can identify a superior route that becomes stale before inclusion; and a JIT provider can improve depth around one trade without making the venue structurally deeper outside that trade. The useful question is therefore not simply whether execution is MEV protected, but which part of the execution process is being improved and which risks remain.

Inside a $10 Million ETH Sale

Consider an institutional desk selling $10 million of ETH into USDC. One basis point on the ticket is worth $1,000.

The figures below remain deliberately hypothetical. They are not BR Solver, BR Capital, CoW Protocol, 1inch or Uniswap performance results, and the individual cost buckets should not be read as universal estimates. The table is intended to illustrate how different execution mechanisms can act on different components of the same order rather than to claim a fixed solver advantage.

Illustrative Execution Structure Fees / Spread Market Impact Information / MEV Cost Gas / Failure Total Cost on $10M
Public AMM routing 8 bps 20 bps 12 bps 2 bps 42 bps $42,000
Private routing, same liquidity 8 bps 20 bps 3 bps 2 bps 33 bps $33,000
Competitive solver execution 6 bps 12 bps 2 bps 1 bp 21 bps $21,000
Solver + compatible partial CoW match 5 bps 7 bps 1 bp 1 bp 14 bps $14,000

The comparison is more useful if read horizontally rather than as a claim that solvers always save 21 basis points. Each row illustrates a different change in execution structure and which cost component that change can affect.

The first comparison holds liquidity constant. The same order is routed privately rather than broadcast through the public mempool, so modeled market impact remains at 20 basis points because the available depth has not changed. Information and MEV cost falls from 12 basis points to 3, retaining nine basis points, or $9,000, on the $10 million ticket. That $9,000 is simply the arithmetic implied by the illustrative assumptions; it should not be interpreted as an estimate of the typical savings from private routing.

Competitive solver execution changes the liquidity path itself. One solver may hold inventory, another may source private liquidity, and a third may identify a more efficient multi-pool route. In the example, the winning execution structure cuts modeled market impact from 20 basis points to 12, with the improvement coming from different access to liquidity rather than concealment alone.

Opposing flow changes the economics again. If $5 million of the ETH sale can be crossed against compatible buyers inside the auction, external markets only need to absorb the remaining $5 million. Market impact falls with the residual size, inventory requirements shift, and less toxic flow needs to be hedged externally. The exact reduction in impact cannot be inferred from notional alone because the relevant liquidity curves are nonlinear.

JIT would represent another possible change to the execution structure. Instead of hiding the same order, finding another route or reducing the unmatched residual, temporary liquidity can alter the depth available on a particular route at execution time. However, assigning a fixed JIT benefit to the table would be misleading because the result depends heavily on pool structure, fee tier, hedging economics and competition among liquidity providers.

No institutional desk would hard-code a fixed solver advantage before seeing the auction. Depending on volatility, pool depth and competing flow, the difference could be 7 basis points, 15 basis points or 25, and under less favorable conditions it could be substantially smaller.

Scale makes these apparently modest improvements material. A repeatable 10 basis-point reduction in implementation shortfall across $500 million of monthly notional retains $500,000 that would otherwise disappear through execution costs. For a high-turnover strategy, execution engineering feeds directly into portfolio economics.

What Solver Markets Change for Institutional Desks

The broader lesson from operating inside solver markets is that execution is becoming an infrastructure layer of its own. Liquidity discovery, financing, order matching and settlement no longer need to be bundled into a single router or venue.

A fully on-chain institutional trading stack remains unlikely, and it does not need to be the end state for solver-based execution to matter. Portfolio construction, risk controls, and much of the decision logic can remain off-chain, while specialized execution systems compete over liquidity and blockchains provide programmable settlement where the economics justify it.

That model is closer to existing quantitative markets than the usual “TradFi moves on-chain” narrative suggests. Traditional trading desks already separate the investment decision from the machinery used to execute it; solver and resolver systems introduce a similar separation, but with public state, atomic settlement and programmable liquidity added to the execution problem.

Crypto reached 24/7 trading and API-native market access much earlier. The harder part is delivering consistent institutional execution when order size increases, volatility picks up, liquidity fragments across venues and timing becomes critical. This aligns with the market structure analysis led by Revaz Shmertz across BR Capital’s digital asset framework, backed by BR Labs’ direct operating data from BRRRolver inside competitive auction venues.  

For an institutional desk, headline TVL or aggregate DEX volume only tells part of the story. Implementation shortfall, stressed fill rates, route stability under higher latency, inventory toxicity and pre-settlement information leakage say far more about whether a venue can actually handle size. A market can look liquid on paper and still deliver poor execution once volatility rises, inventory gets consumed, or routing conditions deteriorate.

JIT adds a useful qualification in the opposite direction: a static snapshot can also understate the liquidity that becomes available around a valuable order. Executable depth is therefore dynamic in both directions – displayed liquidity may disappear when conditions deteriorate, while new liquidity or solver inventory may appear when an order creates an economic incentive to provide it.

This is the larger lesson from solver-driven execution. CoW’s batch auctions, 1inch Fusion’s resolver model, private order flow, flash liquidity and JIT are not competing names for the same mechanism; they modify different parts of the path between an execution decision and final settlement. For an institutional desk, the real question is not which protocol has the largest headline liquidity number, but which execution architecture can reliably convert available liquidity into acceptable realized fills when size and market conditions become difficult.

This material is provided solely for research and informational purposes and evaluates theoretical execution mechanics and market structure variables. It does not constitute investment advice, financial analysis, a trading recommendation, an offer or solicitation to buy or sell securities or digital assets, or an execution guarantee by Revaz (Rezo) Shmertz, BR Capital, BR Labs, Super Protocol, T-Digital, or their associated entities. 
Revaz Shmertz — an expert on on-chain payments and market infrastructure

SpaxVexo Builds an Elon Musk Era Vision for Onchain Participation

Crypto Is Searching for Its Next Coherent Technology Story

The digital-asset market does not suffer from a shortage of ideas. It suffers from too many ideas arriving without a clear relationship to one another. Artificial intelligence, decentralized trading, privacy, tokenized assets and stablecoin payments are developing in parallel, each with its own language and audience. New projects now have to do more than select a fashionable category. They must explain how different technologies fit into one usable experience. SpaxVexo is building its identity around that challenge, combining futuristic branding with a proposed platform for automated insight, community participation and token-enabled access.

The Elon Musk Era Changed How Technology Is Marketed

Elon Musk did not invent the idea of the ambitious founder, but the companies associated with him helped make engineering itself part of mass-market storytelling. Rockets, autonomous vehicles and neural interfaces became subjects of everyday online conversation. SpaxVexo draws from the same cultural atmosphere: technology presented as an attempt to expand what appears possible. There is no suggestion that Musk is connected with the token. The relevance lies in the audience expectation his era helped create. People now look for products that move quickly, publish visible milestones and communicate complex systems through a simple, repeatable mission.

SpaxVexo’s Identity Combines Access With Participation

Rather than framing the token solely as an object to buy and sell, the project describes a wider role across its planned ecosystem. Access to software tools, community functions and decision-making may be connected through a common digital asset. That approach gives SpaxVexo Token a potential purpose beyond market trading, although the distinction will ultimately depend on implementation. Utility cannot be declared into existence. Users must encounter situations in which the token makes an action possible, improves the experience or gives them a meaningful voice. The planned platform is where that claim will either become tangible or remain mostly conceptual.

AI Assistance Is Most Useful When It Reduces Noise

Crypto markets operate continuously, but human attention does not. A trader stepping away for several hours can return to thousands of messages, abrupt price movements and a new narrative already spreading across social networks. SpaxVexo’s AI direction addresses that imbalance by proposing tools capable of organizing signals and presenting relevant changes. The useful outcome is not an oracle that predicts every turn. It is a calmer information layer. An assistant might group related events, identify abnormal activity and help a user distinguish a genuine market development from recycled commentary. That would save time, though every output would still require judgment.

Explainability Should Be Treated as a Product Feature

Automated tools can become dangerous when polished language hides uncertainty. A model may describe an interpretation convincingly even when the underlying data is incomplete. SpaxVexo can respond to that weakness by showing sources inside its interface, assigning confidence levels and separating observed facts from generated analysis. At first glance, those details seem more appropriate for professional terminals than a community-oriented platform. They are increasingly necessary everywhere. Retail participants face the same volatile markets as institutions, usually with fewer safeguards. An assistant that admits what it does not know may prove more valuable than one that produces a constant stream of aggressive trading prompts.

Onchain Markets Are Raising Expectations for Speed

Users have become accustomed to digital assets moving at all hours and across multiple venues. They expect balances to update quickly, transactions to be traceable and market tools to respond without long delays. Onchain trading platforms have reinforced those expectations by bringing execution and settlement into more transparent technical environments. SpaxVexo is not required to recreate an exchange to benefit from this change. Its opportunity lies in connecting users with useful information and platform functions at the pace modern markets demand. Performance, however, includes reliability. A dashboard that is fast during quiet periods but unavailable during volatility will not earn lasting confidence.

Referral Networks Can Build Reach, but Culture Decides Quality

Projects frequently use referral incentives because personal recommendations travel further than conventional advertising in crypto communities. The mechanism is easy to understand, and it can help a new platform move across geographic boundaries. Yet not every referral creates an engaged user. Some produce accounts that disappear as soon as a campaign ends. SpaxVexo’s task is to connect discovery with deeper participation: product tutorials, community discussions, testing programs and transparent updates. That makes growth slower than a simple promotional sprint, but potentially healthier. A platform gains resilience when its users understand what it is building and can explain more than the token’s latest market price.

Governance Can Provide a Practical Role for Ownership

SpaxVexo’s governance ambitions could give token holders a route into decisions about platform priorities, community programs or future integrations. That promise should be approached with reasonable discipline. Governance systems are vulnerable to voter fatigue, low turnout and concentration among the largest wallets. Thoughtful proposal rules can reduce those weaknesses. Short summaries should accompany technical documents, conflicts of interest should be visible and voting periods should allow genuine discussion. The project may also need boundaries around which decisions belong to token holders and which remain the responsibility of developers. Clear limits usually make community authority more credible, not less.

Payment Choice Makes a Global Project More Reachable

One of crypto’s practical strengths is that users do not all need to begin with the same asset or banking relationship. A flexible payment system can accept participants from several established networks while sparing them unnecessary conversions. For SpaxVexo, that accessibility supports the international character of the project. It also adds technical responsibility. Network names must be unambiguous, deposit status should be easy to verify and customer support must be prepared for common wallet errors. A broad list of supported assets attracts attention; a carefully designed transaction flow is what prevents that convenience from turning into confusion.

Trust Will Depend on Verifiable Technical Details

Audit statements, liquidity arrangements and team disclosures are common elements in early-stage crypto communication. They can help users organize their research, but labels alone are not enough. A credible security section should identify what was reviewed, which contract version was examined and whether important findings were resolved. Contract addresses need to be published consistently, since impersonators often exploit moments when information is scattered across several social channels. SpaxVexo can strengthen its position by keeping official records current and easy to locate. This is not glamorous work. It is the routine maintenance that separates a durable platform from a campaign assembled around temporary attention.

The Token Economy Must Balance Several Interests

A project allocation model has to support liquidity, engineering, community programs and operational continuity without placing unreasonable influence in one category. Users will therefore look beyond headline percentages. They may ask about vesting schedules, treasury controls, market-making arrangements and the authority to change future distribution. SpaxVexo’s explanations should answer those questions before speculation fills the gaps. What stands out here is how quickly tokenomics has become a form of corporate governance. Decisions that would once have remained inside a private company can now affect a public network of holders from the beginning. Precision in those disclosures is part of product design.

Delivery Will Decide Whether the Vision Feels Real

An Elon Musk-era technology story naturally emphasizes scale, speed and a future that appears closer than expected. SpaxVexo has adopted that sense of momentum, but software development still advances through ordinary proof: tested releases, repaired defects, responsive support and documentation that stays aligned with the code. Early users will likely watch the repository and platform updates for evidence that the ecosystem is becoming more functional over time. Some milestones may change as technical conditions develop. The important signal will be whether those changes are explained openly and followed by working releases, giving the community a continuing record rather than a single launch-day promise.

Official website: https://SpaxVexo.com
Github: https://github.com/SPX-Token/SpaxVexo

Duraqex Explains the Records Behind Its Business Credentials

Australian representation and U.S. registration materials give users and partners specific details to check—and different types of records to understand.

Duraqex has supplied a set of documents outlining its stated business credentials in Australia and the United States. The materials include an Australian financial services authorised representative record, a U.S. money services business registration document and an image referencing an SEC filing.

For users and potential business partners, the practical question is straightforward: what does each record say about the company, and which services does it cover?

Australian Financial Services Representation

The Australian document lists DURAQEX PTY LTD as an authorised representative of OPHELEO HOLDINGS PTY LTD, the holder of Australian Financial Services licence 224485. DURAQEX PTY LTD’s representative number is 001322634, and the supplied extract marks its status as “Current.”

This record identifies the company’s relationship with an AFS licensee. The licence belongs to OPHELEO HOLDINGS PTY LTD; DURAQEX PTY LTD acts under its representative appointment. The services it may provide depend on the terms of that appointment and the licence’s scope.

Anyone assessing a particular service should therefore check that it falls within the relevant authorisation.

U.S. Money Services Business Registration

The FinCEN document lists Duraqex Ltd under MSB registration number 31000337348934. Its declared activities include foreign exchange dealing, issuing and selling money orders, and issuing traveller’s checks.

The registration number provides a reference for checking the business’s entry in FinCEN’s MSB records. The document also explains that the information is submitted by the registrant and is not verified by FinCEN.

MSB registration does not constitute FinCEN approval or endorsement, and it should not be described as a digital asset exchange licence. Its relevance to a particular service must be considered alongside any other authorisations that service requires.

SEC Filing References

The separate image names DURAQEX LTD, gives CIK 0002144180 and references Form D.

A CIK is an identifier used in the SEC’s filing system. Form D is a notice associated with an exempt securities offering. Neither establishes permission to operate an exchange or SEC approval of a company’s services.

The image and its corresponding filing have not been independently verified. They remain reference material for further checking, rather than a verified SEC certificate.

What These Records Mean for Users and Partners

The documents provide names and numbers that make further checks possible. A fuller picture requires a clear connection between those records and the business providing the service.

That means identifying the company named in the customer agreement, confirming its relationship with the Duraqex platform and checking whether its authorisations cover the service being offered. Similar company names across documents do not, on their own, establish that connection.

Each record has a specific purpose. Reading them separately—and matching them to actual services—provides a more useful understanding than treating them collectively as a broad regulatory approval.

About Duraqex

Duraqex’s project materials describe a focus on digital asset market infrastructure, including market access, custody, settlement and transparency. Service availability and authorisation depend on the relevant legal entity, contractual terms and applicable regulatory requirements.

This release is based on supplied materials. Independent verification of the underlying official records remains incomplete.

Media Contact
Duraqex
Email: info@desixb.com
Website: https://www.desixb.com/

Top Features Every Stock Market Trading App Should Have

The rise of digital investing has made stock market participation more accessible than ever. Today, investors can monitor markets, execute trades, and manage portfolios from virtually anywhere using a smartphone. However, with numerous platforms available, choosing the right app for stock market trading requires more than just looking at its interface. A reliable trading app should combine speed, security, insightful analytics, and user-friendly features to support informed investment decisions.

Whether someone is new to investing or has years of market experience, understanding the essential features of a trading app can help ensure a seamless and efficient trading experience.

  1. Intuitive and User-Friendly Interface

A stock market trading app needs to be easy to navigate without compromising functionality. Investors should be able to easily find their watchlists, market information, trading options, and portfolio details.

A clean interface provides a minimal learning curve for beginners and greater efficiency for experienced traders. Well-organised menu options and simple navigation greatly contribute to the overall user experience.

  1. Real-Time Market Data

Up-to-date information is extremely important in stock trading since prices can change at any moment. A good trading app should provide real-time information on stock prices, market indices, trading volumes, and price movements.

The availability of real-time data makes it possible for investors to closely follow market conditions and make more informed trading decisions instead of relying on delayed information.

  1. Advanced Charting and Technical Analysis Tools

Charts are an important part of understanding market trends and identifying potential opportunities. A good trading app should offer interactive charts with different timeframes and analytical tools.

Tools such as Bollinger Bands, moving averages, MACD, and candlestick charts can help traders conduct technical analysis within the app. In addition, drawing tools and other chart customization options can make the analysis process more efficient.

  1. Fast and Reliable Order Execution

Execution speed is among the various factors that can affect trading outcomes. In many situations, delays or technical issues may lead to missed opportunities or unexpected changes in execution prices.

A good trading app should execute buy and sell orders efficiently and provide users with different order types, including:

  • Market orders
  • Limit orders
  • Stop-loss orders
  • Stop-limit orders

This gives users greater flexibility when managing their trading activities.

  1. Strong Security Features

The security of trading applications is one of the most important considerations because they handle financial transactions and sensitive personal data.

Important security features include:

  • Two-factor authentication (2FA)
  • Fingerprint or facial verification for login
  • End-to-end encryption
  • Secure payment processing systems
  • Automatic logout after inactivity

Regular security updates and strict authentication systems can help protect accounts from unauthorised access.

  1. Comprehensive Portfolio Tracking

Investors want to understand their overall portfolio in addition to executing trades. An effective trading application should offer a portfolio dashboard that provides:

  • Information about current holdings
  • Allocation of investments
  • Profit or loss
  • Performance over time
  • Realised and unrealised gains
  1. Research and Educational Resources

Investors, particularly beginners, can benefit from educational tools within the app, as these resources can help them learn more about investing and financial markets.

Some educational resources might include:

  • Company-specific financial data
  • Market news
  • Analyst reports
  • Investment guides
  • Webinars and instructional videos
  • Economic calendars

Research and educational tools within the application can reduce the need to switch between multiple platforms while making investment decisions.

  1. Personalised Watchlists and Alerts

Each trader usually has their own list of companies and sectors they want to track. Watchlists can be customised according to investors’ preferences, making it easier to monitor selected stocks.

Moreover, price alerts and news notifications can save investors from having to check the app constantly for important developments.

Users can set alerts to be informed about:

  • Price movements
  • Changes in trading volumes
  • Company news
  • Financial results
  • Dividend announcements

Timely alerts can help investors stay informed about important events in the market.

  1. Easy Fund Transfers

A smooth investment experience requires efficient fund management. Trading platforms should provide easy ways to deposit or withdraw funds through secure banking channels. Features such as quick fund transfers, clear transaction records, and timely updates can make investing more efficient and help avoid unnecessary delays.

  1. Multi-Device Accessibility

Investors use multiple devices during the day, and therefore, a modern trading platform should support access through smartphones, tablets, and computers.

Cloud-based access can keep important information synchronised across devices, including watchlists, portfolios, and transaction history.

  1. Customisation Options

Each investor has their own preferences. The ability to customise dashboards, charts, watchlists, and notifications can improve the overall experience of using trading software.

Final Thoughts

Selecting the right app for stock market trading involves evaluating far more than convenience alone. A dependable platform should combine real-time market information, secure transactions, advanced analytical tools, reliable execution, and intuitive navigation to support investors across different experience levels.

Rouse Law, P.C. Highlights Iowa’s New 60 MPH Speed Limit Takes Effect on Two-Lane Highways

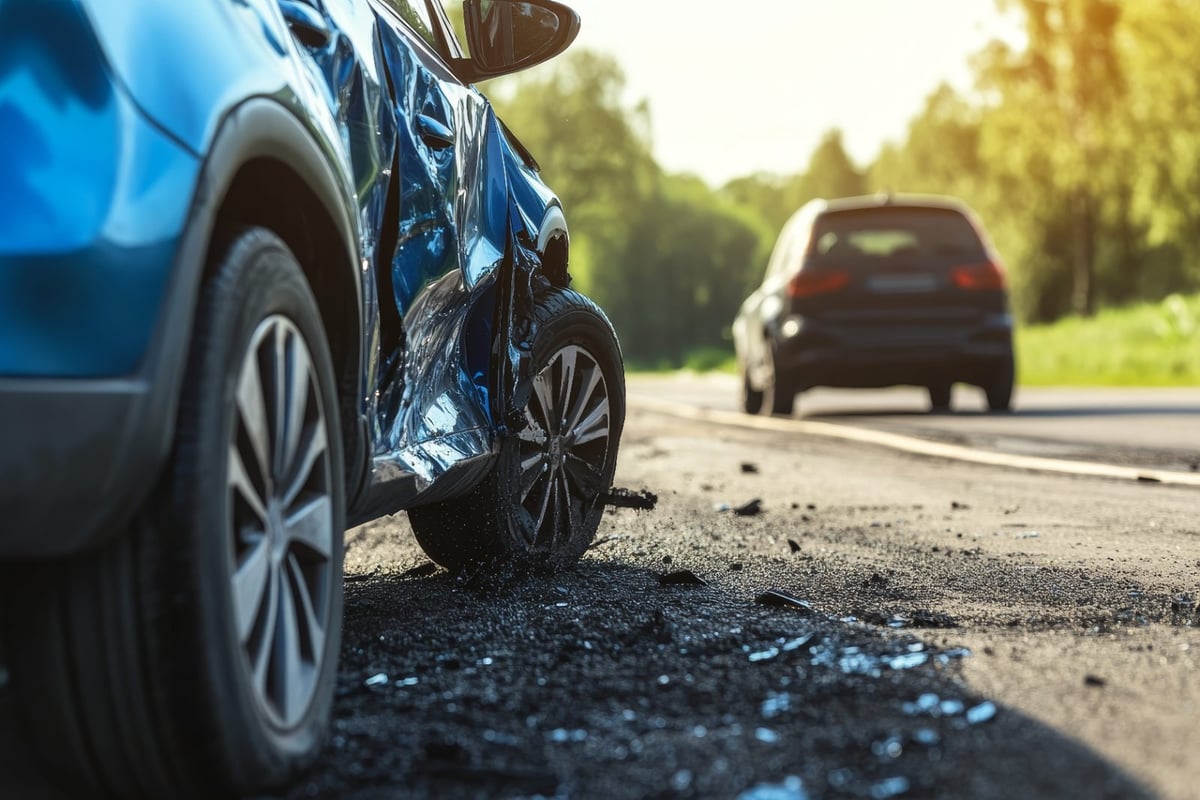
Close-up of a blue car with crash damage to the rear wheel well on a two-lane highway, with debris scattered on the road.

Des Moines personal injury attorney warns crashes may get more severe.

DES MOINES, US — September 10, 2026 — As of July 1, 2026, Iowa’s default speed limit on two-lane highways rose from 55 to 60 miles per hour under Senate File 378, signed by Governor Kim Reynolds. Des Moines personal injury attorney Ward A. (Sam) Rouse says the change, popular with many rural drivers, raises real questions about crash severity that Iowans should understand before they end up in an accident.

A Change Rural Iowa Asked For, Over Safety Objections

Lawmakers passed SF 378 after years of requests from rural constituents, clearing the Iowa House 76-16. But the bill wasn’t without opposition: the State Police Officers Council formally opposed it, citing higher rates of serious injury and death at increased speeds, and one state representative estimated the change could cause roughly six additional traffic deaths per year in Iowa. That concern lines up with independent research: a study by the Insurance Institute for Highway Safety found a 5 mph limit increase is associated with an 8.5 percent rise in highway fatality rates, and a 2.8 percent increase on other roads. Supporters of the bill, including House Speaker Pat Grassley, argued that modern vehicle safety features have made the change reasonable for rural Iowa drivers.

“A 5 mph increase doesn’t sound like much until you’re the one calculating stopping distance and impact force after a crash,” said car accident lawyer Sam Rouse, founder of Rouse Law, P.C. “The physics don’t care how popular a law is. Higher speeds mean less time to react and harder impacts when something goes wrong.”

What Stays the Same

The new law only affects two-lane highways; interstate limits remain 70 mph, and the 25 mph limit in residential and school zones is untouched. Iowa also kept a leniency provision: a driver’s first two citations within a 12-month period for going up to 5 mph over the new 60 mph limit on a two-lane highway will not affect their driving record or insurance rates.

What to Do After a Crash on a Higher-Speed Highway

Des Moines car accident attorney Sam Rouse said the practical impact is that evidence preservation matters more than before. Higher-speed collisions often produce more severe injuries, higher medical costs, and more contested liability disputes, with adjusters looking to minimize payouts before the full extent of an injury is even known. He recommends documenting the scene with photos, obtaining the police report, seeking prompt medical evaluation, and consulting an injury lawyer before giving a recorded statement to an insurer.

Rouse Law, P.C. represents injured clients throughout Des Moines, West Des Moines, and across Iowa in car accident, truck accident, motorcycle accident, and wrongful death cases, and charges no fees unless the firm secures a settlement or verdict on the client’s behalf.

About Rouse Law, P.C.

Rouse Law, P.C. is a West Des Moines, Iowa law firm founded by Des Moines personal injury lawyer Ward A. (Sam) Rouse in the mid-1990s. Sam Rouse is rated by Super Lawyers and holds an AV Preeminent rating from Martindale-Hubbell, the highest peer-review rating an attorney can receive, reserved for those recognized by fellow lawyers for the highest level of legal ability and ethical standards. The firm represents clients throughout the Des Moines area in personal injury cases, including car, truck, and motorcycle accidents, catastrophic injuries, wrongful death, and dog bites. Rouse Law, P.C. offers free consultations and charges no fees unless it secures a settlement or verdict.

View on Google Maps

Media Contact:
Name: Sam Rouse
Company: Rouse Law, P.C.
Email: wardrouse@rouselaw.us
Phone: (515) 223-9000
Address: 4940 Pleasant St, West Des Moines, IA 50266
Website: https://rouselaw.us/

Viacon Launches Specialized Digital Growth Program For Law Firms To Boost Client Acquisition In 2026

Viacon Launches Specialized Digital Growth Program For Law Firms To Boost Client Acquisition In 2026

Viacon launches a specialized digital growth program for law firms, helping them attract more qualified leads, strengthen their online presence, and drive client acquisition in 2026.

KOLKATA, IN — September 10, 2026 — Viacon has launched a specialized digital growth program for law firms and legal practices that want to strengthen online visibility, attract more relevant inquiries, and build lasting client relationships in 2026. 

The program reflects Viacon’s established position as a digital and MarTech solutions agency offering web development, organic SEO, paid media, content marketing, conversion optimization, and business growth support. It adapts those capabilities to the distinct trust, communication, and acquisition requirements of legal services.

Moving Beyond Disconnected Marketing Activity

For many firms, the problem is not a complete lack of digital activity. The problem is that search, content, the website, outreach, reviews, and lead follow-up often operate separately. 

A technically sound website may still produce weak inquiries if its practice-area pages do not match client intent. Strong content may also underperform when visitors face unclear navigation or a difficult contact process. Viacon’s program treats these issues as connected parts of one client journey.

Core Areas of the Program

The program follows the service capabilities Viacon currently presents for law firms and legal practices. Work begins with the firm’s practice areas, target clients, current visibility, website experience, communication process, and growth objectives. 

Viacon can then shape the engagement around what matters most, rather than applying the same campaign structure to every legal business. The areas are:

  • Online visibility through search strategies aligned with legal services and active client demand.

  • LinkedIn outreach and thought leadership for professional audiences and decision-makers.

Focused on Relevance, Authority, and Inquiry Quality

The approach is also consistent with Viacon’s published work in the legal sector. Assisting a legal client, the agency identified: 

  • Misaligned keyword targeting

  • Irrelevant organic traffic

  • Technical SEO limitations 

The agency rebuilt the strategy around technical optimization, legal search intent, and topical authority. That experience gives the new program a practical foundation. Visibility matters, but visibility without relevance can waste time and leave intake teams handling inquiries that don’t fit the firm’s services.

A More Accountable Route to Client Acquisition

Under the program, law firms can connect discovery with credibility and conversion. Search visibility helps prospective clients find the firm, while articles, case studies, and educational content demonstrate useful knowledge. 

A professional, responsive website directs visitors towards an appropriate next step. Structured email communication and follow-up help firms nurture genuine interest, and reputation management supports public trust. 

Looking Ahead with Viacon

Viacon’s specialized digital growth program is intended for law firms, legal consultancies, and focused practices seeking a more coordinated route to growth in 2026. It does not reduce client acquisition to traffic volume or isolated campaign metrics. 

Instead, it brings together visibility, thought leadership, website experience, communication, and reputation around a clear commercial purpose. The purpose is to help legal practices attract suitable prospects and turn digital attention into stronger client relationships.

About Viacon

Founded in 2018, Viacon describes itself as a full-service digital and MarTech solutions agency serving businesses across multiple industries and international markets. Its core capabilities cover web and application development, digital marketing, enterprise services, media production, and growth consulting. 

For legal-sector clients, Viacon focuses on tailored strategies that help practices build visibility, demonstrate authority, and develop stronger relationships with prospective and existing clients. Here you can share your digital growth aims with us, and rest assured that we will help you not only meet new clients but also build strong relationships with them.

Media Contact:
Name: Ejaz Ahmed
Company: Viacon
Email: priya.viacon@gmail.com
Phone: +919163234171
Address: Mani Casadona, 10W3 West Tower, 11F, 04 Street Number 372, Action Area I, New town West Bengal 700160
Website: https://viacon.io/

QGI Names Founder Dr. Sam Sammane Chief Executive Officer

Dr. Sam Sammane Chief Executive Officer of QGI

QGI Names Founder Dr. Sam Sammane Chief Executive Officer
Founder and architect of the company's deterministic AI platform takes the helm as QGI moves into commercial release across regulated industries.

QGI Names Founder Dr. Sam Sammane Chief Executive Officer

Founder and architect of the company’s deterministic AI platform takes the helm as QGI moves into commercial release across regulated industries.

San Diego, California — [09/09/2026] — Quantum General Intelligence, Inc. (QGI) today announced that its founder and Executive Chairman, Dr. Sam Sammane, has been appointed Chief Executive Officer, effective immediately. Dr. Sammane, who designed the company’s core technology, will continue to lead research and engineering alongside co-founder MhD Waseem Al Sammane, Chief Innovation Officer.

The appointment follows the departure of Dain Ehring, who has stepped down as Chief Executive Officer. The company thanks him for his contribution during its formation.

The problem QGI was built to solve

Generative AI has transformed how software is written, how documents are drafted and how information is retrieved. It has not transformed the industries that need it most — because in those industries, an answer that cannot be explained is an answer that cannot be used.

A lender must be able to show a regulator why a loan was approved or declined. A pharmaceutical manufacturer must be able to demonstrate to an inspector that every batch record was reviewed against the correct standard. A compliance officer must be able to reproduce, months later, exactly how a decision was reached. Probabilistic models that produce different outputs from the same inputs, and that cannot show their reasoning, fail these tests by design.

QGI was founded on a different premise: that AI can be deterministic — producing the same result from the same inputs every time — and explainable, with every step of reasoning open to inspection. Not as a constraint on capability, but as the foundation for deploying AI where the stakes are highest.

The technology

QGI’s platform combines neural and symbolic reasoning in a single architecture. Neural models handle perception, language and pattern recognition. A symbolic reasoning layer applies rules, constraints and formal logic, producing decisions that can be traced, audited and reproduced.

At the centre of the platform is QGI’s memory engine, built on a hypergraph architecture that integrates diverse data sources into a single, queryable structure. The engine allows the platform to hold context across sessions, connect information across documents and systems, and reason over structured and unstructured data together — with materially lower latency than conventional retrieval approaches.

The platform runs on QGI’s own proprietary models, including QGI Ultra, designed for transparency and reproducibility, and works alongside leading external models where customers prefer them. It exposes a full SDK, API and agent framework, so that customers and partners can build their own applications, agents and workflows on the platform rather than waiting for QGI to build them.

The result is a system in which AI can be given real responsibility in regulated environments: reviewing documents against rules, extracting and validating data, flagging exceptions, and producing outputs that stand up to audit.

The product portfolio

QGI is moving from development into commercial release across a set of products built on the same platform:

QGI Studio — a browser-based workspace that lets anyone build, test and run applications and agents on the platform with no installation and no infrastructure. Users sign in, describe what they need, and produce working applications in a session.

Deep GMP — a compliance and audit environment for FDA-regulated industries, supporting batch record review, inspection readiness and regulatory audit. Launched in partnership with an established FDA-inspection consultancy.

QGI Finance — an edition built for regulated lenders, servicers and compliance functions, supporting loan file review, pre-purchase audit, document validation and rules-based decisioning. In beta, with full release targeted for October.

Vertical applications — the platform allows industry-specific applications to be built and deployed in days rather than months. Further editions are in development for clinical trials, life sciences quality, and public-sector Private AI use.

Deployment — the platform is available as a hosted service and as a private, on-premises or air-gapped deployment for organizations with data-residency, sovereignty or security requirements.

Leadership

“I started this company because I believed AI could be held to a real standard of accountability, and that the industries which needed that most were being offered the least of it,” said Dr. Sammane. “We now have a platform that does what we set out to build. It gives the same answer every time, it shows its work, and it can be deployed where the data has to stay. My job as CEO is simple: ship it, put it in customers’ hands, and prove in production that explainable AI is not a compromise but an advantage.”

“Sam designed this architecture and he understands it more deeply than anyone,” said MhD Waseem Al Sammane, co-founder and Chief Innovation Officer. “We have spent the last year making the engine work. The next year is about making it matter to customers. Having the person who built the technology leading the company is exactly right for that stage.”

About Dr. Sam Sammane

Dr. Sammané is a three-time founder, scientist and technologist with more than two decades of experience building and scaling technology companies.

His background spans regulated industries: he has built software for FDA-regulated environments and led organizations through SOC 2 and ISO 27001 compliance, experience that directly informed QGI’s design.

He leads the company’s research, engineering and product direction, and is a frequent speaker on explainable and accountable AI.

About QGI

Quantum General Intelligence, Inc. builds deterministic, neuro-symbolic AI for regulated industries — environments where every decision must be explainable, auditable and reproducible. The company’s platform combines proprietary models, a hypergraph memory engine and a symbolic reasoning layer, exposed through a browser-based studio, an SDK and an agent framework. The platform is developed entirely in-house and is proprietary to the company.

QGI is headquartered in San Diego, California. © 2026 Quantum General Intelligence Inc. All rights reserved.

Media Contact:
Name: Sam Sammane
Company: Quantum General Intelligence Inc
Email: sam@qgi.dev
Website: https://www.qgi.dev/

The Creator Economy Is Now a Real Market — Where Growth Services Like YoyoMedia.in Fit In

Entering the Creator Economy — Why Growth Services Such as YoyoMedia.in Are Needed

Gone are the years when individuals were simply creating content without expectations of any returns. It is now a true economy that has revenue, competition, and infrastructure. With this change new products were created to help creators run their business, growth services being one of them.

 The Creator Economy Has Transformed Into a Real Business Model

What used to be about creating content just for the sake of making it has now become a full-fledged economy of different sponsors, subscriptions, and products with monetization tools provided by platforms. Today’s creators use metrics, retention, and audiences as a part of their vocabulary.

What led to this change?

  1. The monetization systems of platforms have developed – Nowadays YouTube, TikTok, and Instagram enable their users to earn money based on their viewership and content funds.
  2. The companies switched their budgets from ads to creators – Due to the rise in influencer marketing budgets, companies found it more effective to partner with creators than the advertisements of the past.
  3. Viewers trust people more than corporations – People started to prefer creators over brand accounts, making companies spend even more money on marketing.
  4. The emergence of instruments made it easier to produce content – With the editing applications, scheduling tools, and analysis dashboards, even people who do not have a corporate team can create content.

The Supporting Infrastructure Behind Creators

Category Examples of Tools/Services What They Solve
Content creation Editing apps, AI tools Faster, higher-quality production
Scheduling & analytics Native platform insights, third-party dashboards Consistency and performance tracking
Monetization Platform ad revenue, sponsorships, subscriptions Turning audience into income
Audience growth support Growth and engagement services Overcoming early visibility hurdles
Community management Comment tools, moderation bots Sustaining engagement at scale

The Cold Start Problem Every Creator Faces

Every creator no matter how talented or how good the content meets the same first problem: a new account has no history so platforms are reluctant to spread its content far. This cold start problem is one of the reasons that promising creators stop growing early long before content quality becomes the real limit.

Where Growth Support Services Fit In

This is the space that engagement and Growth Support services are made to fill. Growth Support services do not replace content strategy; they help a new or growing account overcome that first visibility barrier quickly. Platforms such as YoyoMedia.in work in this area giving audience Growth Support on Instagram, YouTube and Telegram. These services aim to give content a fair chance for early traction not to bypass quality.

What Separates Growth Support Frhttp://yoyomedia.inom Risky Shortcuts

  •  Real accounts, over bots – Sustainable Growth Support depends on real engagement, not on fake numbers that disappear fast.
  •  Support not substitution – Growth Support services work best together with a real content strategy, not as a stand‑in for it.
  • Gradual delivery – Incremental growth follows natural processes, which is much less likely to create problems than instant, artificial surges.
  • Transparency – Well-established companies disclose accurate information about their services instead of trying to overpromise.

Overall Analysis

As the creator economy continues gaining momentum, supporting tools, such as editing tools or growth services, are evolving from novelties to integral parts of a creator’s business; they are not different from the way any business requires marketing support alongside their core product.

Conclusion

As the creator economy becomes a tangible outlet on the market, it brings about a wide variety of tools that help with its functioning. Growth services such as YoyoMedia.in react to this new boom by focusing on helping creators get through the problem with obtaining visibility, so that good content gets the chance to reach its audience.

How to use AI to Screen Stocks, Forex and Other Instruments and Investments to Optimise Any Portfolio

Artificial intelligence has transformed how investors identify promising stocks and other assets. Traditional screeners required manually setting dozens of filters for valuation, growth, or technical indicators. AI tools now let you describe what you want in plain English, scan thousands of securities in seconds, and surface candidates that match complex criteria across U.S. and global markets.

This approach works for individual stocks, ETFs, and even broader investment ideas. It saves time, reduces bias, and helps uncover opportunities that simple filters might miss. Yet AI is a powerful research assistant, not a crystal ball. Success still depends on clear goals, verification, and sound judgment.

Why AI Screening Matters

Markets generate enormous volumes of data every day—financial statements, news, earnings transcripts, price action, analyst estimates, and alternative signals such as social sentiment or hiring trends. Humans cannot process all of it efficiently. AI models, especially large language models combined with quantitative engines, excel at synthesizing this information.

In the U.S., platforms can rank the entire S&P 500 or broader universes of thousands of stocks. Globally, leading tools cover major exchanges in Europe, Asia, Latin America, and beyond, often totaling 20,000 to 100,000+ securities. This reach allows investors to compare opportunities across regions while accounting for currency, regulatory, and macroeconomic differences.

Key advantages include natural-language queries, multi-factor scoring (fundamentals + technicals + sentiment), rapid iteration, and the ability to incorporate qualitative concepts such as “economic moats” or “AI beneficiaries.”

Practical Ways to Use AI for Screening

Start with a clear investment thesis. Define your style—value, growth, dividend, momentum, quality—and risk tolerance. Then use AI in these steps:

  1. Craft effective prompts.
    Be specific. Instead of “good tech stocks,” try: “U.S. large-cap technology companies with P/E under 25, revenue growth above 15% over the past three years, positive free cash flow, and strong competitive moats. Rank by quality score and exclude highly leveraged firms.”
    For global screens: “European and Asian companies in renewable energy with dividend yields above 3%, debt-to-equity below 0.5, and improving ESG scores. Focus on developed markets.”
  2. Choose the right tools.
    Free or low-cost options include ChatGPT or Grok with financial plugins/data access for idea generation and analysis. Specialized platforms offer deeper capabilities:

    • Tools like the US equities tracker on Markets.fyi offer deep insight and personalised analysis on a trader’s portfolio
    • Interactive Brokers and some brokers now include AI-configured screeners that convert English descriptions into multi-factor scans.
    • Global-focused platforms scan exchanges from NYSE/NASDAQ to London, Tokyo, Hong Kong, India, Brazil, and more.
  3. Layer multiple signals.
    Combine fundamental screens (valuation ratios, profitability, growth) with technical indicators, news sentiment via NLP models, and alternative data. Some systems run parallel agents—one for fundamentals and another for sentiment—to produce ranked shortlists.
  4. Expand beyond stocks.
    AI can screen ETFs by holdings, expense ratios, and factor exposures; identify thematic plays (e.g., “companies benefiting from supply-chain reshoring”); or even surface bonds, REITs, or international funds that fit broader portfolio goals.
  5. Iterate and refine.
    Review the initial list, ask follow-up questions (“Why did this company rank high?” or “Show me comparable firms in emerging markets”), adjust criteria, and re-screen. Many tools support backtesting simple strategies against historical data.

Handling U.S. vs. Global Markets

U.S. markets offer the deepest, most timely data and the widest selection of free/premium tools. Global screening requires attention to differences: reporting standards (GAAP vs. IFRS), liquidity, currency risk, political factors, and trading hours. Good AI platforms normalize data where possible and allow region or exchange filters. Always consider ADR availability or local brokerage access for non-U.S. names.

Important Limitations and Best Practices

AI outputs are hypotheses, not recommendations. Models can hallucinate numbers, rely on outdated data, or overfit historical patterns that fail in new regimes. Always cross-check key metrics against primary sources such as company filings (10-K/10-Q or local equivalents), reliable data providers, or official exchanges.

Other risks include over-reliance, which can lead to herd behavior if many users follow the same popular AI signals, and the fact that past performance of any AI score does not guarantee future results. Diversify, size positions appropriately, and maintain a long-term perspective aligned with your goals.

Best practices:

  • Treat AI as a filter that produces a manageable shortlist for deeper due diligence.
  • Verify facts and understand the “why” behind rankings.
  • Combine AI insights with your own research or professional advice.
  • Stay aware of fees, data latency, and coverage gaps in emerging markets.
  • Monitor for model updates and changing market conditions.

Getting Started Today

Begin with a free-tier tool or a general-purpose AI chatbot. Write a precise prompt based on your strategy, review the results critically, and dig into the top candidates. Over time, experiment with specialized platforms that match your focus—U.S. only, global equities, or multi-asset.

AI does not eliminate the need for judgment, risk management, or continuous learning. Used thoughtfully, however, it levels the playing field. Individual investors can now screen the U.S. market and opportunities around the globe with a speed and sophistication once reserved for institutional desks. The edge comes not from blindly following AI but from asking better questions and verifying the answers.

By integrating these tools into a disciplined process, investors can spend less time hunting for ideas and more time evaluating the ones that truly fit their objectives—whether at home or across international borders.

Study of 3,963 US Economic Releases Finds Forecast Misses Do Not Predict Market Reaction

Sixteen years of data show the largest payroll surprises moved currency prices no further than the smallest ones — and that several releases flagged “high impact” produce quieter-than-average hours

A new study of 3,963 high-impact US economic releases has found that the size of a data surprise — the gap between the figure economists forecast and the figure actually published — has no measurable relationship to how far markets move when it lands.

The research, conducted by the FxBacktest team, joined a 95,799-row economic calendar covering 2007 to 2026, carrying the actual, forecast and previous value of each release, to hourly currency, metals and equity index price data over the same period. Each release hour was measured against the average range of that same clock hour on weekdays containing no high-impact US release at all, giving every event a like-for-like baseline rather than a comparison against the trading day as a whole.

Across 180 non-farm payroll releases, sorting the results into three groups by surprise size produced average euro-dollar price ranges of 60.7, 64.6 and 65.5 pips in the release hour — a pip being the fourth decimal place in most currency quotes. Median figures were flatter still: 56.8 pips for the smallest third of surprises and 56.9 pips for the largest. The group with a median miss of 114,000 jobs moved the market one tenth of a pip further than the group with a median miss of 17,000.

“The forecast miss is the most visible number in the room on release day, so it gets credited with the move,” said Vasil K., CEO of FxBacktest. “What the data shows is that the market is repricing a scheduled moment of uncertainty, not the number itself. Positioning is cleared around a known event at roughly the same scale whether the print lands close to consensus or a long way from it.”

The study identifies a structural reason for the result. The payrolls report is not a single figure: the unemployment rate and average hourly earnings are published in the same instant, so a headline figure above forecast can arrive alongside a weak internal reading. The market’s response is a reading of the entire release rather than of the one line the consensus forecast was written against.

Direction proved symmetric as well. The 100 releases that came in above forecast averaged 62.0 pips of range; the 78 that came in below averaged 66.5.

Which releases actually move markets

The study does not conclude that scheduled data fails to move markets. It finds instead that the moving is concentrated in a small number of events, and that the calendar’s own impact ratings are a poor guide to which.

The Federal Reserve rate decision hour averaged 73.2 pips of euro-dollar range across 91 decisions — 5.21 times an ordinary hour at the same time of day, the largest multiple of any scheduled event in the sample. Non-farm payrolls averaged 63.6 pips, or 2.69 times normal, across 180 releases. Minutes of the Federal Open Market Committee came in at 2.67 times across 99 publications, and the consumer price index at 2.08 times across 82.

Below that, the multiples fall away quickly. Retail sales measured 1.59 times an ordinary hour, manufacturing survey data 1.46 times, gross domestic product 1.35 times, durable goods orders 1.33 times, producer prices 1.31 times and consumer confidence 1.27 times. Weekly unemployment claims — the most frequently published release the calendar flags as high impact — managed 1.21 times, barely a blip. Pooled across all 2,279 high-impact releases in the hourly sample, the average was 1.82 times.

“One event on the list runs above three times a normal hour, three run above two, and the median release runs 1.82,” said Vasil K. “A calendar that prints all of them in the same red typeface is describing the release, not the reaction to it.”

The same release, six different markets

The second finding has broader reach for anyone tracking more than one asset class, because the same scheduled event was found to produce very different responses depending on the instrument.

Weekly unemployment claims moved the euro-dollar rate 1.21 times a normal hour, gold 0.97 times, and the Nasdaq 100 index 0.49 times. That last figure is below one — meaning the hour containing a release flagged as high impact was, for that index, calmer than an ordinary hour at the same time of day. Manufacturing survey data showed the same pattern, running at 0.98 times on the same index.

The reverse also appears. The consumer price index moved the Nasdaq 100 considerably more than it moved the currency market — 2.68 times against 2.08 — a result consistent with an inflation reading being priced primarily as an interest-rate event and an equity index behaving as a long-duration asset. The dollar-yen exchange rate proved the most payroll-sensitive instrument in the set at 3.33 times normal, ahead of the euro at 2.69 and sterling at 2.28.

Across the pooled set of high-impact releases, the ranking by sensitivity ran dollar-yen at 1.84 times, euro-dollar at 1.82, sterling-dollar at 1.65, gold at 1.31, the S&P 500 at 1.23 and the Nasdaq 100 at 1.12.

Timing explains part of the headline figure

The research team cautions that the Federal Reserve’s 5.21 multiple is partly a statement about when the decision is published rather than about its importance relative to other events.

A 2:00 p.m. Eastern decision lands during an hour when the euro-dollar baseline range is roughly 13 to 14 pips, among the quietest of the trading day. Payrolls, published at 8:30 a.m. Eastern, arrive in an hour whose baseline runs 23 to 27 pips — already one of the busiest, and therefore with far less room to multiply. In absolute terms the two events are much closer than the ratios suggest, at 73.2 pips against 63.6.

The study publishes both readings side by side rather than choosing between them, on the grounds that they answer different questions: the absolute range describes how far price travelled, while the multiple describes how unusual the hour was relative to its own norm.

What happens after the release

A smaller section of the study, using 15-minute price data, examined whether the initial reaction persisted. On the pooled set of 327 releases, the direction established in the first 15 minutes was still intact four hours later 63.5% of the time.

The team stresses the limits of that figure. It says nothing about how far price travelled in the opposite direction in the interim, and the average displacement 60 minutes after a release — 23.2 pips — was smaller than the release bar’s own range of 29.5 pips, which the study describes as the signature of a spike that partially retraces. The finer-grained price files reach back only to approximately 2022, leaving individual event samples small: the consumer price index reading of 50.0% persistence rests on 18 observations, and is presented in the study as a sample-size caveat rather than a finding.

A data-quality defect in the source calendar

The research also documents a problem in the underlying calendar data that affects any study of this type, and which the team says is rarely disclosed by publishers of event statistics.

Nearly a quarter of the calendar rows — 24,699, or 25.8% — carried a midnight placeholder rather than an actual publication time. For releases issued at fixed US Eastern times, the study reconstructed the moment from the date under US Eastern daylight-saving rules, then validated that reconstruction against the rows that did carry a timestamp, accepting it only where it landed in the correct hour at least 95% of the time.

Non-farm payrolls validated at 100% of its 59 timed rows and producer prices at 100% of 48. Others failed and were used from timed rows only: the Philadelphia Fed index validated at just 19.1%, because its publication time moved from 10:00 to 8:30 a.m. Eastern during the sample period, and the federal funds rate at 88.1%, because the Committee published at 2:15 p.m. Eastern prior to 2013.

A second defect involved incorrect daylight-saving offsets on a minority of rows, which places a release in the neighbouring hour. Releases whose recorded hour fell outside the hours holding at least 15% of that event’s own history were discarded. Of the final 3,963 resolved releases, 3,367 came from the source clock and 596 from validated reconstruction. Releases published simultaneously, such as the several lines of an inflation report, were collapsed into a single event so they counted once rather than three times.

Stated limits

The team emphasises that price range is not a measure of profitability. The figures are drawn from one side of the market and exclude the cost of transacting, which widens sharply at precisely these moments, and they make no allowance for the difference between a quoted and an executed price during a fast move. Every figure in the study, the team notes, should be read as a ceiling on price movement rather than an estimate of what was capturable.

Historical statistics also describe the period measured and do not forecast future behaviour. The full dataset — release-hour ranges across six instruments, the payroll surprise analysis and the post-release persistence tables — is published free for reuse with attribution.