AIPayWithCrypto Secures $10 Million Financing WithParticipation From Multiple Institutions

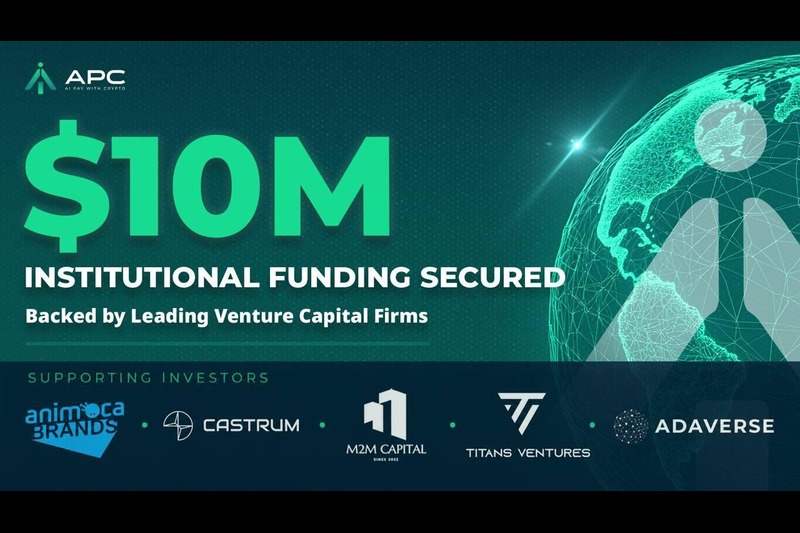
AIPayWithCrypto has officially closed a $10 million Series A financing round. The round was led by Animoca Brands, with follow-on investments from Titans Ventures, Castrum Capital, Adaverse, and M2M Capital.

Beyond capital injection, all parties have reached in-depth strategic consensus. They will jointly build the future integration of AI and payment, improve supporting infrastructure, and serve global users and AI economic entities. Going forward, APC will launch its brand-new AI-payment ecosystem on the market and consolidate its core competitiveness in the payment sector.

The financing marks an important milestone in APC’s next stage of growth and will support several strategic initiatives across the ecosystem, including:

  • Accelerated development of the AI Agent Marketplace
  • Native payment integrations across gaming and digital collectibles
  • Expanded ecosystem access through Animoca Brands’ global portfolio

These initiatives are expected to strengthen APC’s position at the intersection of AI, payments, digital assets, and intelligent commerce while creating new opportunities for ecosystem participants worldwide.

The company is already working with payment providers, merchants, and ecosystem partners across several markets and expects those relationships to deepen as new products are rolled out.

The team sees a simple reality emerging. AI systems are getting better at making decisions. Eventually, some of those decisions will involve money. When that happens, someone needs to provide the rails that allow those transactions to happen safely and predictably.

The new funding will support product development, ecosystem expansion, and merchant connectivity as APC prepares to bring its AI-payment ecosystem to market. The company is focused on building the infrastructure required for both human-driven and machine-driven transactions.

Looking ahead, APC remains focused on building practical payment infrastructure for a future where humans and intelligent systems increasingly participate in the same economy.

About APC

AIPayWithCrypto (APC) is building payment infrastructure for the AI economy. The company combines payment routing, merchant connectivity, digital asset infrastructure, and AI-compatible transaction systems to enable commerce between humans, businesses, and intelligent autonomous systems.

APC — Infrastructure for the Age of Intelligent Commerce.


Disclaimer

This content has been provided by AIPayWithCrypto and is published as received. AIPayWithCrypto is solely responsible for the information contained herein, including its accuracy and completeness.

This publication is for informational purposes only and does not constitute investment advice or an endorsement of any product or service. Readers should conduct their own research and consult a licensed financial advisor before making investment decisions.

ADEX Investigation Reveals XCSSET Supply-Chain Threat Hidden in Xcode Build Files

Limassol, Cyprus – ADEX has published a first-hand investigation into an active XCSSET malware infection targeting macOS developer pipelines, revealing how the malware hides inside Xcode project build files and spreads through developer workflows.

The investigation examined a live infection on a macOS workstation used for iOS development. ADEX found that XCSSET was not embedded in a final application, but inside Xcode project configuration files known as project.pbxproj files. These files control build instructions in Xcode, Apple’s official development environment for macOS, iOS, iPadOS, watchOS, and tvOS applications.

XCSSET is a modular macOS malware family first identified in the Summer of 2020. It is distributed through compromised Xcode projects and triggered when a developer builds the project. Once activated, the malware can harvest credentials, collect browser session data, manipulate cryptocurrency wallet addresses copied to the clipboard, establish persistence, and infect other Xcode projects on the same machine.

During the investigation, ADEX identified repeated osascript executions from /tmp/jl, a temporary file that disappeared almost immediately after running. The team captured the file and found that it was a compiled AppleScript containing obfuscated payloads. After decoding the payload, ADEX found that the malware collected system information and exfiltrated it to  the command-and-control domain riggletoy.ru.

ADEX also found that the malware had modified more than 20 Xcode projects on the affected workstation. The projects were changed within the same minute, indicating automated propagation across the machine. The investigation further identified persistence mechanisms, including a fake Launchpad.app placed in a user cache directory, as well as launch agents, shell profile injections, and git hooks.

The report explains that cleaning individual Xcode projects is not enough if the persistence layer remains active. According to ADEX, remediation should begin by removing all autostart points, including fake application files, rogue launch agents, shell profile injections, and git hooks. The system should then be rebooted before restoring Xcode projects from a known-clean git state.

ADEX’s investigation also reviewed public GitHub repositories and identified 24 repositories containing XCSSET payload chains. Examples included PrinceMittal1/DemoForAuthFlow, zzzznick/dummy-ios, and dvillegastech/ReaxBD. Twelve of the 24 repositories received commits in 2026, with the most recent just one day before inspection . The report also highlighted command-and-control domains including riggletoy.ru and netcdndev.in, with netcdndev.in described as a domain not previously found in public indicator lists at the time of the investigation.

ADEX recommends that developers manually inspect Xcode build phases before opening or building unfamiliar projects, and monitor project.pbxproj files in version control, check global git hooks, keep System Integrity Protection enabled, and use outbound firewall and persistence-monitoring tools.

For organizations, the report recommends behavioral endpoint detection on developer machines, regular auditing of third-party SDKs and dependencies, mobile device management controls, monitoring of launch agents and git hook settings, and regular rotation of API tokens. Any token stored on a compromised developer machine should be treated as exposed.

The full report positions XCSSET as a supply-chain threat because it targets the trusted relationship between developers, repositories, build systems, and downstream software users. Its effectiveness depends on hiding in build files that are commonly shared but rarely reviewed manually.

About ADEX

ADEX is a cybersecurity and fraud-prevention company focused on identifying, analyzing, and disrupting threats that affect digital businesses, developer environments, and advertising ecosystems. The company investigates malware, fraud infrastructure, account compromise, and supply-chain risks to help organizations detect exposure, strengthen defenses, and respond to active threats.

Contact Information: 

Name: Michael Gor

Company: ADEX

Website: www.ADEX.com 

Email:l marketing@ADEX.com

Where teams should learn AML, KYC, and KYB skills

AML, KYC, and KYB knowledge stopped being a compliance-team problem a while ago. Onboarding specialists, fraud analysts, risk officers, finance, and even product managers now need to understand customer due diligence, business verification, and the controls that keep financial crime out the door. The hard part isn’t agreeing that people need training. It’s finding something practical that rolls out across teams without eating the budget or everyone’s calendar.

Here’s how the strongest AML, KYC, and KYB training options stack up, and who each one really suits.

1. Sumsub Academy: free, practical, and built for whole teams

If you want training people will actually finish, start with Sumsub Academy. The courses are free, self-paced, and certificate-backed, which kills the two excuses that usually sink team training: cost and scheduling. You get coverage across all three disciplines, with the aml courses, How to Collect Data for Successful KYC, Business Verification Fundamentals, and Business Verification Advanced.

The format is what makes it stick. Lessons are short and built around the calls an analyst makes mid-case: which document to request, when a name mismatch matters, when to escalate. A new hire can run a module between onboarding calls instead of blocking out a full afternoon. That’s also why it reaches past compliance officers. A product manager who works through the KYC course designs cleaner verification flows the first time, instead of shipping something the risk team has to unpick later.

Best for

  • teams that want free, job-ready training
  • companies upskilling several functions at once
  • professionals who want certification without a big time or budget hit

2. ACAMS: the recognized name in AML certification

ACAMS is the credential people recognize on sight. If an analyst wants a line on their CV that hiring managers and auditors already trust, the CAMS certification carries weight a free course hasn’t built yet. The trade-off is honest: it costs real money, takes months, and leans toward formal study rather than day-one workflow. It does broaden out into customer due diligence and financial crime prevention, so the reading isn’t narrow.

Best for

  • professionals chasing an established AML credential
  • specialists who want formal certification
  • organizations funding traditional compliance education

3. ICA: structured qualifications for the loicang haul

The International Compliance Association runs the route for people who want depth, not a weekend skim. Its AML and KYC qualifications are built as proper study programs, with the structure and assessment that fit someone building a specialist career over years. If a team member wants a formal learning path and the budget supports it, ICA delivers that. Don’t expect a quick option you can drop into onboarding next week, because that was never the point of it.

Best for

  • professionals after deeper, formal study
  • people building long-term specialist credentials
  • organizations with structured training budgets

4. ACFCS: financial crime training that crosses silos

ACFCS earns its place when your people don’t sit neatly in one box. Plenty of analysts touch AML, fraud, investigations, and risk in the same week, and ACFCS treats those as connected work rather than separate worlds. For an investigator who needs to see how a fraud pattern feeds an AML case, that wider financial crime lens is the whole value.

Best for

  • professionals working across fraud and AML
  • investigators and financial crime specialists
  • teams that want broad financial crime context

5. In-house programs: full control, ongoing upkeep

Some larger firms build their own AML, KYC, and KYB training from scratch. It makes sense when the processes are unusual and the material has to mirror exact systems, policies, and escalation paths. A bank running a custom case-management tool can’t teach that from a generic course. The cost shows up later: someone has to keep the content current every time a rule or a workflow shifts, and that maintenance bill never really lands at zero.

Best for

  • larger organizations with mature compliance functions
  • businesses with highly specific workflows
  • teams layering company-specific enablement onto broader learning

How to pick a compliance course your team will actually use

Strip out the marketing and the training that works tends to share five traits:

  • content that maps to the job, not the textbook
  • real workflows over abstract theory
  • a rollout that doesn’t need its own project plan
  • self-paced, flexible access
  • value that earns back the time and money

This is where free, self-paced platforms pull ahead. They drop the barrier to entry, turn upskilling into a habit rather than a once-a-year event, and give everyone the same baseline to reason from when a tricky case lands on the desk.

So which one should you pick?

It comes down to what you’re optimizing for, and the honest answer splits in two. Chasing a formal, recognized credential for a few key people? ACAMS, ICA, and ACFCS still own that ground. Trying to lift a whole team’s everyday judgment without a procurement fight? Start with Sumsub Academy and layer the formal certifications on top for the handful who need them. The move that wastes the most money is buying expensive certificates that gather dust while the onboarding decisions stay exactly as messy as they were.

Financial Planning Pressures That Can Shape Family Assets and Cross Border Decisions

Financial decisions rarely sit apart from the wider economy. Families, business owners, investors, and professionals often make private plans while watching interest rates, property values, currency movement, inflation, and market confidence. When asset prices shift or borrowing becomes more expensive, people tend to review the way their savings, real estate, business interests, and long-term obligations are arranged. This kind of review is not only about growth or returns. It is also about protection, continuity, and making sure financial documents can support practical decisions when life becomes more complex.

The same pressure can appear when personal matters overlap with larger financial commitments. A family may own property in more than one place, hold investments across different accounts, or depend on income tied to a business or professional role. In those situations, planning becomes less about one isolated issue and more about how different financial responsibilities connect. A market downturn, a major life event, a relocation, or a change in family structure can expose gaps that were easy to overlook during calmer periods. That is why financial planning often expands beyond portfolios and savings goals into matters involving documentation, legal process, and asset transfer.

Estate Matters and the Value of Clear Asset Records

When a family is dealing with estate matters, financial organization can quickly become central to the process. Bank accounts, real estate, retirement assets, business shares, insurance policies, debts, tax records, and beneficiary information may all need to be reviewed with care. According to www.aldenlawfirm.com, in that setting, a probate lawyer can be involved when assets must be handled through a formal process after someone passes away. While the financial side may seem straightforward at first, complications often appear when documents are outdated, property ownership is unclear, or family members have different expectations about timing and distribution.

From an investment and financial planning perspective, the issue is not only legal procedure. It is also about preserving asset value, limiting unnecessary delays, and keeping financial decisions organized during a difficult period. If a property needs maintenance, a business interest needs attention, or an account must be accessed for required expenses, delays can affect more than paperwork. They can influence liquidity, tax exposure, and the ability of a family to make timely decisions. Clear records, updated ownership details, and accurate financial information can make the process more manageable and reduce confusion when multiple assets or beneficiaries are involved.

Cross Border Goals and Financial Commitments

Cross border planning often brings another layer of financial pressure. A professional may be moving for work, an investor may be expanding activity into another country, or a family may be balancing income, property, education, and long-term residence plans across different jurisdictions. As mentioned by saavedraperezlaw.com, in these situations, a visa lawyer may become relevant when immigration status affects the ability to work, invest, study, remain in a country, or manage obligations tied to relocation. The financial effects can be significant because timing, eligibility, and documentation may influence income continuity, housing decisions, and business planning.

These decisions can also affect how people structure their assets and obligations. A delayed approval, a change in status, or a requirement for additional documentation may alter employment plans, investment timelines, travel schedules, and family budgets. For investors and professionals, this can create uncertainty around cash flow, tax planning, and access to local financial systems. Therefore, cross border planning often requires more than comparing opportunities in different markets. It requires careful attention to how personal status, financial commitments, and documentation work together before major commitments are made.

Liquidity Concerns During Major Life Transitions

Liquidity becomes especially important when families or individuals face major transitions. An investment account may look strong on paper, but available cash can still be limited when expenses arrive quickly. Property costs, tax obligations, professional fees, relocation expenses, business payments, and family support can all place pressure on short-term funds. When markets are volatile, selling assets at the wrong time may create losses or reduce long-term value. As a result, people often need to think carefully about which assets are accessible, which ones are restricted, and which ones should remain untouched unless absolutely necessary.

This is where personal planning and market awareness often meet. A person may hold assets that perform well over time, yet those assets may not solve immediate financial needs. Real estate can take time to sell, private business interests may be difficult to value, and retirement accounts may carry penalties or tax consequences if accessed early. Meanwhile, family or relocation issues may require decisions within weeks rather than months. A practical financial plan accounts for both long-term value and short-term access, especially when legal, administrative, or personal deadlines are involved.

Risk Management Across Assets and Obligations

Risk management is not limited to market exposure. It also includes the risk of missing documents, unclear ownership, delayed approvals, tax problems, currency movement, and poor timing. A diversified portfolio may reduce investment risk, but it cannot fix weak recordkeeping or unclear authority over assets. Likewise, strong income may not protect a family from disruption if important documents are incomplete or if major decisions depend on approvals that are outside their control. These risks are often quiet until a transaction, transition, or family event makes them urgent.

Good planning focuses on reducing avoidable uncertainty. That can mean keeping financial records current, reviewing account ownership, maintaining accurate beneficiary details, tracking property obligations, and understanding how personal decisions may affect taxes, liquidity, and investment timing. It can also mean avoiding rushed commitments when documentation is incomplete. In a financial environment shaped by changing rates, shifting markets, and global mobility, people benefit from treating paperwork and planning as part of their broader financial position rather than as separate tasks handled only when pressure appears.

Stronger Planning Creates More Financial Control

A stable financial plan does not remove uncertainty, but it gives people more control when personal and market conditions become complicated. Families with clear records, organized accounts, and realistic liquidity plans are often better positioned to respond when life events affect assets, income, or long-term commitments. Professionals and investors with cross border goals can also make stronger decisions when they account for timing, documentation, tax exposure, and access to funds before making major moves. The goal is not to predict every outcome. The goal is to reduce confusion and protect financial flexibility.

Financial planning works best when it reflects the full picture of a person’s life. Markets matter, but so do family obligations, asset transfer issues, relocation plans, legal requirements, and the practical timing of decisions. When those pieces are reviewed together, people can make choices with a clearer view of risk and responsibility. That broader approach can protect assets, support continuity, and make difficult transitions easier to manage without losing sight of long-term financial goals.

Legal Costs That Shape Financial Risk After Serious Care And Injury Claims

Serious injury and care-related disputes can carry financial consequences long before a case reaches a formal hearing, settlement discussion, or trial date. For individuals, families, insurers, employers, and legal teams, the early phase often creates a chain of costs that may not appear clearly on a balance sheet at first. Medical bills, lost income, reduced work capacity, expert review fees, insurance correspondence, administrative delays, and document preparation can all shape the economic pressure surrounding a claim. In a financial context, these matters are not only about personal harm or legal rights. They also involve measurable risk, resource allocation, liability forecasting, and the difficult task of estimating how one event may affect future expenses.

For investors, business owners, and professionals who follow financial markets, these claims also show how legal exposure connects with broader economic behavior. A single dispute may involve health providers, insurers, employers, transportation companies, professional service firms, and local legal practices. Each party may face direct or indirect costs depending on the facts, documentation, and timing involved. Therefore, legal claims tied to serious care concerns or physical injuries often become financial events as much as legal ones. They require careful review because the value of a claim can shift as records develop, treatment continues, income losses become clearer, and long-term needs are evaluated.

How medical malpractice claims create legal and financial pressure

According to one legal team, medical malpractice claims often involve allegations that professional care fell below an accepted standard and caused measurable harm. Within the legal scope, these matters usually require detailed review of records, expert opinions, timelines, consent issues, treatment decisions, and the connection between the care provided and the harm claimed. Because the facts are often technical, legal teams must examine whether the outcome came from an unavoidable complication, an administrative failure, a diagnostic concern, a treatment error, or another issue supported by evidence. This makes the financial side more complex because the cost of building or defending a claim can increase quickly as more documentation and expert analysis become necessary.

The financial weight of these claims can extend beyond the person bringing the case. Healthcare practices may face insurance premium pressure, reputational concerns, internal compliance reviews, and operational costs connected to defending the matter. Patients may deal with added care expenses, income disruption, and uncertainty about future treatment needs. Insurers must evaluate reserve amounts, settlement exposure, and the likelihood of litigation costs rising over time. As a result, medical malpractice matters are often viewed through both legal and economic lenses. The claim value depends not only on the alleged harm, but also on the strength of proof, the projected cost of future care, the quality of documentation, and the risks each side faces if the dispute continues.

Why car accident claims matter within legal practice economics

As mentioned by www.pcw-law.com, a car accident claim may appear straightforward at first, yet legal practices often treat these cases as financially layered matters because injuries, liability issues, insurance limits, and documentation can vary widely. Lawyers may review police reports, medical records, wage information, vehicle damage, witness accounts, and treatment timelines to determine how the claim should be valued. Even when fault seems clear, disputes can arise over the severity of injuries, whether symptoms came from the crash, whether treatment was necessary, and how future limitations should be measured. This creates a practical connection between legal strategy and financial assessment because every missing record or unclear fact can affect negotiation strength.

For law firms that handle injury claims, these cases require operational planning as well as legal analysis. Attorneys and staff may invest time in client intake, evidence collection, insurer communication, medical billing review, demand preparation, and litigation readiness. The firm must also consider case costs, expected recovery, timelines, and the probability that settlement discussions will resolve the matter without extended court involvement. From a broader business perspective, injury claims show how legal services operate in a risk-based environment. Value depends on facts, documentation, liability, available coverage, and the ability to present damages in a way that withstands review from insurers, opposing counsel, and courts.

Insurance reserves and claim valuation affect financial planning

Insurance companies play a major role in shaping the financial path of serious injury and care-related claims. Once a claim is opened, insurers often assign reserves based on the estimated amount that may be needed to resolve it. These reserves can change as new records arrive, liability becomes clearer, treatment progresses, or damages appear larger than initially expected. Reserve decisions are not merely internal accounting choices. They influence settlement posture, litigation strategy, reporting obligations, and the way companies assess overall exposure across a portfolio of claims. When many high-value claims arise in a short period, the effect can reach underwriting practices and premium calculations.

Claim valuation also requires careful financial judgment because early estimates may not capture the full economic picture. A claim involving short-term treatment may later include surgery, ongoing therapy, reduced earning capacity, or permanent limitations. Conversely, a claim that initially appears costly may become less severe if recovery is strong or documentation fails to support future losses. This uncertainty makes legal claims difficult to price. For businesses and insurers, the challenge is similar to evaluating any uncertain liability. The available information must be weighed against future probability, possible litigation expenses, and the cost of resolving the matter sooner rather than allowing the dispute to continue.

Documentation often determines the financial strength of a claim

The financial strength of a serious claim often depends on the quality and consistency of documentation. Medical records, billing statements, employment records, photographs, correspondence, incident reports, and expert reviews can all support or weaken the value assigned to a dispute. Incomplete records may make it harder to connect losses to the event in question, while organized documentation can make damages easier to evaluate. This is why legal teams usually treat records as financial evidence, not just background information. They show what happened, what it cost, how long the effects lasted, and whether future losses can be estimated with reasonable support.

Documentation also affects negotiation behavior. When a claim file is clear, complete, and supported by consistent records, insurers and opposing parties may have less room to dispute the financial demand. However, when gaps exist, the value of the claim may be challenged, delayed, or reduced. This dynamic matters because time itself has a cost. Longer disputes may increase legal expenses, delay payment, strain personal finances, and create uncertainty for businesses carrying potential liabilities. In practical terms, strong documentation helps convert a disputed event into a more measurable financial issue. That measurement is often what allows parties to evaluate risk, negotiate responsibly, and avoid unnecessary escalation.

Careful claim analysis supports better financial decisions

Legal claims involving serious care concerns or physical injuries require more than a basic review of who was harmed and who may be responsible. They require financial analysis that accounts for past costs, future needs, liability disputes, insurance limits, legal expenses, and the practical risk of continued conflict. For individuals, that analysis can shape decisions about settlement, treatment planning, and income protection. For businesses, insurers, and legal practices, it can influence reserves, staffing, case strategy, and long-term exposure management. The strongest decisions usually come from treating the claim as both a legal matter and a financial event with consequences that may extend well beyond the first demand letter.

A careful approach also helps reduce avoidable uncertainty. When facts are organized, damages are supported, and risks are evaluated realistically, each party can make better decisions about whether to negotiate, defend, settle, or continue developing the case. This does not remove the personal seriousness of injury or care-related harm, but it does place the dispute within a clearer economic framework. In markets, uncertainty affects value, and the same principle applies to legal claims. Better information creates better valuation, and better valuation supports more disciplined decisions for everyone involved.

SpaceX IPO Consolidates Infrastructure for the Next Phase of Space Enterprise

The integration of launch dominance, Starlink broadband, and AI computing into a single corporate ecosystem raises critical supply chain questions for global markets.

The technology sector is undergoing a structural transition that extends far beyond orbital logistics. The impending SpaceX initial public offering functions as more than a capital raise for spaceflight; it establishes the framework for a unified operating system targeting a multiplanetary economy. By combining global launch operations with the Starlink communications network, advanced computational systems, and autonomous robotics, one organisation is positioning itself to control the primary transport and digital networks of space expansion. This centralisation of critical infrastructure provides significant operational scale, yet it simultaneously forces governments and enterprises to scrutinise market competition, system reliability, and the governance of a single-vendor supply chain.

To make sense of this shifting paradigm, we sat down with Maury Blackman, a veteran technology executive and venture capitalist. As the Managing Director of Pierpoint Ventures, the Founder and Chairman of Insight Integrity, and the CEO of Velosimo, Blackman has spent his career building interconnected tech ecosystems, scaling public sector solutions, and identifying high growth startups. You can learn more about his background at Maury Blackman. In this interview, we explore the strategic implications of the SpaceX mega IPO, what a fully integrated tech stack means for the broader market, and how unified automation platforms will dictate the next era of human industry.

Q: Your recent piece compares the SpaceX IPO to the British East India Company, framing it as a complete “civilizational operating system.” As a CEO who builds deeply integrated tech ecosystems, how viable is it for a single corporate entity to securely manage the transport, communication, and software layers of space expansion?

MAURY BLACKMAN-Technically it is viable, and that is precisely what should give us pause. I have spent my career building platforms where the value lives in the connective tissue between layers rather than in any single layer alone. When you control launch, the orbital communications mesh, the computer, and the robotics, you do not just own products. You own the protocol that every other participant has to speak.

The East India Company comparison holds because that firm was never only a trading house. It became the administrative, military, and monetary authority across an entire subcontinent. A vertically integrated space enterprise can absolutely run securely as a closed system. The harder question is not whether one company can manage these layers. It is whether the rest of us should accept a future where the operating system of human expansion has a single vendor, a single failure mode, and a single set of commercial incentives. Security inside the stack is not the same thing as security for the people who depend on it.

Q: The article highlights the aggressive integration of satellite networks, AI, and robotics under one corporate umbrella. From your vantage point as an investor, how does a mega platform of this scale disrupt the traditional venture capital model for emerging deep tech startups?

MAURY BLACKMAN-It changes the entire shape of the funding conversation. For two decades the venture playbook for deep tech assumed an eventual exit through acquisition or public offering, with a handful of plausible strategic buyers. When one platform absorbs launch, connectivity, compute, and automation, that buyer universe collapses toward a single dominant acquirer. Founders now have to ask a question that used to be theoretical. Are we building a company, or are we building a feature that the platform will eventually replicate or absorb?

At Pierpoint we look hard at where a startup sits relative to that gravity well. The companies I find most fundable are the ones solving a problem the mega platform structurally cannot prioritize, because it sits outside their margin model or their attention. Capital does not disappear in this environment. It concentrates. The risk is that early stage investors start underwriting only the ideas that complement the giant rather than the ones that might one day challenge it, and that is how you starve the next generation of genuine alternatives.

Q: Advanced AI and autonomous coding models are increasingly positioned as the operational stack that will power off world operations. Given your work with data systems, what are the primary governance and reliability risks of deploying autonomous software systems across complex, distributed networks?

MAURY BLACKMAN-The first risk is provenance. When autonomous systems write, deploy, and modify code across a distributed network, you lose the clean chain of accountability that traditional change management gave you. If you cannot answer who or what made a decision, and on what data, you cannot govern it. The second risk is correlated failure. Distributed does not mean independent. When every node runs the same underlying model and the same assumptions, a flaw does not stay local. It propagates at machine speed across the whole mesh before a human ever sees it.

I have spent years working in environments where data integrity is the entire product, and the lesson is consistent. The reliability of an autonomous system is only as good as the verifiability of its inputs and the auditability of its actions. For off world operations the stakes rise because latency removes the option of real time human intervention. The governance answer is not to slow the automation. It is to build independent verification, tamper evident logging, and trust layers that sit outside the system being trusted. You cannot let the same entity be both the actor and the auditor.

Q: Drawing on your extensive background in government technology and public communications, what are the core challenges when privately owned infrastructure platforms become the definitive information and utility networks for public use?

MAURY BLACKMAN-The core challenge is that public obligations and private incentives are not the same thing, and infrastructure forces them into the same room. I spent years building software for state and local government, and the defining feature of public infrastructure is that it has to serve everyone, including the unprofitable, the remote, and the inconvenient. A private network optimizes for return. Most of the time those goals overlap. The problem lives in the cases where they do not.

When a single company controls the connectivity that emergency services, schools, and elections depend on, that company holds leverage that looks a lot like sovereignty without any of the democratic accountability that comes with it. Pricing, access, content decisions, and uptime stop being commercial questions and become questions of civic participation. The honest answer is that our regulatory frameworks were built for utilities that were geographically bounded and slow to change. They are not ready for infrastructure that is global, software defined, and owned by one firm. We need governance that treats critical private infrastructure as a public trust, with transparency obligations and continuity guarantees that match the role it actually plays.

Q: The financial press is fixated on multitrillion dollar valuations and massive retail carve outs. As an entrepreneur and investor, what downstream effects do you anticipate an IPO of this magnitude will have on overall market liquidity and the ability of smaller tech firms to secure funding?

MAURY BLACKMAN-An offering of this size acts like a gravitational mass on the entire market. In the near term it pulls an enormous volume of capital toward a single name, and that capital has to come from somewhere. Institutional allocators rebalance, index funds are forced to buy, and attention concentrates. For a window, smaller tech firms can find it harder to compete for the same dollars, because every generalist investor wants exposure to the marquee story.

There is also a longer arc that I think is more interesting. A successful offering of this scale validates an entire category and can lift sentiment across adjacent sectors, which eventually loosens funding for companies that ride the same thesis. So the picture is not uniformly negative for the smaller player. The firms that struggle are the ones with no clear relationship to the dominant narrative. The firms that benefit are the ones investors can frame as participating in the same future. My advice to founders is unglamorous. Do not try to compete for attention during the peak of the frenzy. Build the durable thing, and position it so that capital finds it when the rebalancing settles.

Q: We are looking at a future where a single platform might dominate the robotics workforce, the communications backbone, and the transport vehicles for industry. For specialized software platforms and integration companies trying to plug into this ecosystem, what is the best strategy to stay relevant?

MAURY BLACKMAN-Become the layer the giant does not want to build and cannot afford to ignore. This is the entire thesis behind the integration work I do. Dominant platforms are extraordinary at depth and surprisingly weak at breadth across systems they do not own. They will never invest in connecting gracefully to the thousand legacy environments, regulatory regimes, and niche workflows that real enterprises and governments actually run on. That gap is the opportunity.

The right strategy has three parts. First, own the interoperability, because the value of any ecosystem is ultimately bounded by what it can connect to, and that is where independent integration companies earn their seat. Second, own trust and verification, because as more of the stack becomes autonomous, someone neutral has to certify that the data and the actions are what they claim to be. Third, stay portable. Never let a single platform become your only distribution channel or your only buyer, because the moment you do, your roadmap belongs to them. Relevance in this future does not come from competing with the backbone. It comes from being the connective and trust infrastructure that the backbone depends on and cannot replace.

This upcoming financial milestone represents much more than a massive capital raise. It signals a fundamental shift in how global infrastructure is built, funded, and deployed. The insights discussed today highlight that as tech platforms scale to encompass entire industries, from AI and robotics to satellite communications, the need for seamless, reliable integration becomes critical. Governing these massive ecosystems will require not just capital, but advanced technological oversight, strategic partnerships, and robust data integrity.

Looking ahead, the success of the next industrial frontier will depend entirely on systems that can reliably connect complex, disparate layers of infrastructure. Whether managing operations on Earth or navigating the logistics of space expansion, bridging the gap between hardware, software, and human operations remains the defining challenge for leadership. Enterprises and investors who prioritize secure, scalable integrations will be the ones who truly unlock the potential of these emerging mega platforms.

To learn more, visit www.pierpointventures.com

Disclaimer: Maury Blackman is Managing Director of Pierpoint Ventures, Founder and Chairman of Insight Integrity, and CEO of Velosimo. The views expressed are his own. This article is commentary, not investment advice.

Day Trading vs. Swing Trading: Which Strategy Should a Beginner Choose on the Kayeventures Platform?

Entering the world of financial markets can be an overwhelming experience for a beginner, primarily because of the sheer volume of information and the variety of approaches to trading. The choice of a trading style is a foundational decision that will dictate your daily routine, psychological workload, and ultimately, your financial results. Among the many methodologies available today, day trading and swing trading remain the two most popular paths for retail traders. The analysts at Kayeventures have broken down both approaches to help novice market participants choose the strategy that best aligns with their goals, risk tolerance, and available time.

Day Trading: High Speed and Intense Dynamics

Day trading, or intraday trading, involves opening and closing positions within a single trading session. A day trader never leaves trades open overnight, completely eliminating the risk of unexpected morning gaps, which are sharp price jumps that occur between market sessions due to overnight news. This trading style demands maximum concentration and a significant time commitment, as practitioners must constantly monitor charts, order books, and real-time news feeds. Seconds matter here, and trades are often executed on lower timeframes, such as one-minute or five-minute intervals.

For a beginner, day trading can be highly stressful and emotionally draining. The rapid pace of decision-making frequently triggers psychological traps, leading novices to overtrade or abandon their risk management rules in the heat of the moment. However, for those who can maintain strict discipline, day trading offers deep market immersion and the potential for quick compounding of capital. The technological infrastructure of Kayeventures is fully optimized for this intense style, providing ultra-fast order execution and minimal slippage, which are critical components when trading inside the day.

Swing Trading: Freedom of Movement and Deep Analytics

Swing trading represents a completely different philosophy, focusing on capturing price momentum, or swings, over a period of several days to several weeks. Swing traders operate on larger timeframes, such as four-hour or daily charts, allowing them to look past short-term market noise and identify stronger, more sustainable institutional trends. This approach does not require sitting in front of a monitor for eight hours a day; a few hours of high-quality analysis in the evening or before the market opens is usually more than enough to manage a portfolio.

This strategy is often considered far more suitable for beginners because it provides ample time to think, verify signals, and calculate position sizes without psychological pressure. Overnight risks do exist in swing trading, but they are mitigated by wider stop-losses and precise capital allocation. By focusing on broader economic factors and structural chart patterns, beginners can develop a deeper, more mature understanding of market mechanics rather than just reacting to erratic price ticks.

Building Trust and Trading Expertise in the Modern Era

Regardless of the chosen strategy, the reliability of your execution partner remains the most critical factor in your trading career. At a time when new traders diligently research industry benchmarks, checking Kayeventures reviews and studying peer feedback across international forums, our platform stands out through its total transparency. We believe that an educated trader is a successful trader, which is why we complement our high-tech terminal with comprehensive educational materials and deep market analytics for both intraday and swing strategies.

When beginners ask if the Kayeventures legit infrastructure can truly support their growth, they find their answer in our robust risk management tools, clear fee structures, and stable performance. We do not push users toward aggressive, high-risk behavior; instead, we provide the flexible environment necessary to master either day trading or swing trading at a sustainable pace. By prioritizing user education and providing elite trading conditions, Kayeventures ensures that every client can confidently develop their skills and build a reliable path toward financial independence.

Disclaimer

This content has been provided by Kayeventures and is published as received. Kayeventures is solely responsible for the information contained herein, including its accuracy and completeness. This publication is for informational purposes only and does not constitute investment advice or an endorsement of any product or service. Readers should conduct their own research and consult a licensed financial advisor before making investment decisions.

Inside Capital 2026: Investing Platform Co-Founders on the New Residential Property Opportunity for Wholesale Investors

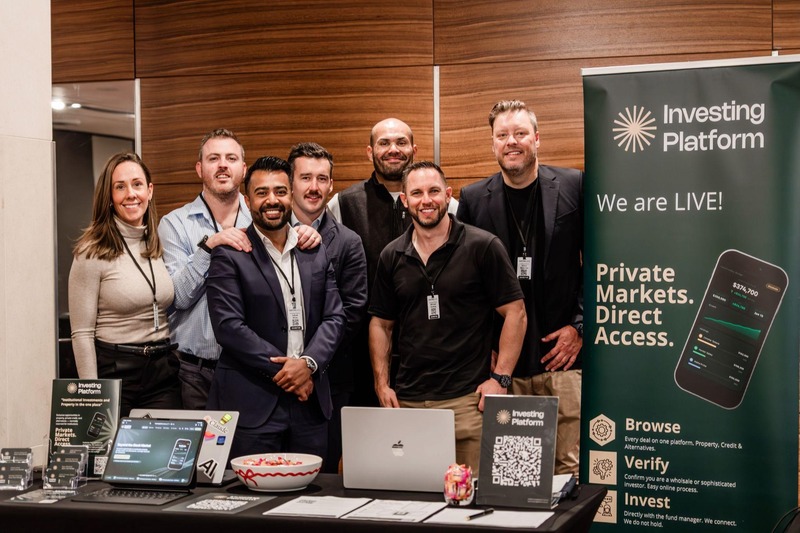
Adnan Tanveer and Adam Newman, co-founders of Investing Platform, sat down after two days at Capital 2026 to share what they heard, what they pitched, and why brand-new, negatively geared property is the allocation story they believe wholesale investors can’t afford to ignore right now.

Day 1: Inside the Room

Interviewer: Adnan, for readers who aren’t familiar with Capital 2026 — what is it, and why does it matter?

Adnan: Capital 2026 matters because it’s one of the largest wholesale investor conferences in Sydney, and in Australia. Steve Torso, the organiser and the brain behind the whole conference, has put together a real beast of an event, which brings together a huge number of wholesale investors, and a lot of fund managers, all in one place. That’s really the reason it matters.

Interviewer: Adam, what was the atmosphere actually like walking in, especially on day one?

Adam: It’s a very professionally run conference, and you could see people were excited to be there. It was very well attended from the time the doors opened, and there was a bit of buzz around a lot of strong conversations happening from the minute the doors opened.

Interviewer: Adnan, who specifically was in the room? Give us a sense of the names and the calibre of the attendees.

Adnan: There were some well-established fund managers in there. We met with Pengana Capital Group, Centuria Capital Group and Harbour Credit Partners. Phoenix Growth Fund was there as well, and we met a couple of other interesting ones who were more active in the crypto space… not our particular sector, so I won’t pretend to remember all of them. But it was a really good mix.

Interviewer: Adam, what were the main themes the conference was built around this year?

Adam: The themes were broadly around the investment ecosystem, heavily based around private credit, institutional funds and property. But the main talking points, time and time again, were the decisions in the federal budget: the changes to capital gains tax, and the changes to negative gearing, where we see a real opportunity.

Interviewer: Adnan, on day one, which presentations and sessions stood out?

Adnan: The presentations around private credit, and the funds that were invested in residential property, stood out, and there were some presentations made around commercial property too. The one thing I did feel in the room was that there was less enthusiasm around commercial property, or that people just don’t understand it that well yet.

Interviewer: Adam, how did you find the overall quality of the presentations?

Adam: They were all very strong, and all thematically similar. The way the presentations are run, people only get a tight window to present, which means they really hit on their strongest points. And the themes were the same throughout: there are opportunities in property, opportunities in private credit, and opportunities for really well-run funds to deliver a yield and an opportunity to investors.

“Negative gearing is a huge topic right now. It wasn’t only on investors’ minds — it was on the fund managers’ minds too.”  — Adnan Tanveer

Interviewer: Adnan, the federal budget’s negative gearing changes were a big topic heading into the conference. How did they play out in the room?

Adnan: Negative gearing is a huge topic right now, and everyone’s talking about it. It was not only on investors’ minds… speaking with a lot of people in the room, it was clearly on the fund managers’ minds too. What was interesting was that some of them seemed a bit lost on it. That was quite a notable theme.

Interviewer: Adam, break down the negative gearing case for wholesale investors reading this who want the specifics.

Adam: Look, it’s not my place to break down government policy. What we understand is that negative gearing will be changed for existing properties… that benefit will no longer be offered… However, it will remain grandfathered for those who are already invested, and it will remain in place for new properties. That’s really exciting for us, given that we’ve launched the Investing Platform with 484 new properties available for purchase on it.

Interviewer: Adnan, what projects does www.investingplatform.com.au currently have on the platform?

Adnan: It’s quite straightforward. As my business partner said, we have 450-plus physical, brand-new properties on there, which includes apartments in Parramatta, Gosford and Lindfield, Macquarie Park, and a few others. On top of that, we also have capacity in wholesale investments, one of them being hvlhotels.com.au, which we’re running right now.

Day 2: Where the Deals Get Done

Interviewer: Adam, how did day two feel different from day one?

Adam: It was very different for us, because we presented on day two early in the day, directly after the first keynote, which was a fascinating window into the pharmaceutical industry and the opportunity around cancer treatments. The room was full when we presented. We did have a couple of technical issues, but we managed them in our stride, and after our presentation we were practically inundated with enquiries from both suppliers and investors. It was a really, really busy day for us.

Interviewer: Adnan, did investors approach Investing Platform proactively on day two?

Adnan: Yes — there was a lot of enthusiasm actually in the room. The main draw was obviously the negatively geared property on the front end. But in the last two minutes, Adam and I showed investors our back-end agentic operating system, which shows how an organisation can be run with AI agents on the back end, and there was a lot of interest in that.

“In the last two minutes, we showed investors how an organisation can be run with AI agents on the back end… there was a lot of interest in that.”  — Adnan Tanveer

Interviewer: Adam, who is the core investor profile of Investing Platform? What type of wholesale investor is most aligned with what you offer?

Adam: Our archetypal investor is someone who runs their own self-managed super fund, or has significant wealth, and is looking to create either passive income or capital uplift. They’re probably a level below the family office although we’re very happy to deal with family offices too. They’re looking for something that provides a better return than the banks, but not something they have to consistently manage, like a trading floor or a share portfolio. Something they can invest in and watch the income returns or the dividends tick up, without too much work at their end.

The Road Ahead

Interviewer: Adnan, how did the conference close out? What was the mood at the end of day two?

Adnan: The mood at the end of day two was actually quite uplifting. Everyone was buzzing, exchanging contacts and talking about how they could do business with one another. We actually met a lot of interesting people, and there are a lot of opportunities ahead for both wholesale and retail investors moving forward, especially in brand-new properties.

Interviewer: Adam, Wholesale Investor has flagged Velocity Conference 2026 as the next major event. Will you be there?

Adam: We’re still evaluating it, but the Velocity offer looks really good, particularly given the amount of work we do with AI, and especially on the back end. What was interesting for people who saw our presentation was the work we’ve done with our agentic systems, and Velocity has a heavy AI bent, so it feels like it would be a very natural fit for us.

About Investing Platform

Investing Platform is a Sydney-based investment platform connecting wholesale and sophisticated investors with curated, brand-new residential development opportunities. Co-founded by Adnan Tanveer and Adam Newman, the platform brings over 20 years of combined financial services experience and more than $180M in facilitated transactions. Investing Platform serves investors as defined under the Corporations Act 2001.

Visit: www.investingplatform.com.au

Disclaimer: This article contains forward-looking statements based on current assumptions. Actual results may differ materially. This is not financial advice. Investing Platform serves wholesale and sophisticated investors only as defined under the Corporations Act 2001.

Media Contact:

Adnan Tanveer

info@figure8capital.com.au

Suite 3, 1 Box Road, Caringbah NSW 2229
aiNTEL Launches Expanded Unified Global Entity Intelligence Platform, Closing Gaps Left by Legacy Compliance Platforms

WASHINGTON, D.C. — aiNTEL, a Washington, D.C.-based intelligence firm providing AI-driven risk and compliance infrastructure to government and private-sector clients, today announced an expanded release of its global entity intelligence platform, addressing long-standing gaps left by traditional screening, OSINT, and AML vendors. The company’s proprietary InGrav AI engine, paired with a 25-year curated global data lake, now delivers enhanced real-time subterranean risk surfacing, anomaly detection, automated network mapping, and fully explainable, audit-ready intelligence across financial crime, AML, fraud, sanctions evasion, and enterprise risk.

For more than two decades, commercial banks, fintechs, and global enterprises have patched together fragmented solutions. Legacy screening databases offer breadth without context. Standalone OSINT tools surface disparate signals without interpretation. AI challengers deliver speed without transparency or domain-specific precision. And most enterprise platforms require multi-year implementations and heavy R&D overhead before producing value.

aiNTEL dissolves those trade-offs inside a single, mature, operational platform with 25 years of field validation in the world’s most dynamic, high-tempo environments. The InGrav AI engine pairs real-time anomaly detection and network graph generation with transparent, audit-ready outputs, giving compliance, risk, and investigations teams the rare combination of speed and defensibility that regulators now expect, while bypassing the development lead times and implementation risk associated with most enterprise compliance transformations.

“Most of the market is selling standalone fragments of the solution without understanding the broader operational context in which these capabilities will be deployed now and in the future,” said Dr. Ryan Clarke, Executive Director – Strategy and Solutions at aiNTEL. “Our partners do not need another context-free raw data feed, another generalized dashboard, or another prototype that has been adapted from a completely different domain area. They need decision-grade intelligence across the entire risk surface, delivered the moment it is needed, and defensible the moment it is challenged. That is the white space aiNTEL was purpose-built to lead. This is only possible through aiNTEL’s unique combination of having built the world’s most extensive global data lake over a 25-year period that simultaneously interacts directly with our global AI-driven OSINT capabilities that pull risk data 24/7 from all over the world, including in contested and denied information environments.”

Where competitors overspecialize without strategic differentiation, aiNTEL converges multiple categories into one platform that generates a 360-degree fully entity-resolved profile, continuously monitored and adapted. Background screening and due diligence sit alongside network discovery, beneficial ownership analysis, adverse media monitoring, and live anomaly detection.

The result is a strategic operating system for global entity intelligence. Commercial and investment banks, central banks, and international wire transfer providers use aiNTEL to accelerate AML screening, detect sanctions evasion, and power investigations. Fintechs deploy institutional-grade compliance without institutional-grade timelines. Global enterprises screen counterparties, vendors, and partners across jurisdictions and languages with full audit trails attached.

As regulatory scrutiny, cross-border financial crime, and AI-enhanced fraud rise, aiNTEL expects demand for unified, explainable, immediately deployable intelligence infrastructure to grow exponentially.

About aiNTEL

aiNTEL is a Washington, D.C.-based leader in global open-source entity intelligence. Powered by the proprietary InGrav AI engine and a 25-year curated global data lake, aiNTEL provides AI-powered risk and compliance infrastructure for the world’s most demanding private-sector environments.

CreditCube Guide: Why Is Personal Finance Dependent Upon Your Behavior?

Whether personal finance is dependent upon your behavior becomes clearer if you can figure out how your everyday habits impact your finances. Imagine two friends, Daniel and James, earn the same monthly salary and live in the same city. After payday, Daniel spends and depends on loans whenever money runs short.

James follows a different approach. He practices budgeting, builds saving habits, and plans his financial goals carefully. Months later, both face emergencies. Since Daniel has no emergency fund, he may consider borrowing options from online lenders like CreditCube. But James was able to solve his emergencies from his savings account. Even when he has to borrow, it is only a small amount.

From their behavior, you can notice that their financial outcomes were strongly influenced by their money habits. But then, let’s look at how personal finance relies directly on your actions. And also, why is it dependent on behaviors?

What Does Personal Finance Include?

The moment you start working and earning, you already begin your personal finance journey. And this journey will have you partaking in the following:

  • Budgeting. This is the process of planning how to allocate your income across expenses, savings, and other financial goals.
  • Saving. This means setting aside money for future use.
  • Borrowing. Getting the money you need from a friend or lender with an agreement to repay it later. If you have bad credit or need urgent funds, options like personal loans from online lenders may also be considered when traditional borrowing is difficult.
  • Credit Management. Credit management involves how you use borrowed money. It includes paying bills on time and keeping credit usage low.
  • Debt Repayment. The process of paying back money owed to lenders or creditors.
  • Insurance. This means entering a legal contract where you pay regular fees (premiums) into a shared pool. In return, the insurer assumes the financial risk of specific emergencies, protecting you from crippling out-of-pocket costs.
  • Investing. This means putting money into assets like stocks, bonds, or businesses to grow wealth over time.
  • Emergency Planning. This involves preparing financially for unexpected situations like job loss or medical challenges.
  • Retirement Planning. This is the process of saving and investing money to ensure you have enough income when you are no longer earning a salary.

Note: Each of these depends on financial habits and consistent financial activity.

Why Is Personal Finance Dependent Upon Your Behavior?

Personal finance is dependent on your behavior because your actions determine how you use it. This is because even with a good income, poor behavior leads to weak financial security. Two key behavior phases shape personal finance:

1. Behavior before making money. This refers to building financial literacy and habits you develop while preparing to earn. It includes learning professional skills and building career discipline, such as goal-setting and execution.

2. Behavior after making money. This refers to how you manage money once you start earning. It includes spending habits, saving, investing, borrowing, and financial decisions.

The table shows the personal finance behavior of two people who earn the same salary.

Person Behavior Outcome
James Uses budgeting, builds an emergency fund, practices automatic transfers, and has different investments. Strong financial well-being, less debt stress, and financial stability even during emergencies.
Daniel No budget, weak savings, poor spending habits, and no planning. Debt stress and unstable financial outcomes.

The Main Behaviors That Shape Personal Finance

While no single behavior shapes personal finance on its own, there is one that connects them. And that is the spending behavior. It is the connection in personal finance because it influences how much you save and whether you stay within a budget. The moment money enters your account, decisions begin. Should I pay bills first? Go shopping? Save part of it? Invest in a business or stocks? Buy property? Upgrade my lifestyle?

So in reality, personal finance often comes down to the choices made after earning money. Two people can earn the same income and still end up in very different financial situations because they spend differently.

How Emotions Influence Financial Decisions

Emotions can change the way people use money. Feelings like fear, happiness, stress, excitement, or pressure can affect how people spend, save, borrow, or invest money. This happens because the brain likes shortcuts when making hard decisions.

For example, a person who feels sad or stressed may buy things just to feel better for a short time. He or she may avoid saving or investing money out of fear. They may also panic and make bad choices when things go wrong.

Friends and social media can also affect spending and financial well-being. A person may see others buying expensive things and feel they need the same items, even if they cannot afford them. This is sometimes called the fear of missing out (FOMO).

Nevertheless, you can make better money choices by planning before spending. Make it a financial norm to follow a budget instead of letting emotions decide for them.

Common Money Behaviors That Hurt Financial Progress

An economic data report shows that total U.S. household debt reached about $18.8 trillion in the first quarter. Credit card balances alone climbed to around $1.17 trillion. These figures raise an important question: Are families borrowing money only because of emergencies? Or are their spending habits also causing money challenges?

Some families borrow money for medical bills or car repairs when their savings are not enough. Others get into debt because of habits like spending or not planning their budget well. Over time, these habits can make money problems worse.

These behaviors include:

  • Spending before saving.
  • Ignoring budgeting
  • Weak saving discipline
  • Ignoring existing debt balances.
  • Paying only the minimum credit card amounts.
  • Taking loans without a clear repayment plan.
  • Making financial decisions under pressure.
  • Comparing lifestyle with others.
  • No emergency fund or insurance coverage.

Positive Behaviors That Improve Personal Finance

Below are deliberate actions that can transform your financial life.

  • Track Spending Weekly. Review your transactions every weekend. This keeps your budget accurate and prevents end-of-month surprises.
  • Automate Savings. Schedule automatic transfers to move money into your savings account right after payday. This ensures you save before you have a chance to spend.
  • Build a Starter Emergency Fund. Aim to save an initial buffer. This safety net handles certain emergencies without forcing you into debt.
  • Compare Loan Costs First. Always analyze the APR and repayment terms before signing any credit contract. Checking the total cost of borrowing saves you money.
  • Pay Bills on Time. Set up calendar alerts or automatic payments for your recurring bills. Prompt payments eliminate late fees and support good credit health.
  • Review Credit Reports. Check your credit history annually for errors. Catching mistakes early protects your access to competitive interest rates.
  • Create a Debt Payoff Plan. Use structured strategies like the debt snowball or debt avalanche to pay down outstanding balances faster.
  • Pause Before Major Purchases. Wait 24 to 48 hours before buying non-essential items. This simple pause helps you separate temporary wants from actual needs.

Is Personal Finance More About Behavior Than Income?

Personal finance is more about behavior than money because how people act with money matters a lot. It is not only about how much money someone earns. It is about what they do with it.

For example, a person who saves money, spends carefully, and plans ahead can do well even if they do not earn much. But someone who earns a lot and spends carelessly may still end up in debt or have money challenges.

This means good money habits can help you stay safe with money for a long time. Income provides opportunity, but behavior determines results. Without good financial habits, even a high income cannot guarantee strong financial security.

How to Change Your Financial Behavior

If you are not satisfied with your current financial situation or want to make it better, you need to start by adjusting your financial habits. For example, if impulse spending happens after payday, move money to savings first. This helps you to kill that craving and urgent urge to spend when you have money.

You can upgrade your financial habits by following this step-by-step framework.

  • Pinpoint a specific action that consistently hurts your budget.
  • Track when it happens or the emotional triggers behind the habit.
  • Create an explicit boundary to disrupt the negative pattern. For example, establish a rule stating the following: “I must wait 48 hours before purchasing anything that is not on my grocery list.”
  • Remove human willpower from the equation entirely.
  • Dedicate a time at the end of every month to audit your transactions and review budgets.
  • Set clear financial goals and improve financial literacy
  • Strengthen saving consistency

Final Thoughts

Personal finance is dependent upon your behavior because your daily choices turn your income into either long-term stability or chronic stress. By adjusting your mindset, automating your savings, and pausing before major purchases, you can master your behavior and build genuine financial security. It does not require perfection, only consistent decisions repeated over time.

FAQ Section

Why is personal finance dependent upon your behavior?

Personal finance depends on your behavior because your actions control how you spend, save, borrow, repay debt, and plan. While having strong financial literacy helps, your daily choices and financial habits ultimately determine your long-term financial outcomes.

How does your behavior affect personal finance?

Your behavior shapes your daily budgeting, debt accumulation, credit health, and savings consistency.

Is personal finance mostly about income?

Income sets your initial financial potential, but personal finance is deeply dependent upon your behavior and how you manage that income.

What behaviors improve personal finance?

You can improve your financial well-being by tracking your expenses weekly, automating savings, and paying bills on time to maintain access to credit.

Why do people make bad financial decisions?

People often make poor choices due to emotional triggers like stress, spending, social pressure, and the fear of missing out (FOMO). Cognitive biases, present bias, a lack of clear budgets, and avoiding bank statements out of anxiety also cause people to make harmful choices under pressure.

Contact Person

Peter Chijioke

Email

support@creditcube.com

Company Name

Sensete LTD