The specific behavioral metrics that trigger elite casino VIP program invitations

Casinos do not just guess when upgrading players to their top tiers; they rely on hard data. Securing an invitation to an exclusive VIP program requires more than occasional high-stakes wagers. Management teams monitor specific metrics to identify long-term value, focusing on predictable patterns over unpredictable spending sprees. Understanding these exact behavioral markers gives players a clear view of how loyalty programs evaluate their activity and decide who receives the highest level of service.

The role of frequency and session length

VIP managers look closely at how often a player logs in and how long they stay at the tables or slots. A player who visits three times a week for two hours each session often scores higher in loyalty algorithms than someone who plays for ten hours straight once a month. This metric reveals engagement and genuine interest.

Consistency in attendance tells the casino that their venue is a primary source of recreation for the player. Canadian players who make gaming part of their regular weekend routine tend to trigger automated VIP reviews faster than erratic visitors. Proving reliability over several months sets a strong foundation for an upgraded account status.

Betting consistency over pure volume

Many players mistakenly believe that one massive bet guarantees an immediate upgrade. However, average bet size paired with consistency is the actual metric that alerts VIP hosts. If a player maintains steady, moderate-to-high wagers across multiple sessions, the system flags them as a sustainable VIP candidate. During regular gameplay evaluations, representatives at Mr.Bet prioritize sustained betting patterns far more favorably than sporadic high-roller activity. Evaluating a player’s average wager size helps the management team separate thrill-seekers from dedicated patrons.

Casino hosts track the following betting behaviors to identify consistent VIP candidates:

  • Average bet stability: Maintaining a relatively narrow range of bet sizes instead of jumping between minimum and maximum limits.
  • Turnover rate: The total amount of money wagered over a specific period, regardless of whether those individual bets won or lost.
  • Re-wagering habits: How often a player takes their winnings and puts them back into active play during the exact same session.

Deposit patterns and withdrawal behavior

The way a player funds their account and handles payouts provides critical insight into their overall value. VIP programs want to attract players who manage their bankroll smoothly without creating excessive administrative work.

Deposit frequency

Regular, predictable deposits signal strong account health. A player making steady weekly deposits is highly attractive to a VIP program because it shows the player has a set entertainment budget. Conversely, players who make dozens of micro-deposits in a single night may trigger responsible gaming alerts rather than VIP consideration.

Bankroll management style

Casinos also analyze the ratio of deposits to withdrawals. Players who instantly withdraw every minor win are less likely to receive elite invitations compared to those who keep a working balance in their account. Leaving funds available for future sessions demonstrates an ongoing commitment to the venue and reduces transaction costs for the operator.

Behavioral Metric Standard Player Profile VIP Candidate Profile
Play Frequency Sporadic, irregular visits Predictable, consistent sessions
Bet Sizing Erratic swings from minimum to maximum Stable, moderate-to-high average bets
Account Funding Dozens of micro-deposits in one night Regular, predictable weekly deposits
Withdrawal Habit Instantly cashes out every minor win Maintains a working balance for future play

Game selection and risk tolerance

Not all casino games contribute equally to a VIP profile. The house edge varies significantly between titles, and VIP metrics account for this discrepancy. A player who exclusively places low-risk, even-money bets on European Roulette will need a much higher turnover to reach elite status compared to an avid slot player.

Risk tolerance is a major behavioral indicator. Algorithms track whether a player takes calculated risks or sticks exclusively to the absolute safest options. Those who engage in higher-variance games often move up the loyalty ladder much faster because their playstyle aligns with higher profitability margins.

Several game selection metrics heavily influence how quickly a player receives a premium invitation:

  • Game type distribution: The percentage of time spent on high-margin games versus low-margin strategic card games.
  • Feature buy utilization: How frequently a player purchases bonus rounds, indicating a willingness to spend more for immediate entertainment value.
  • Table game betting spreads: The variation between a player’s lowest and highest bets during live dealer sessions, which showcases their risk appetite.
  • Tournament participation: Active engagement in site-wide competitions, proving that the player interacts with community-focused events.

Communication and responsiveness

While financial metrics drive the bulk of VIP decisions, behavioral engagement plays a surprisingly large role. Account managers track how players respond to standard promotional emails, text messages, and customer support interactions. Polite, responsive players who actively claim customized bonuses show that they value the relationship.

If a player regularly ignores communications or is overly demanding with support staff, they might be skipped over for a VIP invite, regardless of their spending level. The elite tier is ultimately a relationship-based service, and managers want to invite patrons who will be pleasant and collaborative to work with.

Achieving the final milestone

Earning a spot in an elite casino program comes down to proving sustained, long-term value rather than just flashing cash. By maintaining consistent session lengths, stabilizing average bet sizes, and engaging in predictable deposit routines, players naturally align themselves with the metrics that trigger automatic upgrades. The ultimate goal for management is to identify reliable patrons, and players who organically fit that profile will eventually find an exclusive invitation waiting in their inbox.
How a Casino Earns a Player’s Trust in the First Ten Minutes

Choosing an online casino is a lot like walking into a new shop: within minutes, you decide whether the place feels reliable or whether something seems off. For online gambling platforms, those first ten minutes matter even more because players are about to share personal data and real money. A casino that fails to reassure visitors early rarely gets a second chance. One that communicates openly can turn a curious newcomer into a loyal customer.

Why the First Ten Minutes Shape a Player’s Entire Opinion

Research on web usability consistently shows that users form impressions of a website within seconds. Online casinos face an especially skeptical audience. Many players have heard stories about delayed withdrawals, confusing bonus rules, or unlicensed operators that vanish overnight. As a result, every new visitor arrives with a mental checklist.

During those opening minutes, a player usually browses the homepage, scans the game lobby, checks the bonus offer, and looks for payment information. Each step either confirms that the site is legitimate or raises a red flag. The casino’s job is to answer the player’s unspoken questions before doubt settles in.

Licensing and Security Signals Players Check Right Away

The first thing an experienced player looks for is proof that the casino operates legally. Reputable sites display their license information in the footer, often with a clickable seal that leads to the regulator’s official register. Well-known regulators include the UK Gambling Commission, the Malta Gaming Authority, and the Curaçao Gaming Authority, which has been reforming its licensing system to raise standards. A license number that cannot be verified is one of the clearest warning signs.

Security comes next. Before signing up, careful players typically confirm:

  • A valid SSL/TLS certificate, shown by the padlock icon and “https” in the browser address bar.
  • A license number that matches the entry in the regulator’s public database.
  • Clear terms and conditions and a privacy policy that are easy to find.
  • Company details, such as the registered operator name and address.
  • Logos of independent testing agencies like eCOGRA, iTech Labs, or Gaming Laboratories International (GLI).

When these elements are visible without digging, the player feels the casino has nothing to hide.

Transparent Bonus Terms That Do Not Hide the Real Cost

A generous welcome bonus attracts attention, but it can also destroy trust if the conditions are buried in fine print. Wagering requirements, maximum bet limits, game contributions, and expiry dates determine whether a bonus is genuinely valuable. Casinos that summarize these rules next to the offer show respect for the player’s time and intelligence.

Regulation is pushing the industry in this direction, too. In the UK, the Gambling Commission capped wagering requirements on bonuses at 10x from January 2026. Even in markets without such caps, players increasingly compare offers based on their real cost rather than their size. The difference between a trustworthy and a questionable presentation is often easy to spot:

Trust-Building Practice Warning Sign
Wagering requirement shown next to the bonus Wagering terms hidden deep in the general T&Cs
Clear list of eligible games Vague wording like “selected games” with no list
Stated maximum bet while wagering Unexplained bonus forfeits after a large bet
Visible expiry period No information on how long the bonus lasts
Option to decline the bonus Bonus applied automatically with no opt-out

Payment Options and Withdrawal Clarity from the Start

Deposits are rarely the problem; withdrawals are. A casino that clearly lists processing times, withdrawal limits, and any applicable fees removes a major source of anxiety. Familiar payment methods also reassure players, because these providers have their own compliance standards. These include Visa, Mastercard, e-wallets like Skrill and Neteller, bank transfers, and in some cases, cryptocurrencies.

Identity verification, often called KYC (Know Your Customer), is another area where honesty pays off. Regulated casinos must verify identity to prevent fraud and money laundering. Problems arise when players discover this only at the moment they try to cash out. Explaining the process upfront, ideally during registration, turns a potential frustration into a sign of professionalism. Platforms such as Hitnspin Casino show how this works in practice, presenting payment limits, timelines, and verification steps clearly so players know exactly what to expect before their first deposit.

Customer Support That Answers Before Doubts Grow Bigger

Even a well-designed site cannot answer every question, which is why support quality plays a huge role in early trust. Many players test customer service before registering by asking a simple question in live chat. A fast, polite, and accurate reply tells them that help will be available if something goes wrong later. A slow bot loop or a generic answer does the opposite.

Strong support usually combines several channels. A 24/7 live chat handles urgent issues, email covers detailed requests, and a well-organized FAQ lets players find answers on their own. Support in the player’s language also makes a noticeable difference, especially on international platforms.

Fair Games, Responsible Gambling Tools, and Honest Design

The game lobby is where trust becomes tangible. Titles from established studios such as NetEnt, Pragmatic Play, Play’n GO, and Evolution signal that the casino works with licensed, independently tested providers. Displaying return-to-player (RTP) percentages in the game information panels adds another layer of transparency.

Responsible gambling tools are equally important, even for players who never plan to use them. Deposit limits, session reminders, cool-off periods, and self-exclusion options show that the casino cares about player wellbeing rather than only revenue. Honest design also matters. That means no fake countdown timers, no misleading “jackpot just won” pop-ups, and no pressure tactics pushing players to deposit immediately.

Turning a Short First Visit into a Lasting Relationship

Trust in online gambling is built quickly but lost even faster. In the first ten minutes, players look for:

  • A verifiable license;
  • Solid security;
  • Fair bonus terms;
  • Clear payment rules;
  • Responsive support;
  • Fair games backed by responsible gambling tools.

Casinos that deliver all of this openly give newcomers a reason to stay. Those that hide key details push them away almost instantly. Ultimately, a casino that treats transparency as standard practice earns the lasting confidence that keeps players returning.

How Bonuses Work at a Modern Online Casino

Bonuses are one of the first things players notice at an online casino. Welcome packages, free spins, and cashback deals appear on almost every homepage, each promising extra value. Behind every offer, however, is a set of rules that decides what that value is really worth. This guide explains how casino bonuses are structured, what the terms mean, and how to use them with confidence.

Why Casinos Offer Bonuses and What Players Gain

Online casinos operate in a highly competitive market, and bonuses are their main tool for attracting and keeping customers. A welcome offer encourages new players to sign up, while reload deals and loyalty rewards give existing members a reason to return. For the operator, a bonus is a marketing cost balanced by the house edge built into every game. For the player, it provides extra playing time, a chance to try new titles, and a small cushion against early losses.

A bonus is rarely free money you can withdraw right away. Most offers come with conditions you must meet before winnings become withdrawable cash. Once you understand this exchange, you can judge each promotion on its real merits.

The Most Common Bonus Types at Online Casinos

Modern casinos use several bonus formats, each suited to a different playing style and usually carrying its own terms. A free spins package, for example, often restricts you to one slot, while cashback may have lighter conditions.

Below is an overview of the formats you are most likely to see:

Bonus Type How It Works Typical Conditions
Welcome deposit match The casino matches a percentage of your first deposit, such as 100% up to a set amount Wagering requirements, minimum deposit, time limit
Free spins A set number of spins on selected slots Winnings are often subject to wagering and a cap
No-deposit bonus Small credit or spins given just for registering Strict wagering and low withdrawal limits
Reload bonus A deposit match for returning players Similar to welcome offers, often smaller
Cashback A percentage of net losses returned over a period Usually lower or no wagering
Loyalty and VIP rewards Points or perks earned through regular play Tier levels and point conversion rules

Many platforms collect active offers on a dedicated page so players can compare them easily. You can see an example of such a section at https://bruce.bet/user/bonus, where available promotions and their conditions are listed together.

Wagering Requirements and the Fine Print Explained

Wagering requirements, sometimes called playthrough, are the most important term attached to any bonus. They tell you how many times you must bet the bonus amount, or sometimes the bonus plus deposit, before you can withdraw related winnings. For instance, a $100 bonus with a 35x requirement means placing $3,500 in total bets. Requirements commonly range from about 20x to 50x, though they vary by casino and region. Lower numbers are better because they make the bonus easier to clear.

How Game Weighting Affects Your Bonus Progress

Not every bet counts equally toward wagering. Casinos assign each game category a contribution percentage. Slots typically contribute 100%, meaning a $1 spin reduces your requirement by $1. Table games such as blackjack or roulette often contribute only 10% to 20%, and some are excluded entirely. Live dealer games may also be restricted, so checking the weighting table before you play can save a lot of frustration.

Time Limits, Maximum Bets, and Withdrawal Caps

Most bonuses must be cleared within a fixed period, often between 7 and 30 days. If the deadline passes, the bonus and its winnings are usually removed. Many casinos also set a maximum bet while a bonus is active, frequently around $5 per spin or round, and breaking this rule can void your winnings. No-deposit offers and free spins often include a cap on how much you can withdraw. Reading these details first helps you avoid unpleasant surprises.

Practical Tips for Claiming Casino Bonuses Wisely

A smart approach starts with reading the terms rather than focusing on the headline number. A smaller offer with fair conditions can deliver more real value than a huge package with steep requirements. Your preferred games also matter, since a slots-focused bonus may not suit someone who mainly plays blackjack. Above all, bonuses are meant to extend entertainment, not to push you into betting more than you planned.

These habits will help you get the most from each promotion:

  1. Read the full terms, including wagering, game weighting, and expiry dates.
  2. Compare the actual playthrough amount instead of the advertised bonus size.
  3. Choose offers that match the games you already enjoy.
  4. Respect maximum bet limits to keep your winnings valid.
  5. Check whether a promo code is required before depositing.
  6. Set a budget and use deposit limits or time-out tools if needed.
  7. Play only at licensed casinos with clear and transparent rules.

Making Every Casino Bonus Work in Your Own Favor

Casino bonuses can add real value when you understand how they work. Welcome matches, free spins, cashback, and loyalty rewards each serve a different purpose, and their worth depends on the conditions attached. Wagering requirements, game contributions, time limits, and bet caps decide whether a bonus is practical or mostly decorative. By reading the terms carefully and choosing offers that fit your style, you turn promotions into a genuine advantage.

Before claiming your next bonus, take a few minutes to review its rules and set a clear budget. A well-chosen offer, used within sensible limits, can make your time at any online casino more rewarding and enjoyable.

Push Notifications in Online Gambling: Engagement Without the Irritation

Your phone buzzes during a lecture: a casino app announces free spins on online slots, the third message today. For people who play now and then, push notifications are how casino apps fight for attention. Done well, they flag a casino bonus worth claiming; done badly, they become noise that leads straight to the uninstall button. This article shows how online casinos can stay engaging without becoming irritating.

Why Push Notifications Matter in Online Gambling

Mobile gambling is a busy market, and apps fight to bring players back. Push notifications are the fastest way to do it: one tap drops the user into the lobby, where online slots, live dealer tables, and other casino games are a swipe away. Operators use them to share promotions, remind players about unfinished wagering, or point out new games. For weekend players, one well-timed message can mean opening the app instead of forgetting it. The channel is cheap, instant, and easy to measure, so most gambling apps rely on it. Available on iOS and Android, the Slotoro app comes from an operator that launched in 2023 under a Curacao licence and treats notifications as part of a wider service that also includes table games, live casino, insta games, and a sportsbook with esports markets.

The Thin Line Between Engagement and Annoyance

The same speed that makes push notifications useful also makes them risky. Notification fatigue is real: a phone lighting up five times a day trains the brain to treat every alert as spam. Research consistently links message overload to people switching notifications off or deleting the app.

Several things turn a helpful message into an irritating one:

  • Alerts arriving during lectures, exams, or late at night.
  • Generic promos that ignore the games a player actually opens.
  • The same casino bonus repeated daily with no new value attached.
  • Clickbait wording that overpromises and underdelivers in the fine print.
  • Messages that keep coming after the player has stopped opening the app.

Preferences form fast. A player who enjoys online slots after work may mute everything except major bonus alerts within a week. Once back in, the Slotoro login takes seconds, but the decision to keep notifications on depends on whether the messages earned it. Operators who respect player choices keep their audience; those who blast through lose it.

Push Notification Strategies That Actually Work

Getting notifications right is less about clever copy than discipline. Successful apps treat attention as a limited resource and build rules around it. Every push spends a little trust, and trust refills far slower than it drains.

Timing and Frequency Caps

Send times should match real life. Evenings and weekends work better for casino content; weekday mornings are a dead zone for most players. Frequency caps matter too: limiting promotional pushes to a few per week makes each feel like an event, not background noise.

Personalization Over Blanket Blasts

A player who only opens live blackjack has no reason to get daily free-spins alerts for online slots. Grouping players by favorite games and deposit habits lets operators send messages that feel relevant. Personalized pushes regularly beat generic blasts and make fewer people switch notifications off.

Honest Copy and Easy Opt-Outs

Short, truthful messages win long-term trust. If a casino bonus carries wagering requirements, the notification should not pretend otherwise. The settings menu should let players pick categories and switch any off in two taps.

A practical workflow helps teams decide what gets sent:

  1. Segment players by favorite games, activity level, and usual session times.
  2. Set a weekly cap, often two to four promotional pushes, and stick to it.
  3. Write short copy that states the offer plainly, without hype or false urgency.
  4. Test send times on small groups before a wide rollout.
  5. Review opt-out and uninstall data monthly, then drop what does not work.

Mobile-first features show how engagement can stay playful rather than pushy. Players can shake their phone in the app to trigger a surprise reward, while an exclusive Piggy Bank grows a personal cashback reserve based on slot play. These opt-in mechanics reward attention instead of demanding it.

Responsible Gambling and Younger Players

Push strategies carry extra weight with young adults. Students often juggle tight budgets and irregular income, making aggressive promo messaging risky, not just annoying. Reputable operators build in safeguards: deposit-limit reminders, reality checks, and zero promotional pushes to anyone who has self-excluded or is taking a break. Players must meet the legal gambling age in their country, which verification checks. If a notification ever pressures you to chase losses or play with rent money, that is a red flag about the operator, not an invitation.

What Lasting Engagement Looks Like

Push notifications are neither hero nor villain; their value depends on restraint. The apps that thrive send fewer, sharper, more honest messages and give players real control over notifications. For players who gamble occasionally, the approach is simple: adjust notification settings early, claim a casino bonus only when it fits the budget, and treat every ping as a suggestion, not a command. Engagement built on respect lasts far longer than engagement built on noise.

Financial Literacy Efforts Highlight the Importance of Understanding Pay Stubs and Tax Deductions

Financial literacy plays an important role in helping individuals and families make informed decisions about their money. From managing household expenses to planning for future goals, understanding basic financial concepts can make everyday decisions easier. One area that deserves more attention is the ability to read a pay stub and understand how taxes and other deductions affect take-home pay.

For employees starting their first jobs, young adults entering the workforce, and families managing changing expenses, knowing how to interpret a paycheck is a valuable step toward financial independence. As schools, employers, and community organizations promote practical money management, understanding payroll documents remains an essential skill.

Why Understanding a Pay Stub Matters

A pay stub provides a breakdown of an employee’s earnings for a specific pay period. It typically lists gross pay, taxes withheld, other deductions, and net pay, which is the amount an employee receives after applicable deductions. A pay stub creator can help users become familiar with how earnings and deductions are presented on a payroll statement.

Although many employees focus primarily on the amount deposited into their bank accounts, reviewing the entire document provides a clearer picture of their finances. Gross pay shows earnings before deductions, while net pay reflects the amount available for spending, saving, and paying bills.

Pay stubs may also include hours worked, overtime, pay rates, year-to-date earnings, and benefit contributions. Reviewing these details helps employees confirm that their compensation matches their expectations and employment agreements. For hourly workers, checking recorded hours and overtime calculations is particularly important.

Understanding Taxes and Common Payroll Deductions

Taxes are among the most significant deductions employees may see on their pay stubs. In the United States, federal income tax withholding, Social Security tax, and Medicare tax are common entries. Depending on an employee’s circumstances and location, state and local income taxes may also apply.

Federal income tax withholding generally depends on factors such as earnings and the information an employee provides on Form W-4. Social Security and Medicare taxes help fund federal benefit programs, while state and local taxes vary according to applicable laws.

Other deductions may include health insurance premiums, retirement plan contributions, and certain employer-sponsored benefits. Some deductions are required by law, while others depend on an employee’s benefit selections or workplace arrangements.

Reviewing a paystub template can help workers recognize common payroll categories and understand how different deductions affect their take-home pay. Employees who notice unfamiliar entries or unexpected changes should contact their payroll department or human resources representative to clarify the amounts.

Connecting Paycheck Knowledge With Everyday Budgeting

Understanding net pay provides a more reliable foundation for household budgeting. Although gross income may appear sufficient to cover monthly expenses, the amount available after deductions is generally more useful when planning everyday spending.

Individuals can use their take-home pay to estimate how much they can reasonably allocate to housing, groceries, transportation, utilities, debt payments, and savings. Reviewing several pay periods can also help identify patterns in income, particularly for employees whose hours or earnings fluctuate.

For workers with irregular schedules, overtime, commissions, or seasonal employment, comparing pay stubs can reveal how changes in earnings affect their budgets. This information can help them prepare for periods when income may be lower than usual.

Pay statements can also support longer-term financial goals. Employees who understand their retirement contributions can better evaluate how much they are setting aside for the future. Similarly, reviewing health insurance deductions can help them understand how workplace benefits affect their available income.

Preparing for Tax Season Throughout the Year

Pay stubs are useful beyond routine budgeting. Keeping them organized throughout the year can make it easier to review earnings and prepare for tax season.

Employees can compare year-to-date payroll figures with their annual wage statements, including Form W-2, when these documents become available. A w2 creator can help users become familiar with the information typically included in a W-2 document, although employees should rely on their employer-issued form when preparing their tax returns.

Understanding tax withholding is also important because the amount withheld from a paycheck is not necessarily the same as an individual’s final tax liability. The final amount depends on several factors, including total annual income, filing status, eligible deductions, and applicable tax credits.

Workers who consistently receive unexpectedly large refunds or owe substantial amounts at filing time may want to review their withholding elections. The Internal Revenue Service offers resources to help taxpayers understand withholding and estimate whether their payments are appropriate for their circumstances.

Maintaining organized payroll records can also help individuals document their income when applying for financial products, renting a home, or completing other transactions that require proof of earnings. Depending on the situation, additional documentation may be necessary.

Making Financial Education More Practical

Financial literacy programs are most useful when they connect general concepts to situations people encounter in everyday life. Lessons about saving and spending become more meaningful when participants can apply them to actual earnings, deductions, and household expenses.

Schools, employers, libraries, and community organizations can help by offering workshops on reading pay stubs, understanding tax withholding, comparing employee benefits, and establishing realistic budgets. These sessions can be especially valuable for first-time workers, recent graduates, and individuals returning to the workforce.

Digital resources can provide additional support. Online calculators, budgeting applications, and educational guides can help users estimate take-home pay and explore how different deductions affect their income. However, individuals should verify important calculations and consult qualified professionals when dealing with complicated tax or payroll questions.

Building Confidence Through Better Financial Habits

Understanding a paycheck may seem like a small part of financial education, but it can influence many aspects of everyday money management. Employees who know how to interpret their earnings and deductions are better positioned to monitor their compensation, organize financial records, and make informed decisions about spending and saving.

Developing these skills does not require advanced financial knowledge. Simply reviewing each pay stub, asking questions about unfamiliar deductions, and keeping records organized can provide a strong starting point.

As communities continue to promote financial literacy, practical lessons about paychecks and taxes can help individuals gain greater confidence in managing their money. By understanding where their earnings go and how payroll deductions work, workers can make more informed choices and build a stronger foundation for their financial futures.


Distributed By: Pulsebulletin.com

ACE Money Transfer Updates App Navigation, Transfer Tracking and Verification Screens

Updated mobile experience introduces a structured transfer process, upfront fee and exchange-rate information, and clearer visibility of outstanding verification steps.

MANCHESTER, England — October 14, 2026 — ACE Money Transfer has introduced enhancements to its mobile app covering transfer setup, recipient details, payment information, status tracking and identity verification.

The update focuses on the steps customers follow when arranging an international money transfer. Changes include a structured transfer flow and a step-by-step process for adding a new recipient.

Changes to the app experience

  • Transfer setup: A clearer sequence guides customers through the transfer process, with fees and exchange rates displayed before they commit to a payment.
  • Recipient details: A step-by-step process guides customers through adding a new receiver.
  • Transfer tracking: Customers can view transfer-status updates in the app, including when a transfer is undergoing manual review.
  • Identity verification: Updated screens show outstanding verification steps, helping customers identify what remains to be completed.
  • Offers: Active promotions are displayed more prominently within the app.

The fee and exchange-rate information gives customers visibility of the full payment amount before confirmation. Transfer tracking provides information about the stage of processing, including manual review, rather than a guarantee of the precise location of funds.

The changes concern the app interface and the information available during a transfer. They do not establish a shorter settlement time or a guaranteed delivery time. The verification changes focus on how outstanding steps are presented, rather than announcing the removal of identity checks.

“Customers want speed, clarity, and confidence when sending money internationally,” said Qamar Adnan, Chief Product Officer at ACE Money Transfer.

The announcement does not specify a platform-by-platform release schedule, eligible markets or whether deployment is complete or phased. It also does not provide measured results for changes in transfer-setup time or the number of steps required.

About ACE Money Transfer

ACE Money Transfer is a remittance provider offering international money transfer services. Its mobile app supports transfer setup, recipient management, identity verification and transfer-status tracking.

Media Detail

Contact Person Name: Media Relation
Company Name: ACE Money Transfer
Email: help@acemoneytransfer.com
Website: https://acemoneytransfer.com/ 

How to Document a Denied Texas Hail or Wind Claim

When a hail or wind claim gets denied, a Central Texas storm loss often becomes an argument about dates and what each inspection actually recorded. In Texas, the strength of your documentation usually decides whether the insurer’s stated reason can be tested at all. A renamed screenshot raises more questions than it answers. An original photograph with its capture date, or a complete inspection report, answers them. So keep the original denial letter.

Your file needs to separate what you saw when you first discovered the damage from what you wrote down later. A later note still belongs in the record, provided you say where it came from and when you made it. Just never pass it off as something written that day.

Build the file for denied insurance claims in Texas

Start with records that establish the claim and denial

Gather the policy and endorsements effective on your reported loss date, the claim acknowledgment, the denial letter, inspection reports, estimates, photographs, videos, emails, text messages, invoices, and telephone notes. Whenever possible, keep each item’s original date and sender, plus its filename and format. Set the denial next to the applicable policy, but don’t assume coverage exists. Note the insurer’s stated reason and any policy language the letter cites.

Insurers deny hail and wind claims for particular reasons, and the ones that matter here usually fall into a few buckets: a missed deadline, an unexamined roof slope, or a causation finding. Dated records can challenge any of them. Attorneys who handle denied insurance claims in Texas rely on exactly this kind of documentation, so build the file first, then decide your next move.

Document the storm damage step by step

  1. Save the denial letter and claim notices in their original electronic formats.
  2. Set up a read-only folder for originals and a separate working folder for notes or annotated copies.
  3. Preserve original photographs and videos before you edit or rename any copies.
  4. Group estimates and reports by issuer and date, and keep every revised version.
  5. Export emails and text exchanges. Follow up important phone calls with a dated email confirming what was said.
  6. Create an issue log identifying the inspected area and each evaluator’s conclusion. Mark what remains disputed.

Never overwrite the originals. Label working copies something like “north-roof-slope-annotated,” and keep the untouched file and its original metadata alongside them.

Make photographs useful as records

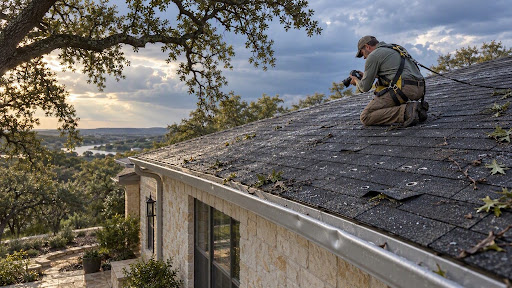
Take an overview photograph that identifies the property area, then take closer views of the visible condition. Photograph temporary repairs before and after the work, and retain invoices for tarps or other mitigation materials. Stay where you can safely stand.

A photograph documents visible conditions at a particular time, not a determination of storm causation. Record who took it and when, and identify its location on the property in a separate photo index.

How to keep a claim timeline after an insurance denial

Record events when they happen

Log the reported loss date and claim submission, followed by each information request and inspection. Include the denial and all reassessment exchanges. Link each entry to its supporting record, and keep discovery dates separate from the reported storm date.

Claim event Date and time to record Supporting record Follow-up to track
Damage discovered When the condition was first observed Original photographs or video Temporary protection and related receipt
Claim reported Submission date and confirmation time Claim acknowledgment and claim number Insurer’s information request
Property inspected Inspection date and arrival time Appointment notice and resulting report Uninspected areas or requested documents
Denial received Date delivered Complete denial letter Reason and cited policy language
Reassessment requested Date sent Email or certified-mail record Written response and inspection date

Use Texas deadlines as checkpoints, not assumptions

Under Texas Insurance Code Chapter 542, Section 542.057 generally requires payment within five business days after notice accepting a claim. Section 542.059 allows an additional 15 days for applicable claim-handling deadlines involving qualifying weather-related catastrophes or major natural disasters. Keep any catastrophe-extension notice in your file.

The Texas Department of Insurance says insurers generally have 15 business days after receiving notice to acknowledge a claim, begin investigating, and request reasonably necessary information. After receiving the required information, they generally have 15 business days to accept or reject the claim in writing. If an insurer needs more time, it generally must explain why in writing and then has up to 45 days to decide. A rejection must include a written reason. Retain the complete notice.

Record what arrived and when rather than declaring a deadline violation. Calculations can depend on requested information or a qualifying catastrophe extension, so preserve delivery confirmations and outstanding requests.

Should I get a second inspection after a denied claim?

Compare conclusions without rewriting them

A second inspection can help clarify a denied claim when the first report omitted an area or left a contractor’s documented observations unaddressed. It may also help when another qualified evaluator disputes a finding supporting the denial. A second inspection does not guarantee a changed outcome. Identify the specific finding you want reviewed, such as an unexamined roof slope.

Source Record exactly Comparison question
Contractor estimate Observed damage and proposed work; quantities and estimate date Does it address the same property area as the insurer’s inspection?
Adjuster report or denial Area reviewed and stated conclusion; cited policy wording Which findings support the written decision?
Engineer report Inspection date and materials reviewed; testing described and final opinion Which observations differ from the other reports?

Request the second inspection in writing and identify the areas or findings needing review. Reference supporting photographs by filename and reports by page number. If a contractor or another evaluator attends, separately record who was present and what each person inspected.

Keep the reports separate rather than combining them. Quote competing conclusions in your comparison notes instead of replacing them with your interpretation, and identify the source page for each quotation.

What to do after a Texas property damage claim is denied

Test the reassessment request for specificity

After an insurer denies a Texas property damage claim, send a written reassessment request identifying the claim and referencing the denial. State which findings need reconsideration and connect each point to a supporting record. Ask for a written response and retain proof of delivery.

Describe disagreements without accusations. For example: “The adjuster’s report does not address the interior ceiling condition shown in the attached photographs.” Identify the room and photograph filenames rather than alleging dishonesty.

Identify what kind of disagreement remains

Coverage concerns whether the policy applies to the reported loss. Scope concerns which damaged components are included. Value concerns the amount assigned to repair or replacement. Compare the denial with the policy and reports, then note the disputed wording in your issue log.

If a report references an attachment you never received, request it by title and date. Mark the gap “requested, not received,” and save that request.

Before asking for appraisal or another inspection, gather the governing policy, denial, and chronology. Include competing estimates alongside inspection reports and original photographs. Read the actual appraisal clause before requesting that process, because availability can depend on policy wording and the dispute. Keep questions for legal advice tied to specific documents.

Find guidance on an unresolved denial

A written reassessment request sometimes resolves a denial, and sometimes it does not. When a complete denial stands after reassessment, the next steps depend on the type of dispute, the policy’s appraisal clause, and the strength of your documentation, which is why the file you built earlier matters most at this stage.

A record another reader can follow

A useful claim file lets someone unfamiliar with your home connect each event to its original record and see exactly where conclusions diverge. You do not need to reconcile competing opinions yourself. Preserve them accurately, and clearly distinguish later recollections from observations recorded during an inspection. Unanswered requests should remain visible rather than disappearing into an email folder. The result should be a dated file containing the governing policy and denial, with an unresolved-issue log pointing to original photographs, reports, and correspondence.

Sources

  • Texas Insurance Code Chapter 542.
  • Texas Department of Insurance: Insurance claim deadlines.


Distributed By: Pulsebulletin.com

BrandingBuzz.Agency Announces Expanded Press Release Distribution Options

Distribution packages provide qualifying business announcements with opportunities for publication across financial, national, regional, and industry-focused media networks.

HOUSTON, Texas – 14th October 2026 – BrandingBuzz.Agency has announced an expanded selection of press release distribution packages for businesses, marketing agencies, and resellers, encompassing targeted placements and broader syndication through third-party networks.

The selection includes newswire distribution, regional news website placements, and individual publication options. The agency reviews submitted announcements against the requirements of the requested distribution route before proceeding. Availability depends on the announcement’s subject matter, editorial acceptance, and the policies of participating platforms.

The expansion addresses differing campaign budgets and distribution requirements. Some clients seek a particular publication, while others require syndication across multiple websites.

“Businesses often want credible online visibility but may not have the budget or resources required for a traditional public relations campaign,” said Mehboob Ali Meghani, Founder & CEO of BrandingBuzz.Agency.

Review and Reporting Process

Clients submit a completed press release for review. BrandingBuzz.Agency evaluates the content, industry, and requested distribution option, then communicates applicable requirements and restrictions. Clients approve the final release before distribution.

Following distribution, the agency supplies a report containing available live publication links. Package-specific requirements and sample reports are provided before an order is placed.

Publication details and distribution options are available on the agency’s website.

Publication Conditions

Press release placements and syndicated announcements are distinct from earned editorial coverage. Publication does not constitute an independent editorial recommendation or endorsement by the hosting website.

Placement availability, link attributes, and indexing remain subject to third-party platform policies. Distribution alone does not establish a commitment to search rankings, traffic, sales, leads, verification, or indexing; any service-specific commitment must be expressly stated in the selected service.

BrandingBuzz.Agency is not affiliated with, sponsored by, or endorsed by the publications participating in third-party distribution networks.

About BrandingBuzz.Agency
BrandingBuzz.Agency is a Houston-based press release distribution agency serving startups, entrepreneurs, established businesses, marketing agencies, and resellers. Its services include bundled distribution and selected individual placements, with content review, client approval before distribution, and reports containing live publication links.

Media Contact

BrandingBuzz.Agency
Mehboob Ali Meghani — Founder & CEO
Email: mail@brandingbuzz.agency
Website: https://brandingbuzz.agency/

The Underwriting Gap: Why Legal Businesses Keep Losing Their Card Processing

A firearms retailer with a federal license, clean books and a decade of filings can still wake up to a frozen payment account. So can a CBD brand selling products that comply with the 2018 Farm Bill, or a sweepstakes operator running promotions reviewed by counsel. None of these businesses did anything illegal. They simply fell outside the risk tolerance of the payment platform they were using, and that distinction is the single most expensive thing many founders never learn until it costs them a month of revenue.

For investors and operators tracking small-business fundamentals, this gap between legality and bankability deserves more attention than it gets. Payment access is working capital. When it disappears, so does the ability to collect, forecast and service debt.

What “High-Risk” Actually Measures

High-risk is not a moral label. It is an actuarial one. Acquiring banks and card networks classify a merchant by the probability that the bank will end up holding a loss, and they weigh a handful of inputs: chargeback frequency, average ticket size, delivery lag between payment and fulfillment, regulatory complexity, and whether the product carries reputational exposure for the brand names printed on the card.

Firearms and ammunition rank high because of jurisdictional patchwork and policy pressure, not because dealers dispute transactions more than average. CBD sits in a category where federal and state rules diverge and where testing claims invite consumer complaints. Sweepstakes draws scrutiny because prize promotions are regulated differently in nearly every state and because entrants sometimes dispute charges they later regret. Subscription models and high-ticket items add their own friction: the longer the gap between the swipe and the delivery, the longer the window for a chargeback.

Understanding the mechanics behind these classifications is worth the reading time, and plain-language explanations of how high-risk credit card processing and merchant accounts differ from standard setups give operators a useful baseline before they start comparing proposals.

The Aggregator Trap

Most of the painful terminations trace back to the same decision. A new business needs to take cards quickly, so it signs up with a payment aggregator, where onboarding takes minutes and no one underwrites the individual merchant up front. The business gets processing immediately because it is sharing a master account with thousands of others. It also inherits that account’s prohibited-business list, which typically bars firearms, ammunition, certain hemp products and prize promotions outright.

Nothing happens at first. Then a risk review, a volume spike, or a single complaint triggers a look at the account. The platform enforces its terms, the account closes, and settled funds often sit in reserve while the merchant scrambles. This structural difference between shared aggregator accounts and dedicated merchant accounts is explored in a practical comparison of choosing between merchant accounts and payment aggregators as a business grows, and the logic applies with extra force to regulated verticals.

What a Dedicated Account Changes

With a dedicated merchant account, the business holds its own merchant identification number and is underwritten as itself. The bank reviews the licenses, the product mix, the website disclosures and the processing history before approval rather than after. Onboarding takes longer, paperwork is heavier, and pricing is usually higher than the flat rates advertised by consumer-facing platforms. In exchange, the merchant stops being an exception hiding inside someone else’s agreement.

The Real Cost of a Shutdown

Operators tend to compare processing on rate alone, which badly misprices the risk. A sudden termination usually brings several costs at once: settled funds held in reserve for an extended review period, a hard stop on online revenue while a replacement is underwritten, the labor cost of re-onboarding, and the possibility of placement on the industry match list that acquirers check during underwriting. That last item is the most damaging, because it narrows future options for years.

Measured against that exposure, a slightly higher discount rate on a properly underwritten account is cheap insurance. The question is not what a merchant pays per transaction. It is what a week of frozen settlement does to payroll.

Building Processing That Survives Scrutiny

Resilient setups share a few traits. They are worth auditing against whatever arrangement a business runs today.

  • Accurate disclosure at application. Understating the product mix to clear underwriting is the most common cause of later termination. Banks find out.
  • Redundancy across multiple MIDs. Spreading volume across more than one merchant account, with load balancing between them, means a single account issue does not take the whole business offline.
  • Chargeback controls before the dispute. Clear descriptors, responsive support, delivery confirmation and documented age or identity verification where the category requires it.
  • A gateway that fits the catalog. Some gateways restrict regulated SKUs at the platform level, which creates a mismatch even when the bank has approved the merchant.
  • Compliance artifacts kept current. Licenses, lab reports, official rules for promotions, shipping policies and state restrictions, all organized and ready for review.

Where Specialist Processors Fit

General-purpose platforms are built for volume and simplicity, which means their risk departments default to exclusion rather than analysis. Specialist providers work the opposite way: they maintain relationships with acquiring banks that already understand these categories and they underwrite the specifics instead of the label. 2Accept operates in that space, placing merchant accounts for businesses that mainstream processors like Stripe, Square and PayPal routinely decline or terminate. For an FFL dealer, that can mean a firearms merchant account set up with the licensing realities of the trade already accounted for; the same approach extends to CBD retailers, sweepstakes operators, ammunition sellers and gunsmiths, alongside gateway integration, chargeback defense and multi-MID load balancing for merchants that cannot afford a single point of failure.

Questions Worth Asking Before Signing

Whoever a business talks to, a short list of questions separates a durable arrangement from a temporary one.

1. Is this a dedicated merchant account with its own MID, or placement on a shared aggregator account?

2. Which acquiring bank underwrites it, and has that bank approved this specific category before?

3. What are the rolling reserve terms, if any, and when does the reserve release?

4. What chargeback ratio triggers a review, and what happens at that point?

5. Can a second MID be added later without re-underwriting from scratch?

6. What documentation does the bank want on an ongoing basis, not just at application?

Treating Payment Access as Infrastructure

The businesses that avoid processing crises are the ones that stopped treating card acceptance as a checkout widget and started treating it as infrastructure, with the same redundancy planning they would apply to hosting or inventory. That means knowing who underwrites the account, keeping compliance documentation current, watching chargeback ratios monthly rather than quarterly, and having a second processing path tested before it is needed. For firearms dealers, CBD brands and promotional operators, the regulatory environment is unlikely to simplify. Payment arrangements built with that assumption hold up; the ones built on the cheapest available flat rate tend not to.

Why Perfectly Legal Businesses Still Lose Their Payment Processors

A gun shop in Pennsylvania sells a legal product under a federal license, keeps meticulous records, and passes ATF inspections. A CBD retailer in Colorado tests every batch and publishes the results. Both are operating lawfully. Both can wake up one morning to find their card processing switched off, their funds held for 90 to 180 days, and a form email citing a clause in a terms-of-service document they signed years earlier. No fraud. No chargeback spike. Just a category decision made somewhere upstream.

This is the quiet reality of what the payments industry calls “high risk,” and it affects far more businesses than most owners realize until it happens to them. Understanding how the designation works, and what to do about it, is now a basic operating skill for anyone in a regulated or reputationally sensitive trade.

What “High Risk” Actually Means

High risk is not a legal category. It is an underwriting judgment, and it blends several separate concerns that get bundled under one label. The first is chargeback exposure: industries with subscription billing, long fulfillment windows, or disputed delivery terms generate more disputes, and card networks penalize acquirers whose portfolios run hot. The second is regulatory complexity, where state-by-state rules mean a product can be compliant in one jurisdiction and restricted in the next. The third, and the one that frustrates merchants most, is reputational risk, which has nothing to do with the merchant’s numbers at all.

That third factor explains why firearms dealers get grouped with industries that have genuine fraud problems. An FFL dealer running a brick-and-mortar shop with a 0.2 percent dispute rate is, by any statistical measure, a better customer than most e-commerce sellers. But the aggregator processing the transaction has made a policy decision about the vertical, not an actuarial one about the merchant. The same logic applies to sweepstakes and promotional contest operators, whose business models are legitimate and heavily regulated but sit close enough to gaming in the underwriting taxonomy to trigger restrictions.

The Aggregator Trap

Most new businesses start with an aggregator, because signing up takes eleven minutes and no underwriting conversation. What they are actually joining is a shared master merchant account where thousands of businesses operate as sub-accounts under one umbrella. That shared structure is exactly why it is fast, and exactly why it is fragile. There is no individual relationship with an acquiring bank, no dedicated merchant identification number, and no underwriter who has read your business plan. Enforcement is automated and categorical, so a product-catalog crawl flagging ammunition components or hemp-derived compounds can trigger termination without a human ever reviewing the account.

The Real Cost of a Sudden Shutoff

Owners tend to think about the processing fee differential and miss the much larger costs. A reserve hold freezes working capital at precisely the moment you need it to pay suppliers. Recurring billing customers see declined cards and churn rather than call support. Advertising spend keeps running against a checkout that no longer completes. And rebuilding takes time: a properly underwritten account for a specialized business is typically a matter of days to a few weeks rather than minutes, because someone is genuinely reviewing documentation.

There is also a legal dimension that deserves more attention than it gets. Terminated merchants sometimes find themselves on a shared industry database that makes subsequent applications harder, and disputes over held funds can turn into contract claims. Specialist commercial litigation practices have grown around exactly these financial-services conflicts, and the lateral hiring moves in that field, such as litigation attorney Katherine Canning joining Dorsey, track where the disputes are concentrating. If a processor is holding a six-figure reserve, the cost of an hour with a commercial attorney is trivial by comparison.

Building Payment Infrastructure That Holds

The durable approach is to stop treating payments as a single switch and start treating it as infrastructure with redundancy. Three principles do most of the work.

  • Get your own MID. A dedicated merchant identification number means a direct relationship with an acquirer and an underwriter who already knows what you sell. Your account cannot be collateral damage in someone else’s policy sweep.
  • Do not rely on one processor. Multiple merchant accounts with traffic distributed across them means a single termination becomes a partial outage instead of a full stop. It also spreads dispute ratios across more volume rather than concentrating them.
  • Disclose everything in underwriting. Describing your product catalog vaguely to get approved faster almost always produces a termination later, and that termination is worse than a decline would have been.

On the technical side, the gateway and the merchant account are separate components, and conflating them causes real confusion during migrations. The gateway handles authorization and tokenization; the merchant account holds the funds and carries the risk relationship. Sage’s practical walkthrough of how to get a payment gateway and accept online payments is a clear primer on how those pieces connect, which is worth reading before you sign anything so you can tell which part of your stack is actually causing a problem.

When a Specialist Makes Sense

If your business sits in one of these categories, a generalist processor is a poor fit no matter how good the advertised rate looks, because the rate is irrelevant once the account is closed. Specialist providers exist precisely for this gap. 2accept works with merchants that mainstream platforms such as Stripe, Square, and PayPal routinely reject or terminate, setting up merchant accounts for FFL firearms dealers, CBD retailers, sweepstakes operators, ammunition sellers, and gunsmiths. Their offering covers the pieces that matter structurally rather than cosmetically: gateway integration, chargeback defense, and multi-MID load balancing that distributes volume across several merchant identification numbers so one processor’s policy change does not take your checkout down with it. The value in working with a provider that already understands your vertical is that the compliance conversation happens during underwriting, not during a termination review.

Questions Worth Asking Any Provider

1. Will I hold a dedicated MID, or operate as a sub-merchant under a shared account?

2. Which acquiring bank is behind the account, and have they underwritten my specific category before?

3. What are the reserve terms, and under what conditions do they change?

4. What does the dispute response workflow look like, and who assembles the evidence?

5. How quickly can a secondary MID be activated if the primary is restricted?

Treat Payments Like a Utility You Can Lose

The businesses that handle this well are the ones that stopped assuming the ability to accept a card was permanent. They keep underwriting documentation current, monitor dispute ratios monthly rather than reactively, maintain a backup processing path they have actually tested, and keep enough cash buffer to survive a reserve hold without missing payroll. None of that is glamorous work, and all of it is cheaper than the alternative. For a legal business operating in a category someone else decided to call risky, redundancy is not paranoia. It is just how the system is built, and planning around it beats being surprised by it.